Earnings results often indicate what direction a company will take in the months ahead. With Q3 behind us, let’s have a look at Accenture (NYSE: ACN) and its peers.
IT Services & Consulting companies stand to benefit from increasing enterprise demand for digital transformation, AI-driven automation, and cybersecurity resilience. Many enterprises can't attack these topics alone and need IT services and consulting on everything from technical advice to implementation. Challenges in meeting these needs will include finding talent in specialized and evolving IT fields. While AI and automation can enhance productivity, they also threaten to commoditize certain consulting functions. Another ongoing challenge will be pricing pressures from offshore IT service providers, which have lower labor costs and increasingly equal access to advanced technology like AI.
The 8 it services & consulting stocks we track reported a solid Q3. As a group, revenues beat analysts’ consensus estimates by 1.5% while next quarter’s revenue guidance was 20.1% below.
Luckily, it services & consulting stocks have performed well with share prices up 11.4% on average since the latest earnings results.
Accenture (NYSE: ACN)
With a workforce of approximately 774,000 people serving clients in more than 120 countries, Accenture (NYSE: ACN) is a professional services firm that helps organizations transform their businesses through consulting, technology, operations, and digital services.
Accenture reported revenues of $18.68 billion, up 6.2% year on year. This print exceeded analysts’ expectations by 3.5%. Overall, it was a satisfactory quarter for the company with a beat of analysts’ EPS estimates but revenue guidance for next quarter slightly missing analysts’ expectations.
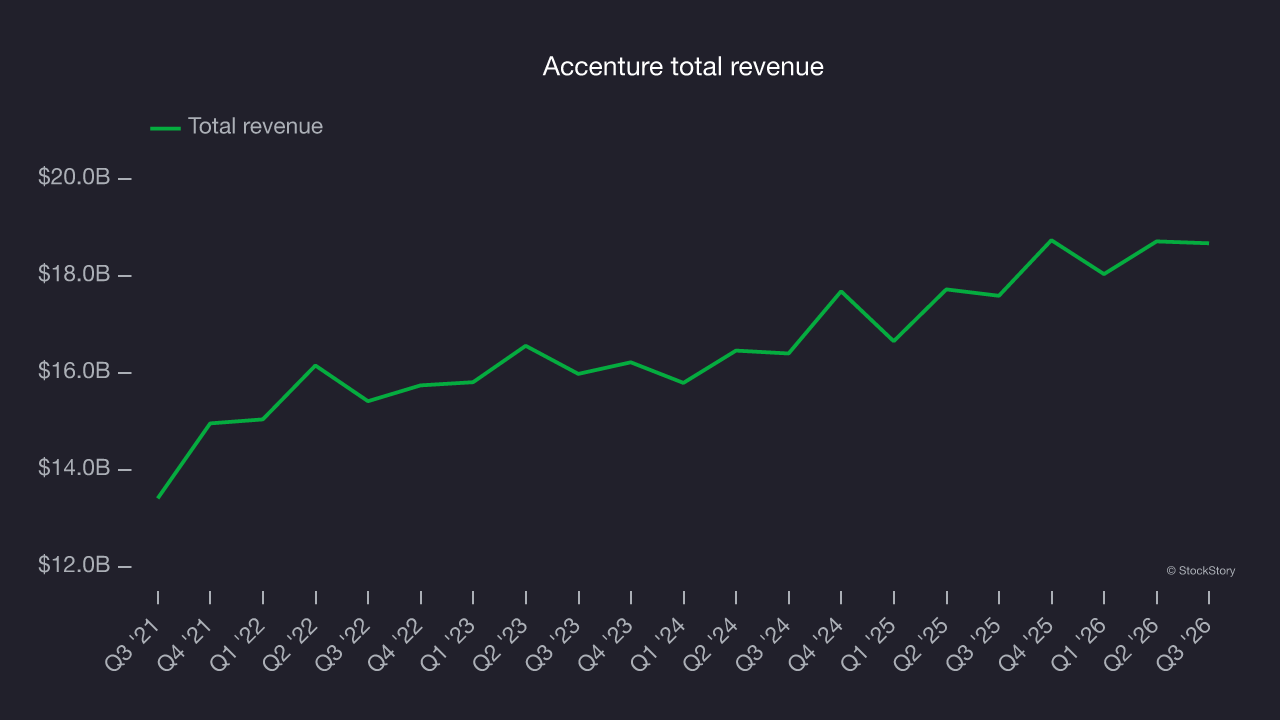
Accenture pulled off the biggest analyst estimate beat of the whole group. Unsurprisingly, the stock is up 38.8% since reporting and currently trades at $254.45.
Is now the time to buy Accenture? Access our full analysis of the earnings results here, it’s free.
Best Q3: Gartner (NYSE: IT)
With over 2,500 research experts guiding organizations through complex technology landscapes, Gartner (NYSE: IT) provides research, advisory services, and conferences that help executives make better decisions about technology and other business priorities.
Gartner reported revenues of $1.50 billion, down 1.3% year on year, outperforming analysts’ expectations by 1.2%. The business had a very strong quarter with a beat of analysts’ EPS estimates.
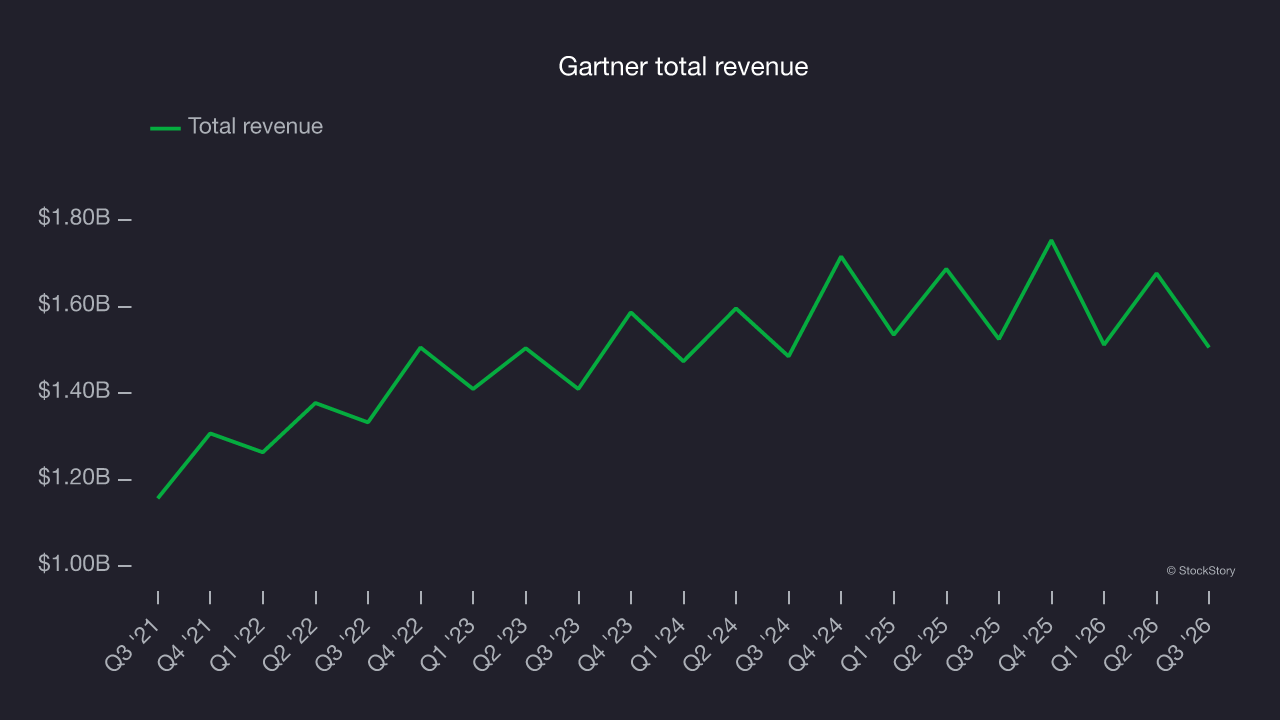
Although it had a fine quarter compared to its peers, the market seems unhappy with the results as the stock is down 18.8% since reporting. It currently trades at $190.97.
Is now the time to buy Gartner? Access our full analysis of the earnings results here, it’s free.
Weakest Q3: DXC (NYSE: DXC)
Born from the 2017 merger of Computer Sciences Corporation and HP Enterprise's services business, DXC Technology (NYSE: DXC) is a global IT services company that helps businesses transform their technology infrastructure, applications, and operations.
DXC reported revenues of $3.03 billion, down 4% year on year, exceeding analysts’ expectations by 1.3%. Still, it was a softer quarter as it posted a significant miss of analysts’ EPS guidance for next quarter estimates and full-year revenue guidance missing analysts’ expectations.
DXC delivered the weakest guidance update and slowest revenue growth in the group. The stock is flat since the results and currently trades at $15.15.
Read our full analysis of DXC’s results here.
IBM (NYSE: IBM)
With a corporate history spanning over a century and once known for its iconic mainframe computers, IBM (NYSE: IBM) provides hybrid cloud computing platforms, AI solutions, consulting services, and enterprise infrastructure to help businesses modernize their operations.
IBM reported revenues of $17.1 billion, up 4.7% year on year. This number surpassed analysts’ expectations by 1.9%. Overall, it was a solid quarter as it also produced a beat of analysts’ EPS estimates.
The stock is down 1.7% since reporting and currently trades at $247.10.
Read our full, actionable report on IBM here, it’s free.
Kyndryl (NYSE: KD)
Born from IBM's managed infrastructure services business in a 2021 spinoff, Kyndryl (NYSE: KD) is the world's largest IT infrastructure services provider that designs, builds, and manages technology environments for enterprise customers.
Kyndryl reported revenues of $3.65 billion, down 1.9% year on year. This result was in line with analysts’ expectations. It was a solid quarter as it also logged a beat of analysts’ EPS estimates.
Kyndryl had the weakest performance against analyst estimates among its peers. The stock is up 28.7% since reporting and currently trades at $16.65.
Read our full, actionable report on Kyndryl here, it’s free.
Market update
Over the past year, investors have been forced to repeatedly answer the same question: what is the market’s biggest risk? The answer has changed several times, and each shift has reshaped market leadership.
Late in 2025 and early 2026, artificial intelligence became the market’s primary uncertainty. Investors questioned whether AI would erode software pricing power and weaken competitive moats as AI made it easier to replicate once-differentiated products.
By the spring, technology took a back seat to geopolitics. The U.S. conflict with Iran briefly became the market’s dominant narrative, raising concerns about oil prices, inflation, and global growth. But as energy markets remained orderly and fears of a prolonged supply disruption faded, investors quickly turned their focus back to fundamentals.
Want to invest in winners with rock-solid fundamentals? Check out our 9 Best Market-Beating Stocks and add them to your watchlist. These companies are poised for growth regardless of the political or macroeconomic climate.