The end of an earnings season can be a great time to discover new stocks and assess how companies are handling the current business environment. Let’s take a look at how D.R. Horton (NYSE: DHI) and the rest of the home builders stocks fared in Q3.
Traditionally, homebuilders have built competitive advantages with economies of scale that lead to advantaged purchasing and brand recognition among consumers. Aesthetic trends have always been important in the space, but more recently, energy efficiency and conservation are driving innovation. However, these companies are still at the whim of the macro, specifically interest rates that heavily impact new and existing home sales. In fact, homebuilders are one of the most cyclical subsectors within industrials.
The 9 home builders stocks we track reported a softer Q3. As a group, revenues missed analysts’ consensus estimates by 1.7%.
Thankfully, share prices of the companies have been resilient as they are up 6% on average since the latest earnings results.
D.R. Horton (NYSE: DHI)
One of the largest homebuilding companies in the U.S., D.R. Horton (NYSE: DHI) builds a variety of new construction homes across multiple markets.
D.R. Horton reported revenues of $9.37 billion, down 3.2% year on year. This print exceeded analysts’ expectations by 3.4%. Despite the top-line beat, it was still a sluggish quarter for the company with full-year revenue guidance missing analysts’ expectations significantly and a significant miss of analysts’ EPS estimates.
David Auld said, "The D.R. Horton team completed our 25th consecutive year as America's largest builder by volume, and we are proud to have provided homeownership to more than 84,000 individuals and families during fiscal 2026."Share
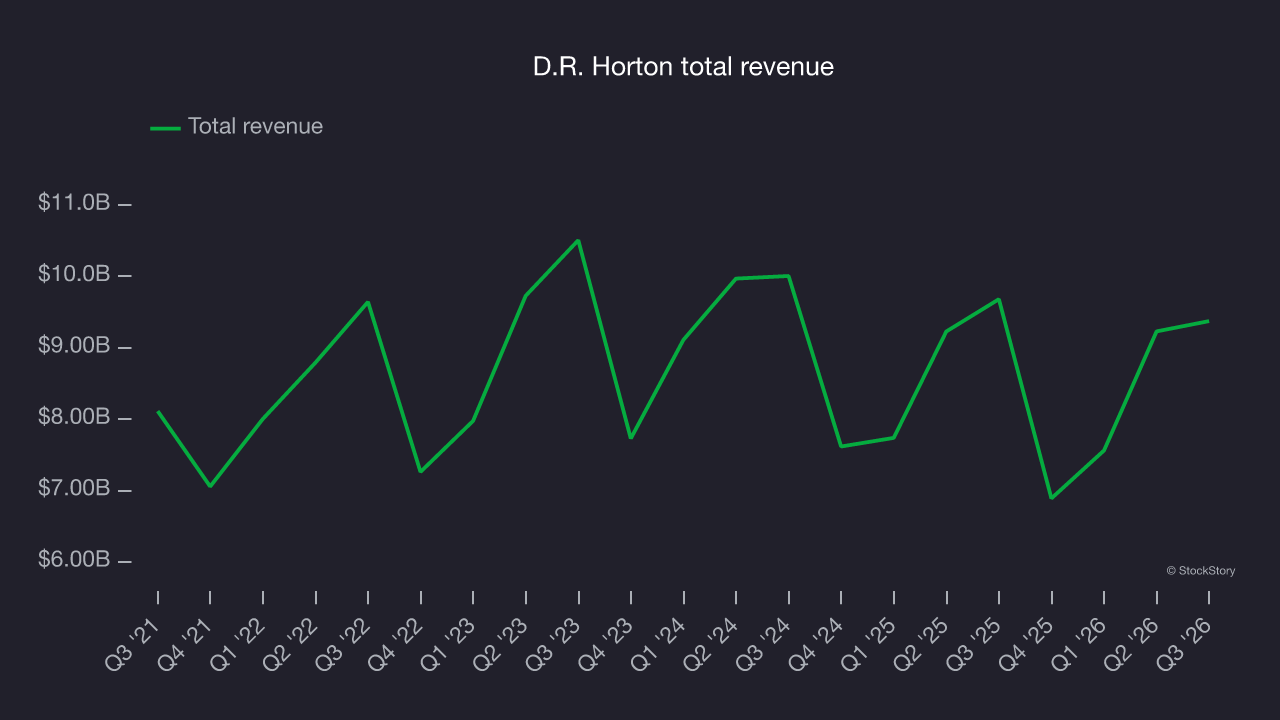
D.R. Horton pulled off the biggest analyst estimate beat but had the weakest full-year guidance update in the group. Unsurprisingly, the stock is up 6.6% since reporting and currently trades at $152.41.
Read our full report on D.R. Horton here, it’s free.
Best Q3: LGI Homes (NASDAQ: LGIH)
Based in Texas, LGI Homes (NASDAQ: LGIH) is a homebuilding company specializing in constructing affordable, entry-level single-family homes in desirable communities across the United States.
LGI Homes reported revenues of $437.5 million, up 10.3% year on year, outperforming analysts’ expectations by 1%. The business had a very strong quarter with a beat of analysts’ EPS estimates.
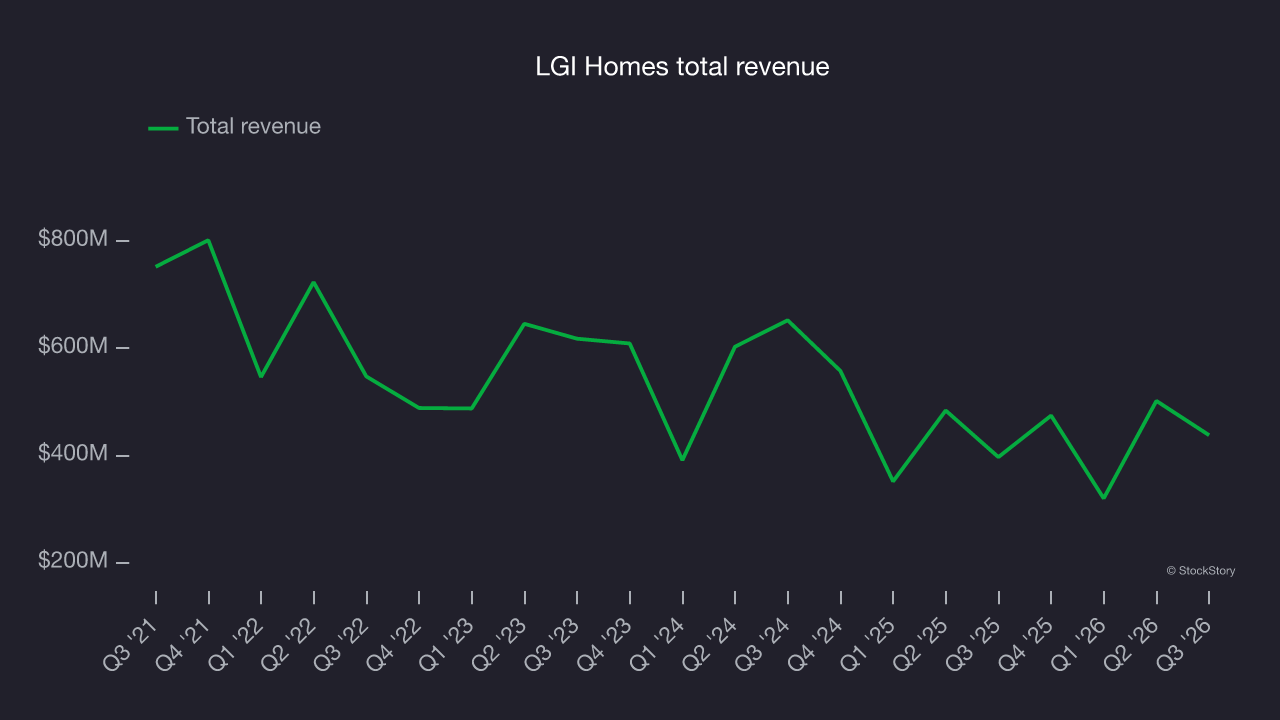
LGI Homes pulled off the fastest revenue growth among its peers. Although it had a fine quarter compared to its peers, the market seems unhappy with the results as the stock is down 3.8% since reporting. It currently trades at $45.61.
Is now the time to buy LGI Homes? Access our full analysis of the earnings results here, it’s free.
Weakest Q3: NVR (NYSE: NVR)
Known for its unique land acquisition strategy, NVR (NYSE: NVR) is a respected homebuilder and mortgage company in the United States.
NVR reported revenues of $2.40 billion, down 7.9% year on year, falling short of analysts’ expectations by 6.4%. It was an underwhelming quarter as it posted a significant miss of analysts’ EPS estimates.
Interestingly, the stock is up 6.3% since the results and currently trades at $6,270.
Read our full analysis of NVR’s results here.
Champion Homes (NYSE: SKY)
Founded in 1951, Champion Homes (NYSE: SKY) is a manufacturer of modular homes and buildings in North America.
Champion Homes reported revenues of $727 million, up 6.2% year on year. This number beat analysts’ expectations by 0.7%. It was a satisfactory quarter as it also logged a narrow beat of analysts’ EBITDA estimates.
The stock is up 5.5% since reporting and currently trades at $91.15.
Read our full, actionable report on Champion Homes here, it’s free.
Installed Building Products (NYSE: IBP)
Founded in 1977, Installed Building Products (NYSE: IBP) is a company specializing in the installation of insulation, waterproofing, and other complementary building products for residential and commercial construction.
Installed Building Products reported revenues of $808.4 million, up 3.9% year on year. This print surpassed analysts’ expectations by 2.4%. Taking a step back, it was a mixed quarter as it recorded a significant miss of analysts’ EPS estimates.
The stock is down 6.3% since reporting and currently trades at $220.50.
Read our full, actionable report on Installed Building Products here, it’s free.
Market update
Over the past year, investors have been forced to repeatedly answer the same question: what is the market’s biggest risk? The answer has changed several times, and each shift has reshaped market leadership.
Late in 2025 and early 2026, artificial intelligence became the market’s primary uncertainty. Investors questioned whether AI would erode software pricing power and weaken competitive moats as AI made it easier to replicate once-differentiated products.
By the spring, technology took a back seat to geopolitics. The U.S. conflict with Iran briefly became the market’s dominant narrative, raising concerns about oil prices, inflation, and global growth. But as energy markets remained orderly and fears of a prolonged supply disruption faded, investors quickly turned their focus back to fundamentals.
Want to invest in winners with rock-solid fundamentals? Check out our Top 6 Stocks and add them to your watchlist. These companies are poised for growth regardless of the political or macroeconomic climate.