Non-lethal weapons company Byrna (NASDAQ: BYRN) missed Wall Street’s revenue expectations in Q3 2026, with sales falling 45.7% year on year to $15.3 million. Its GAAP loss of $0.13 per share was 17% above analysts’ consensus estimates.
Is now the time to buy Byrna? Find out by accessing our full research report, it’s free.
Byrna (BYRN) Q3 2026 Highlights:
- Revenue: $15.3 million vs analyst estimates of $16.15 million (45.7% year-on-year decline, 5.3% miss)
- EPS (GAAP): -$0.13 vs analyst estimates of -$0.16 (17% beat)
- Adjusted EBITDA: -$1.36 million (-8.9% margin, 137% year-on-year decline)
- Adjusted EBITDA Margin: -8.9%, down from 13.2% in the same quarter last year
- Market Capitalization: $92.33 million
Management Commentary“Over the past several months, we have made significant progress in rebuilding the foundations necessary to support sustainable long-term growth,” said Byrna CEO Conn Davis. “Our results in the quarter reflect our ongoing transition, but we are now starting to see positive signs of new initiatives taking hold and expect to improve sequentially as we approach the end of our fiscal year. For example, we averaged over 29,000 website sessions per day in August, the highest since March of this year. Website conversion also improved from June to August sequentially. Both of these metrics reflect the work we’ve done increasing engagement across our digital channels, onboarding creators to our social engagement program, and launching new media partnerships. While these efforts remain in their early stages, the initial indicators are encouraging and give us confidence that we are moving in the right direction.
Company Overview
Providing civilians with tools to disable, disarm, and deter would-be assailants, Byrna (NASDAQ: BYRN) is a provider of non-lethal weapons.
Revenue Growth
A company’s long-term performance is an indicator of its overall quality. Any business can put up a good quarter or two, but many enduring ones grow for years. Thankfully, Byrna’s 18% annualized revenue growth over the last five years was incredible. Its growth surpassed the average industrials company and shows its offerings resonate with customers, a great starting point for our analysis.
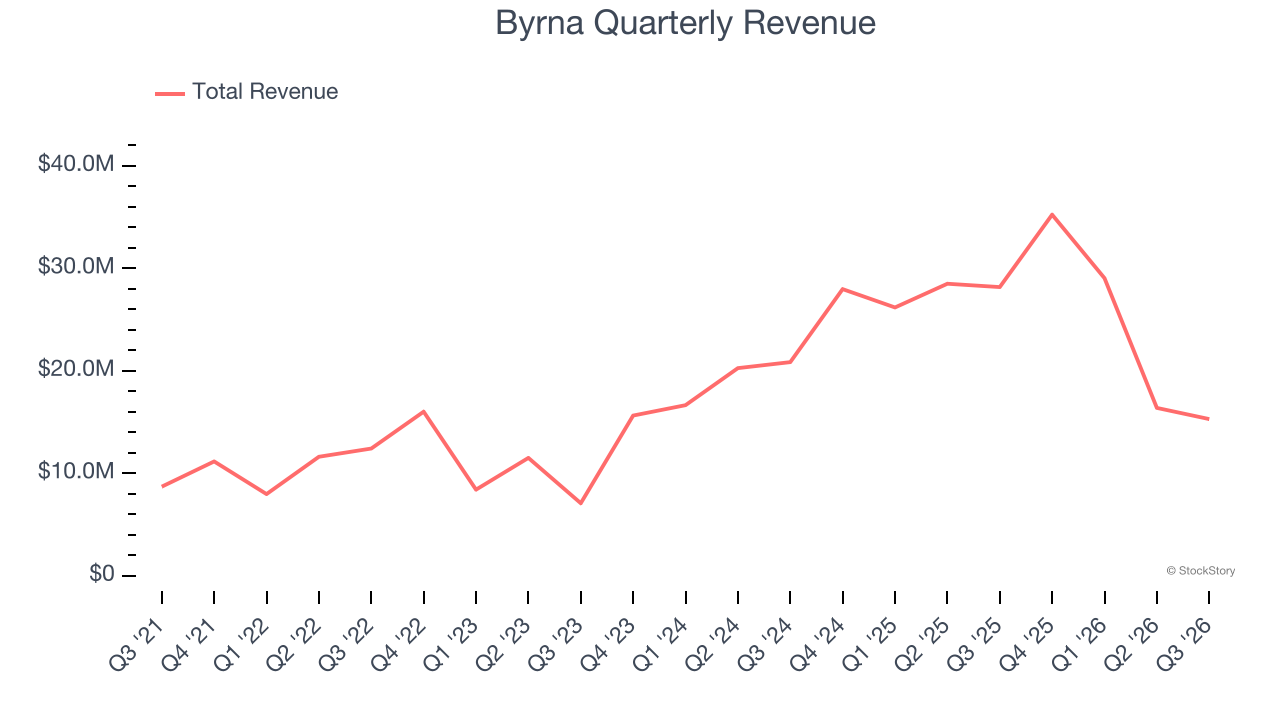
Long-term growth is the most important, but within industrials, a half-decade historical view may miss new industry trends or demand cycles. Byrna’s annualized revenue growth of 14.3% over the last two years is below its five-year trend, but we still think the results suggest healthy demand. 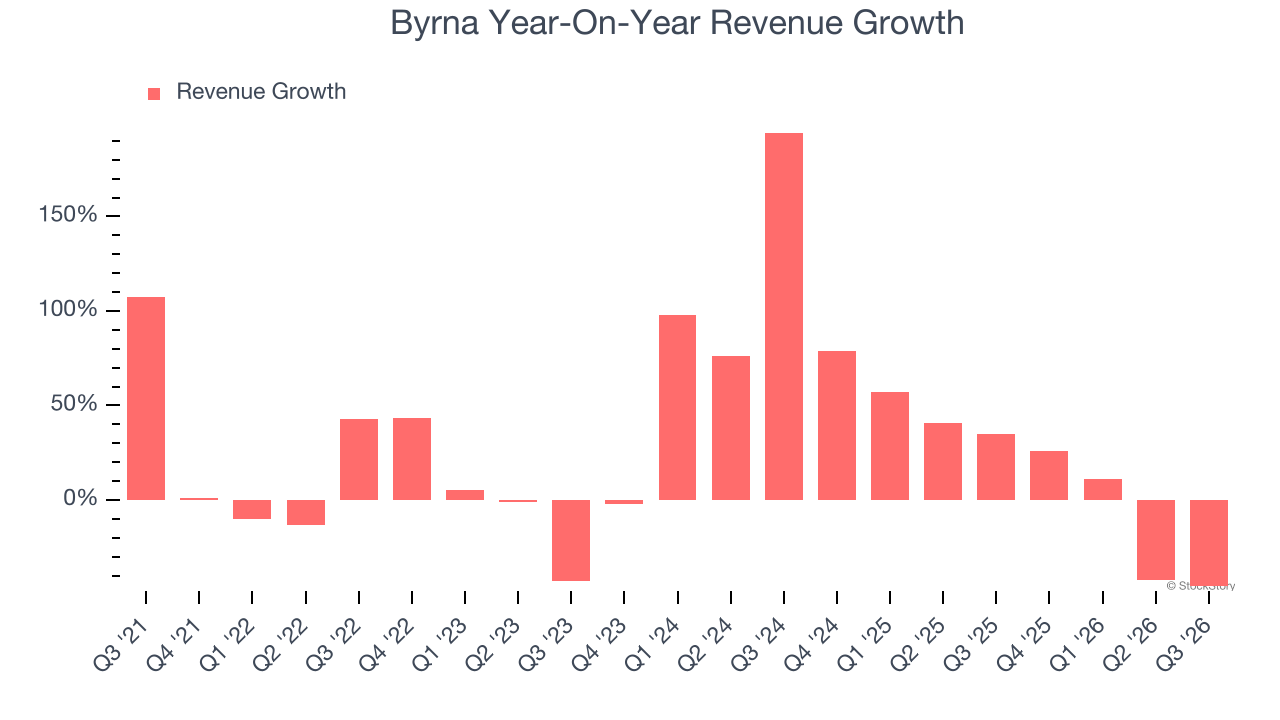
This quarter, Byrna missed Wall Street’s estimates and reported a rather uninspiring 45.7% year-on-year revenue decline, generating $15.3 million of revenue.
Looking ahead, sell-side analysts expect revenue to decline by 5.2% over the next 12 months, a deceleration versus the last two years. This projection is underwhelming and suggests its products and services will face some demand challenges. At least the company is tracking well in other measures of financial health.
WHILE YOU’RE HERE: The Next Palantir? One satellite company captures images of every point on Earth. Every single day. The Pentagon wants it. Hedge funds are using it to beat earnings. You’ve probably never heard of it.
This is what the early days of Palantir looked like before it became a giant. Same playbook. Different technology. If you missed Palantir, you need to see this. Claim The Stock Ticker for Free HERE.
Operating Margin
Byrna’s high expenses have contributed to an average operating margin of negative 4.1% over the last five years. Unprofitable industrials companies require extra attention because they could get caught swimming naked when the tide goes out.
On the plus side, Byrna’s operating margin rose by 13 percentage points over the last five years, as its sales growth gave it operating leverage. Still, it will take much more for the company to reach long-term profitability.
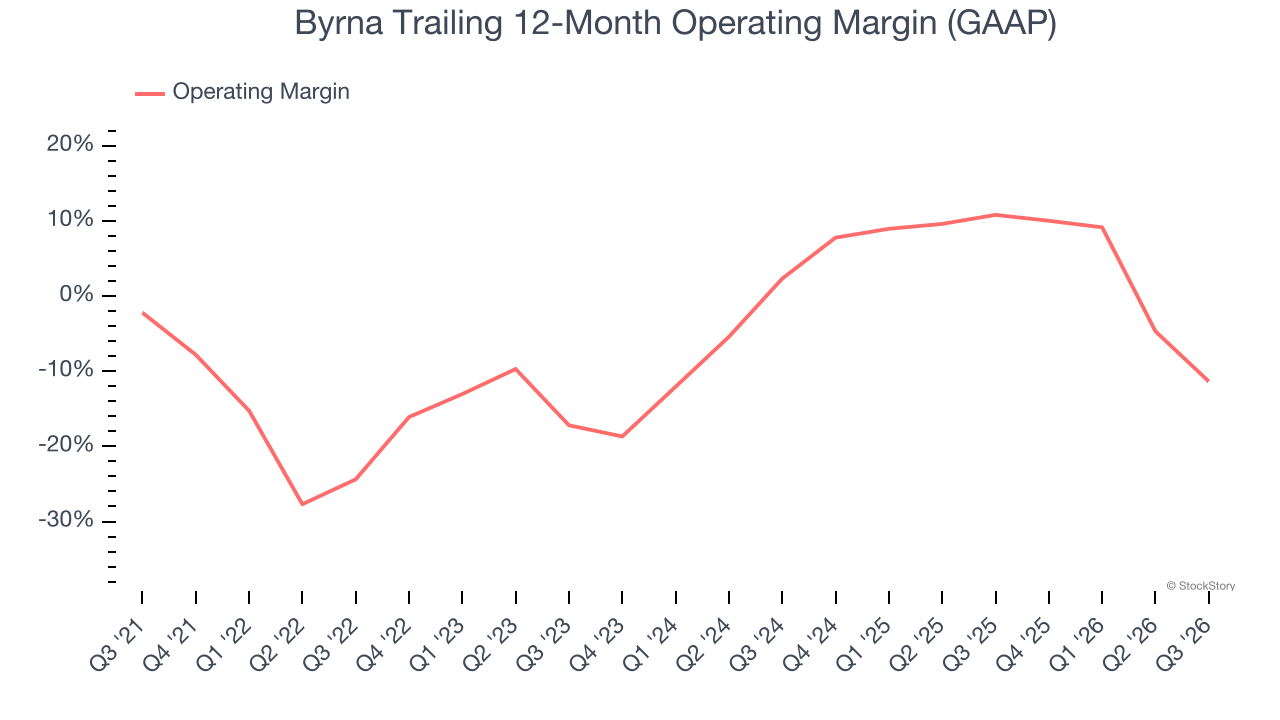
Byrna’s operating margin was negative 19.2% this quarter.
Earnings Per Share
Revenue trends explain a company’s historical growth, but the long-term change in earnings per share (EPS) points to the profitability of that growth — for example, a company could inflate its sales through excessive spending on advertising and promotions.
Byrna’s earnings losses deepened over the last five years as its EPS dropped 25.2% annually. We’ll keep a close eye on the company as diminishing earnings could imply changing secular trends and preferences.
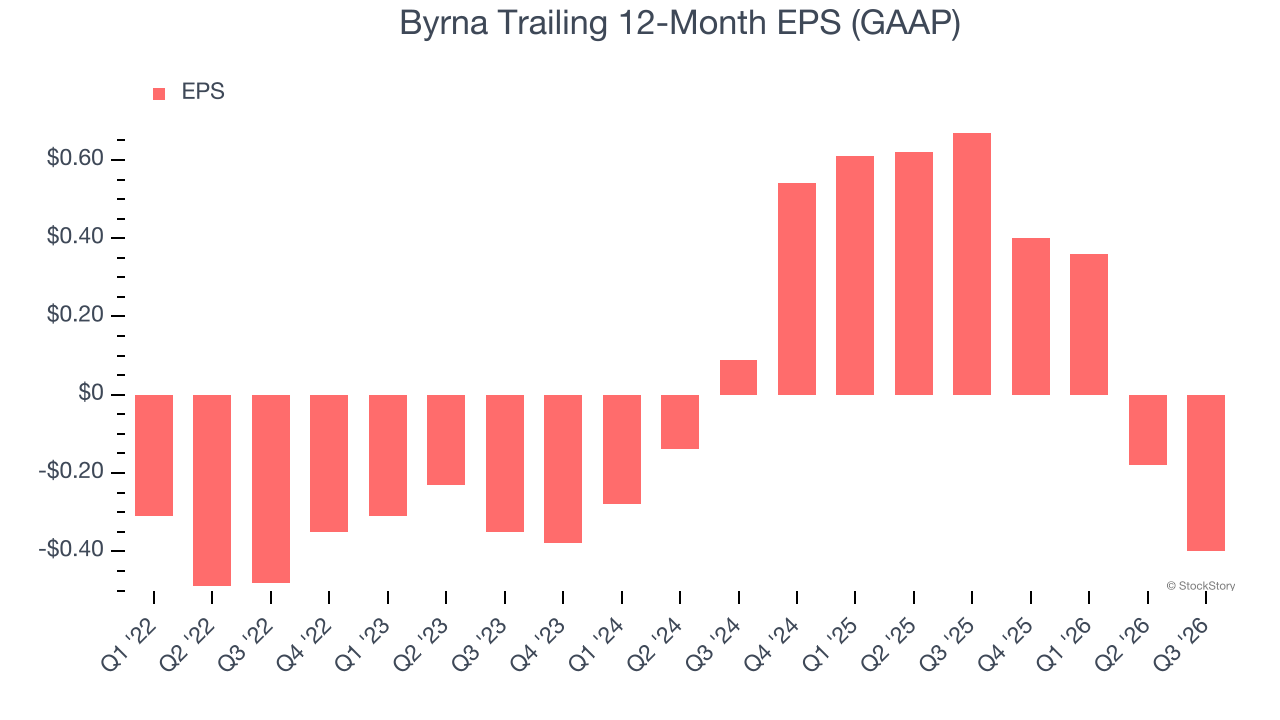
Like with revenue, we analyze EPS over a more recent period because it can provide insight into an emerging theme or development for the business.
Sadly for Byrna, its EPS declined by 154% annually over the last two years while its revenue grew by 14.3%. This tells us the company became less profitable on a per-share basis as it expanded.
We can take a deeper look into Byrna’s earnings to better understand the drivers of its performance. Byrna’s operating margin has declined over the last two years. This was the most relevant factor (aside from the revenue impact) behind its lower earnings; interest expenses and taxes can also affect EPS but don’t tell us as much about a company’s fundamentals.
In Q3, Byrna reported EPS of negative $0.13, down from $0.09 in the same quarter last year. Despite falling year on year, this print easily cleared analysts’ estimates. Over the next 12 months, Wall Street expects Byrna to improve its earnings losses. Analysts forecast its full-year EPS will improve from negative $0.40 to negative $0.24.
Key Takeaways from Byrna’s Q3 Results
We were impressed by how significantly Byrna blew past analysts’ EBITDA expectations this quarter. We were also glad its EPS outperformed Wall Street’s estimates. On the other hand, its revenue missed. Overall, this print had some key positives. Investors were likely hoping for more, and shares traded down 5.3% to $3.84 immediately after reporting.
Big picture, is Byrna a buy here and now? What happened in the latest quarter matters, but not as much as longer-term business quality and valuation, when deciding whether to invest in this stock. We cover that in our actionable full research report which you can read here (it’s free).