What a brutal six months it’s been for Flowers Foods. The stock has dropped 32.4% and now trades at $5.58, rattling many shareholders. This was partly due to its softer quarterly results and might have investors contemplating their next move.
Is there a buying opportunity in Flowers Foods, or does it present a risk to your portfolio? Get the full stock story straight from our expert analysts, it’s free.
Why Do We Think Flowers Foods Will Underperform?
Even with the cheaper entry price, we’re cautious about Flowers Foods. Here are three reasons you should be careful with FLO, plus one stock we’d rather own.
1. Demand Slipping as Sales Volumes Decline
Revenue growth can be broken down into changes in price and volume (the number of units sold). While both are important, volume is the lifeblood of a successful staples business as there’s a ceiling to what consumers will pay for everyday goods; they can always trade down to non-branded products if the branded versions are too expensive.
Flowers Foods’s average quarterly sales volumes have shrunk by 2.7% over the last two years. This decrease isn’t ideal because the quantity demanded for consumer staples products is typically stable. 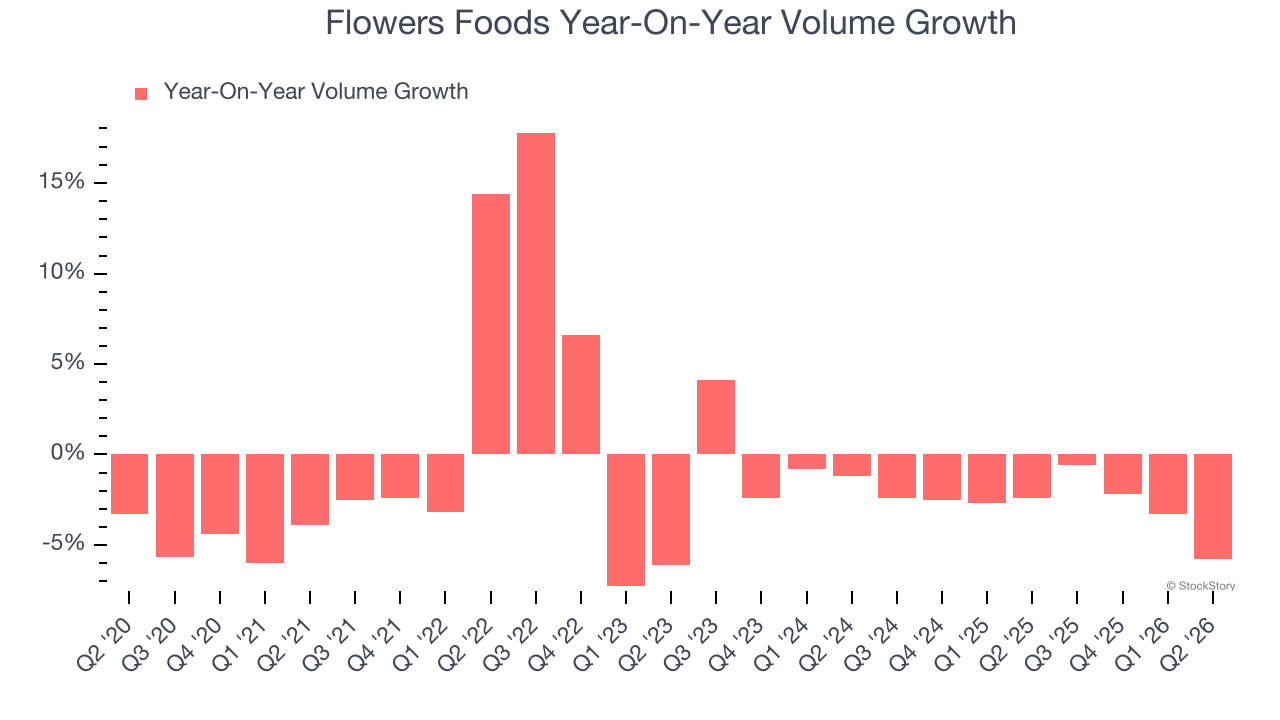
2. Revenue Projections Show Stormy Skies Ahead
Forecasted revenues by Wall Street analysts signal a company’s potential. Predictions may not always be accurate, but accelerating growth typically boosts valuation multiples and stock prices while slowing growth does the opposite.
Over the next 12 months, sell-side analysts expect Flowers Foods’s revenue to drop by 3.1%, a decrease from its 1.4% annualized growth for the past three years. This projection doesn’t excite us and implies its products will face some demand challenges.
3. EPS Trending Down
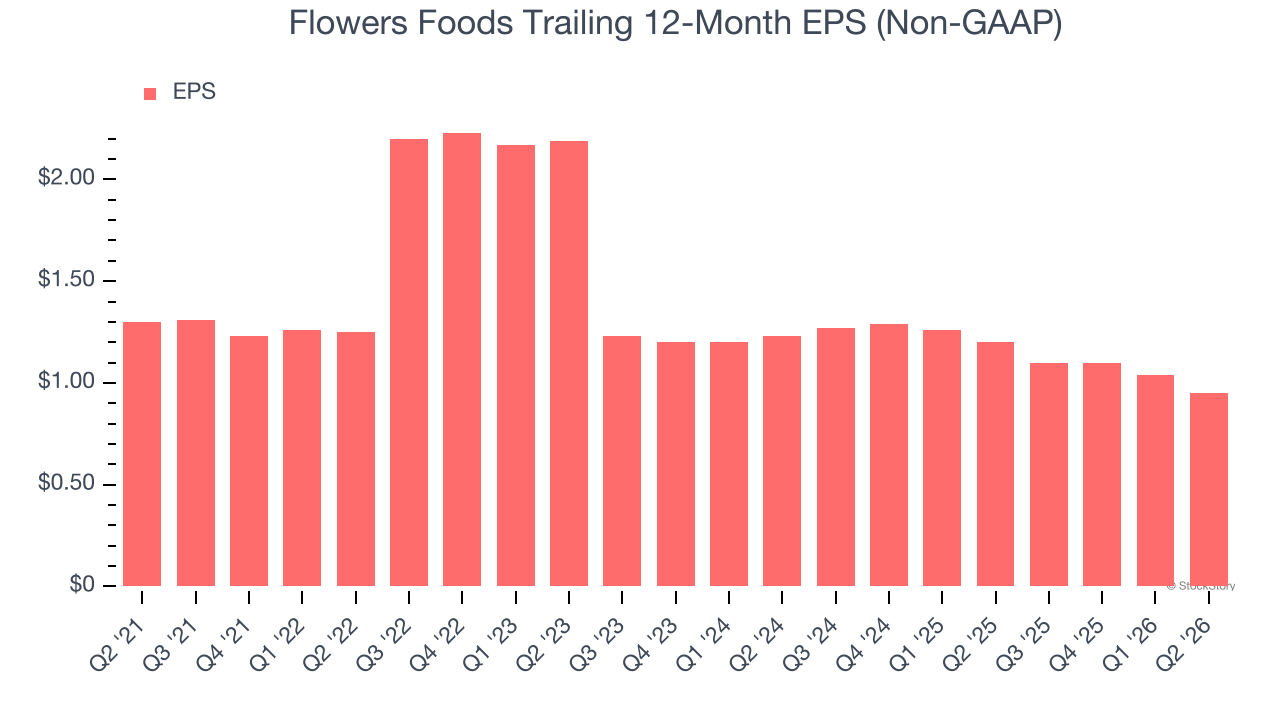
Analyzing the long-term change in earnings per share (EPS) shows whether a company’s incremental sales were profitable — for example, revenue could be inflated through excessive spending on advertising and promotions.
Sadly for Flowers Foods, its EPS declined by 24.3% annually over the last three years while its revenue grew by 1.4%. This tells us the company became less profitable on a per-share basis as it expanded.
Final Judgment
We see the value of companies helping consumers, but in the case of Flowers Foods, we’re out. After the recent drawdown, the stock trades at 8× forward P/E (or $5.58 per share). While this valuation is optically cheap, the potential downside is huge given its shaky fundamentals. There are better investments elsewhere. We’d suggest looking at a top digital advertising platform riding the creator economy.
High-Quality Stocks for All Market Conditions
WHILE YOU’RE HERE: Top 9 Market-Beating Stocks. The best stocks don’t just beat the market once. They do it again. And again. Robust revenue growth, rising free cash flow, returns on capital that leave their competition in the dust. The market has already rewarded these businesses.
But our AI platform says the party isn’t over. Find out which 9 stocks made the cut this week — FREE. Get Our Top 9 Market-Beating Stocks for Free HERE.
Stocks that have made our list include now familiar names such as Nvidia (+1,460% between June 2020 and June 2025) as well as under-the-radar businesses like the once-micro-cap company Kadant (+214% between June 2020 and June 2025). Find your next big winner with StockStory today.