Vocational education company Covista (NYSE: CVSA) reported calendar Q3 2026 (fiscal Q1 2027) results beating Wall Street’s revenue expectations, with revenue up 10.7% year on year to $511.5 million. The company expects the full year’s revenue to be around $2.08 billion, close to analysts’ consensus estimates. Its non-GAAP profit of $2.19 per share was 19.5% above analysts’ consensus estimates.
For more on Covista, read the full research report for free.
Covista (CVSA) Q3 CY2026 highlights:
- Revenue $511.5 million vs S&P analysts’ consensus estimates of $489.4 million (10.7% year-on-year growth, 4.5% beat)
- Adjusted EPS $2.19 vs S&P analysts’ consensus estimates of $1.83 (19.5% beat)
- Adjusted EBITDA $131.2 million vs analysts’ consensus estimates of $118.8 million (25.6% margin, 10.5% beat)
- Revenue guidance The company slightly lifted its revenue guidance for the full year to $2.08 billion at the midpoint from $2.07 billion
- Adjusted EPS guidance Management slightly raised its full-year adjusted EPS guidance to $9.10 at the midpoint
- Operating margin 19.2%, in line with the same quarter last year
- Free cash flow margin 14.9%, down from 24.8% in the same quarter last year
- Market capitalization $4.31 billion
“Purpose at Scale is delivering and all four pillars of the strategy are contributing to our momentum. Total enrollment grew for the 13th consecutive quarter, powering our double-digit revenue growth and continued margin expansion. On that strength, we are raising our fiscal 2027 guidance,” said Steve Beard, Chairman and Chief Executive Officer, Covista. “The demand behind our strategy is durable, and Covista is critical infrastructure for American healthcare. We serve an urgent need in the communities where care matters most, and by doing that well, we are strategically positioned to create lasting value for our shareholders.”
Revenue growth
Reviewing a company’s long-term revenue performance reveals insights into its quality. Any business can have short-term success, but a top-tier one grows for years. Over the last five years, Covista grew its revenue at a 15.4% compounded annual growth rate. Though this growth is acceptable on an absolute basis, revenue growth alone is not enough in the consumer discretionary sector, which can display significant earnings volatility. The bar for the sector is particularly high, reflecting the non-essential and hit-driven nature of the products and services offered. Additionally, the five-year CAGR starts around Covid, when revenue was depressed before rebounding.
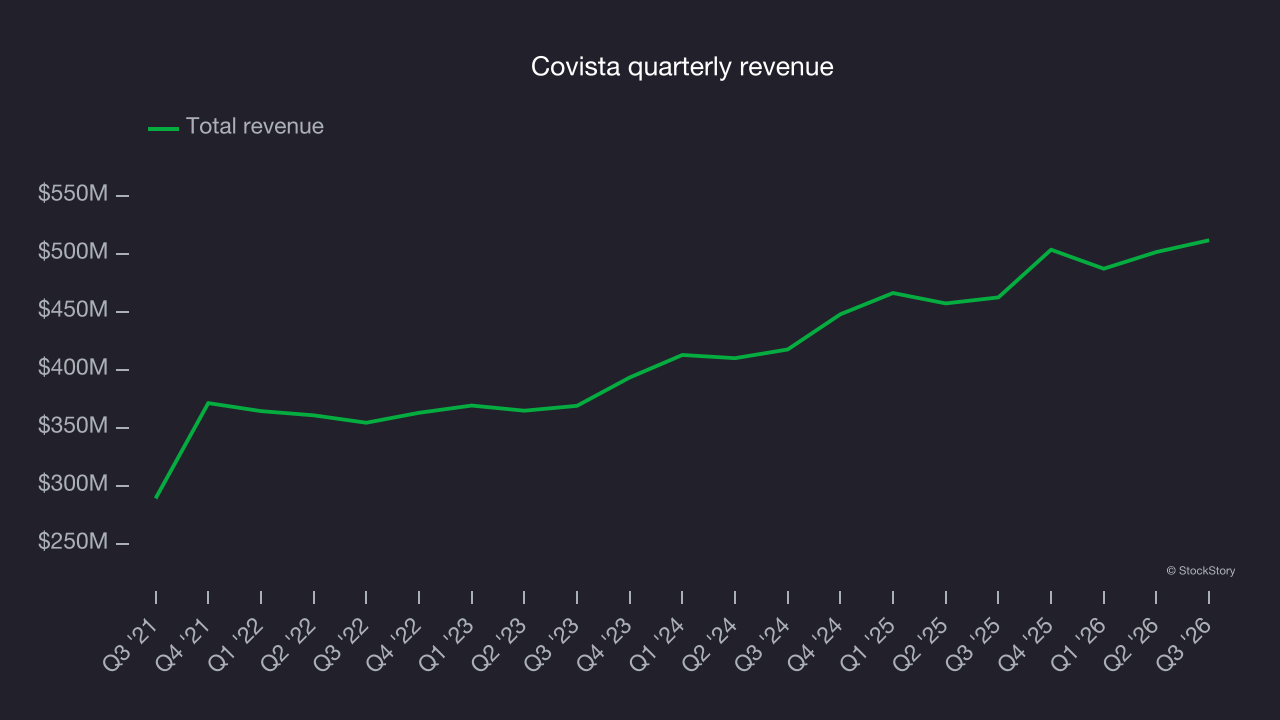
Long-term growth matters most, but within consumer discretionary, a longer historical view may miss a company benefiting from a successful new product or trend. Covista’s recent performance shows its demand has slowed as its annualized revenue growth of 10.8% over the last two years was below its five-year trend. Decelerating revenue growth in the sector warrants caution, as it could signal changing consumer tastes aided by low switching costs. 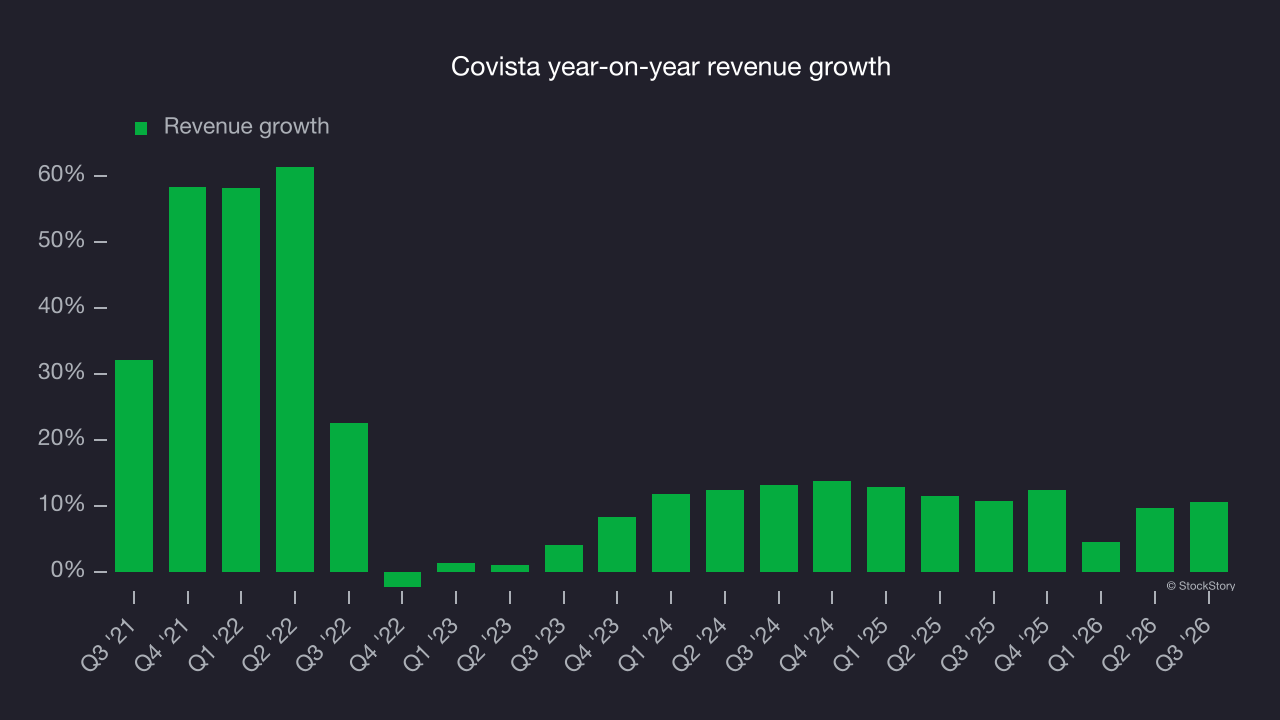
This quarter, Covista reported year-on-year revenue growth of 10.7%, and its $511.5 million of revenue exceeded Wall Street’s consensus estimates by 4.5%.
Looking ahead, sell-side analysts expect revenue to grow 5.3% over the next 12 months, according to S&P, a deceleration versus the last two years. This projection is underwhelming and indicates its products and services will see some demand headwinds.
Operating margin
Operating margin is an important measure of profitability as it shows the portion of revenue left after accounting for all core expenses, from the cost of goods sold to advertising and wages. It’s also useful for comparing profitability across companies with different levels of debt and tax rates because it excludes interest and taxes.
Covista’s operating margin has more or less stayed the same over the last 12 months, but margin increases driven by economies of scale and cost efficiency are generally preferable over time.
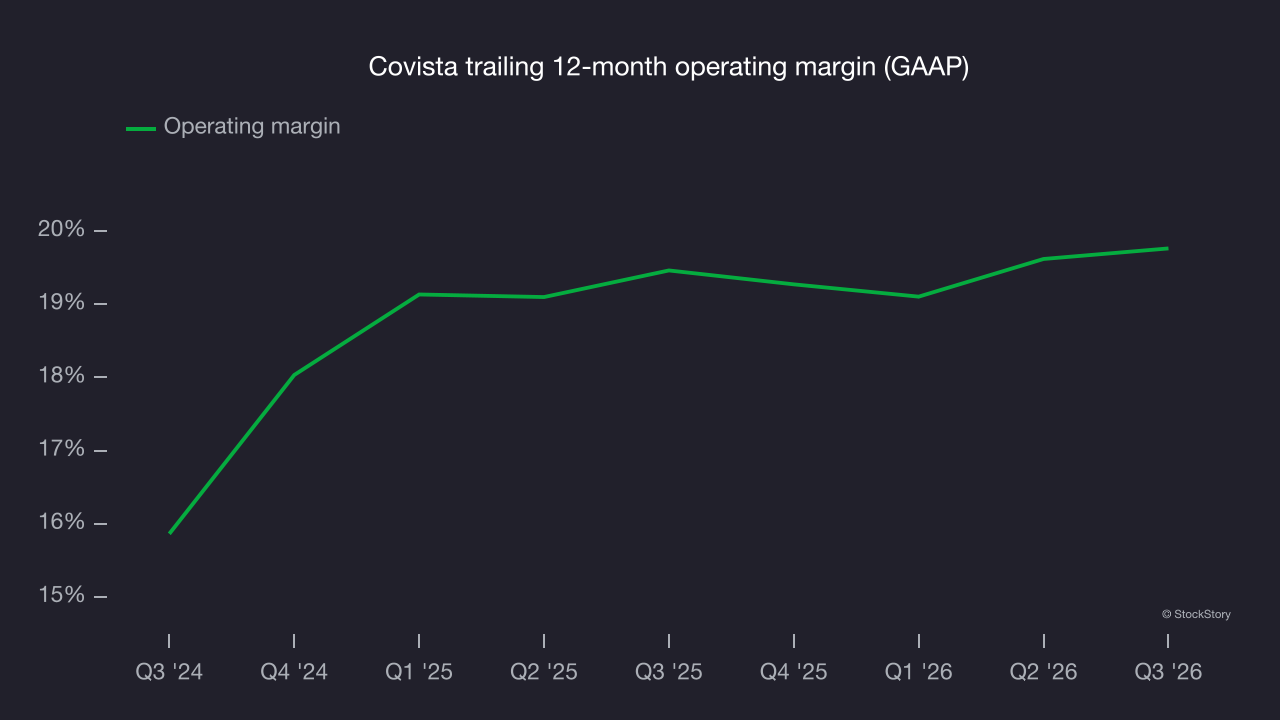
This quarter, Covista generated an operating margin of 19.2%, in line with the same quarter last year. This indicates the company’s overall cost structure has been relatively stable.
Earnings per share
We track the long-term change in earnings per share (EPS) for the same reason as long-term revenue growth. Compared to revenue, however, EPS highlights whether a company’s growth is profitable.
Covista’s EPS grew at a 25.3% compounded annual growth rate over the last five years. On the positive side, this performance outpaced its 15.4% annualized revenue growth, indicating the company became more profitable on a per-share basis as it expanded.
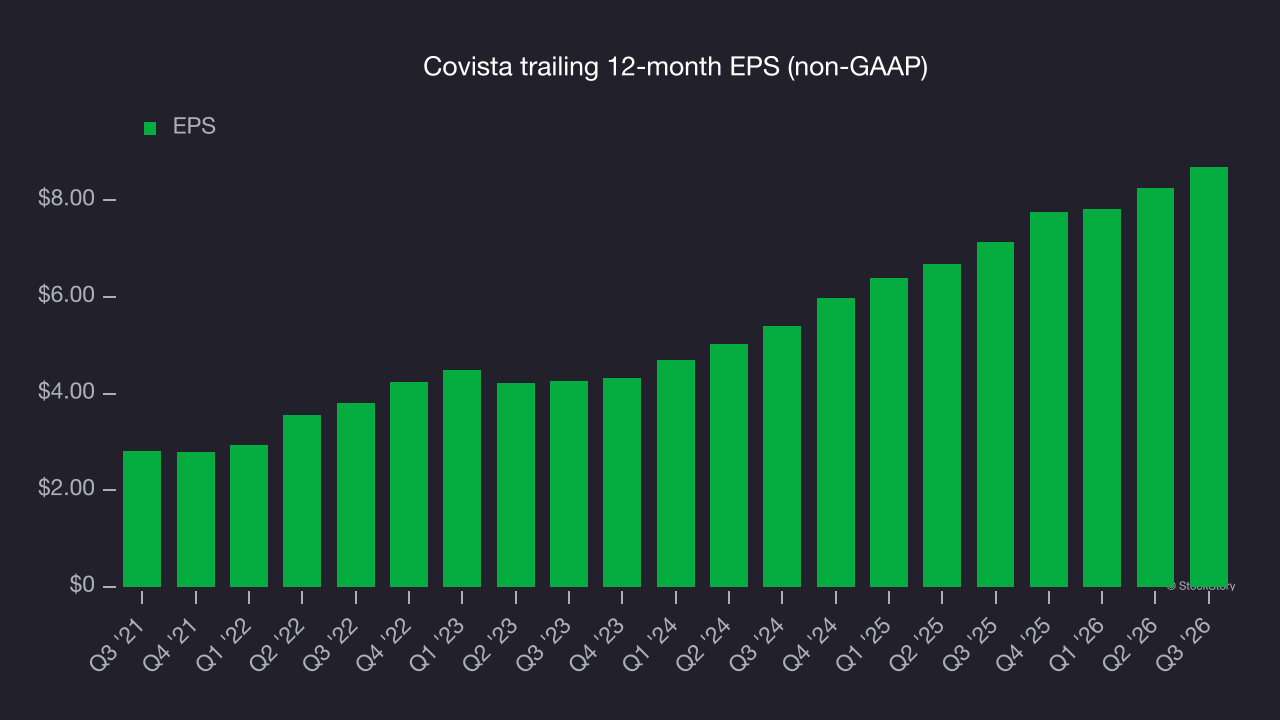
In Q3, Covista reported adjusted EPS of $2.19, up from $1.75 in the same quarter last year. This result easily beat analysts’ consensus estimates. Over the next 12 months, Wall Street expects Covista’s full-year EPS to grow 6.8% from $8.69 to $9.29, according to S&P.
Key takeaways from Covista’s Q3 results
Covista delivered a solid quarter, topping analysts’ consensus estimates for both EPS and revenue. Shares edged higher 1.2% to $130.26 immediately after the results.
Covista reported solid earnings, but one quarter doesn’t necessarily make the stock a buy. When making that decision, it’s important to consider its valuation and business quality as well as the latest quarterly results. For more on Covista, read our full research report here (it’s free).