Alternative asset manager Ares Management (NYSE: ARES) beat Wall Street’s revenue expectations in Q3 2026, with revenue rising 26.1% year on year to $1.43 billion. Its GAAP profit of $0.21 per share was 83.2% below analysts’ consensus estimates.
For more on Ares, read our free full research report.
Ares (ARES) Q3 2026 highlights:
- Assets under management $690.6 billion vs analysts’ consensus estimates of $694.6 billion (15.9% year-on-year growth, 0.6% miss)
- Revenue $1.43 billion vs S&P analysts’ consensus estimates of $1.23 billion (26.1% year-on-year growth, 16.2% beat)
- Fee-related earnings $524.2 million vs analysts’ consensus estimates of $523.6 million (in line)
- EPS (GAAP) $0.21 vs analysts’ consensus estimates of $1.25 (83.2% miss partly due to net realized and unrealized losses on investments)
- Market capitalization $28.16 billion
Revenue growth
Reviewing a company’s long-term revenue performance reveals insights into its quality. Even a poor business can perform well for one or two quarters, but a high-quality one grows for years. Over the last five years, Ares grew its revenue at a strong 22.3% compounded annual growth rate. Its growth surpassed the average financials company and shows its offerings resonate with customers.
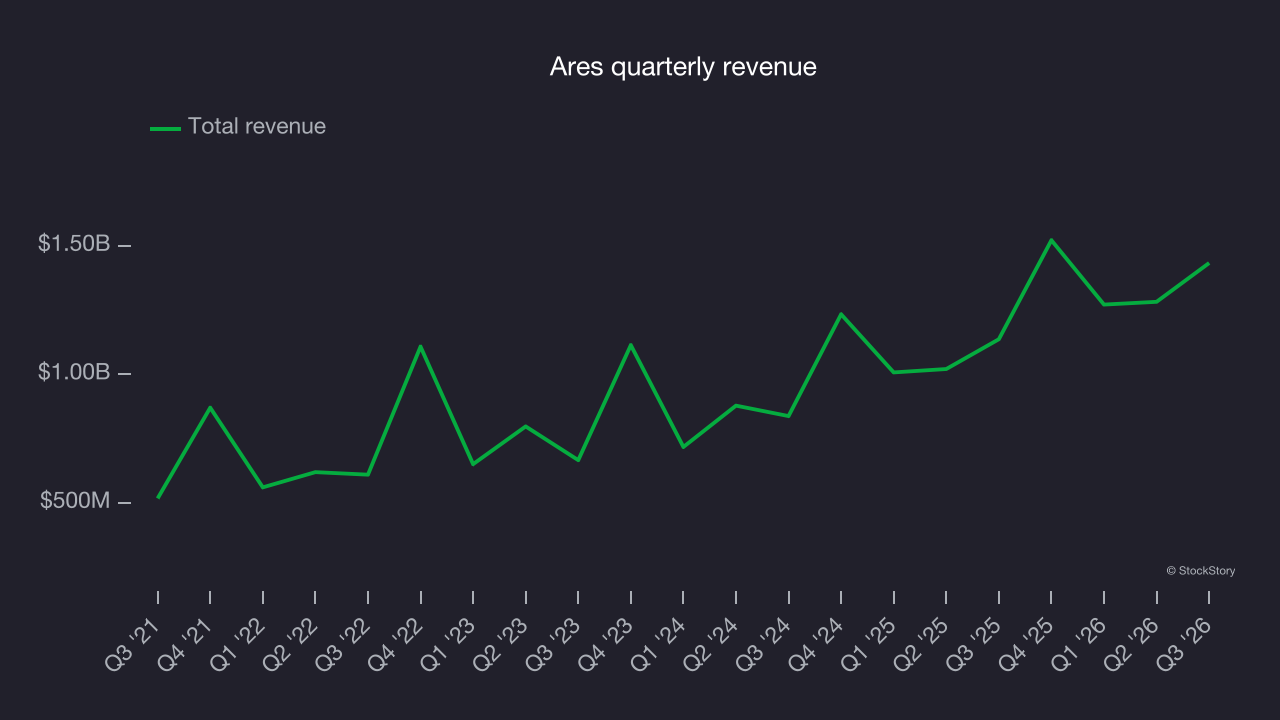
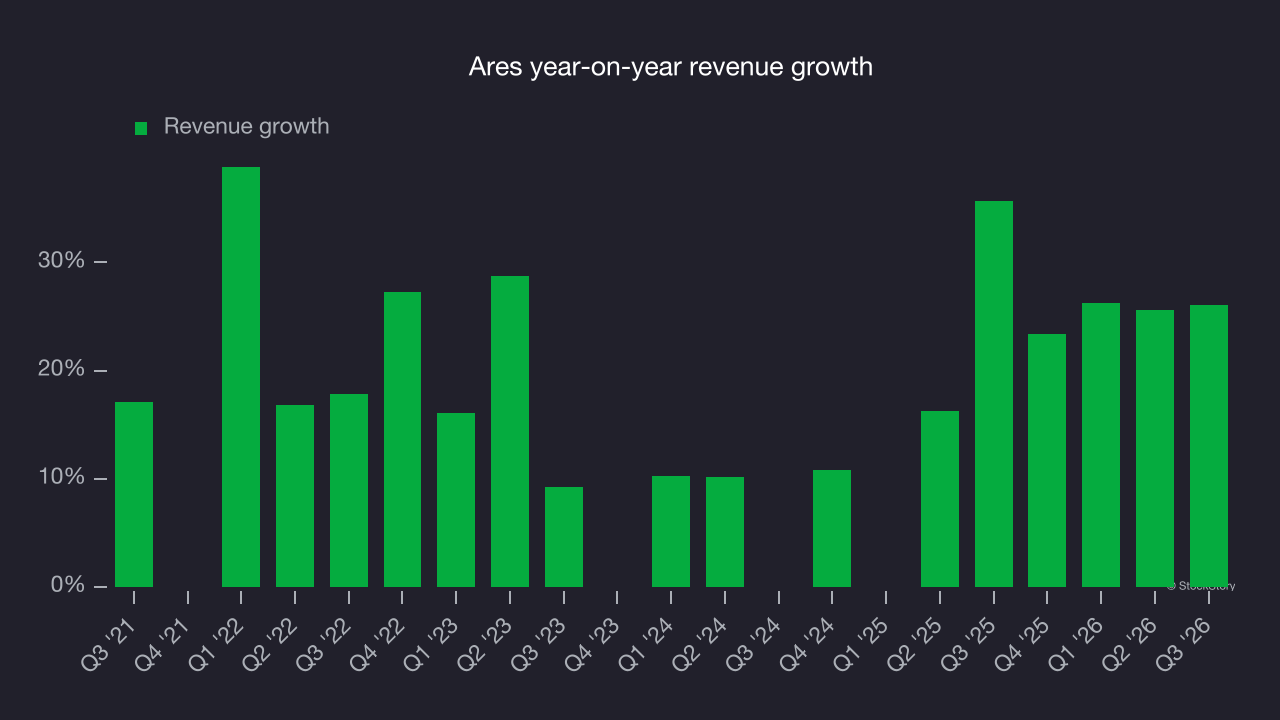
This quarter, Ares reported year-on-year revenue growth of 26.1%, and its $1.43 billion in revenue topped Wall Street’s consensus estimates by 16.2%.
Assets under management (AUM)
Assets Under Management (AUM) encompasses all client funds under a firm’s investment management umbrella. The recurring fee structure on these assets provides consistent revenue generation, offering financial stability even during periods of poor investment returns, though sustained underperformance can impact future asset flows.
Ares’s AUM has grown at an annual rate of 23.5% over the last five years, well above the broader financials industry and faster than its total revenue. Over the last two years, Ares’s AUM growth decelerated to 22.3% annually. Fundraising or short-term investment performance was a net detractor to the company over this shorter period since assets grew more slowly than total revenue. Still, asset growth carries less weight given how lumpy and cyclical it can be.
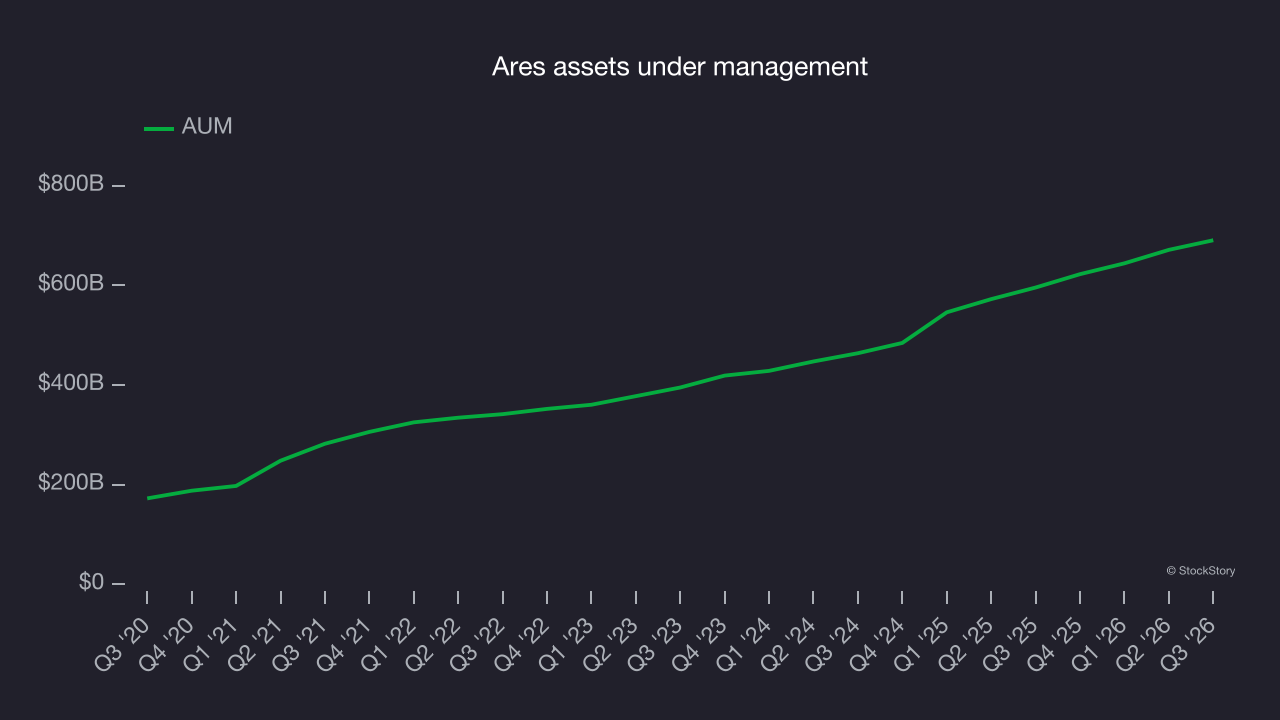
In Q3, Ares’s AUM was $690.6 billion, falling 0.6% short of analysts’ consensus estimates. This figure was 15.9% higher than the same quarter last year.
Key takeaways from Ares’s Q3 results
Ares’s sizable revenue beat was a highlight of Q3, but EPS missed consensus estimates and AUM came in slightly below Wall Street’s consensus, making for a mixed quarter. Shares edged higher 1.1% to $125.26 immediately after the results.
When evaluating Ares at its current price, consider the bigger picture of valuation and business quality as well as the latest earnings. Read the full research report here (it’s free).