U.S. Physical Therapy has had an impressive run over the past six months as its shares have beaten the S&P 500 by 14.2%. The stock now trades at $88.57, marking a 21% gain. This performance may have investors wondering how to approach the situation.
Is there a buying opportunity in U.S. Physical Therapy, or does it present a risk to your portfolio? Get the full stock story straight from our expert analysts, it’s free.
Why is U.S. Physical Therapy not exciting?
We’re glad investors have benefited from the price increase, but we’re sitting this one out for now. Here are three reasons why USPH doesn’t excite us, plus one stock we’d rather own.
1. Fewer distribution channels limit its ceiling
Larger companies benefit from economies of scale, where fixed costs like infrastructure, technology, and administration are spread over a higher volume of goods or services, reducing the cost per unit. Scale can also lead to bargaining power with suppliers, greater brand recognition, and more investment firepower. A virtuous cycle can ensue if a scaled company plays its cards right.
With just $812.2 million in revenue over the past 12 months, U.S. Physical Therapy is a small company in an industry where scale matters. This makes it difficult to build trust with customers because healthcare is heavily regulated, complex, and resource-intensive.
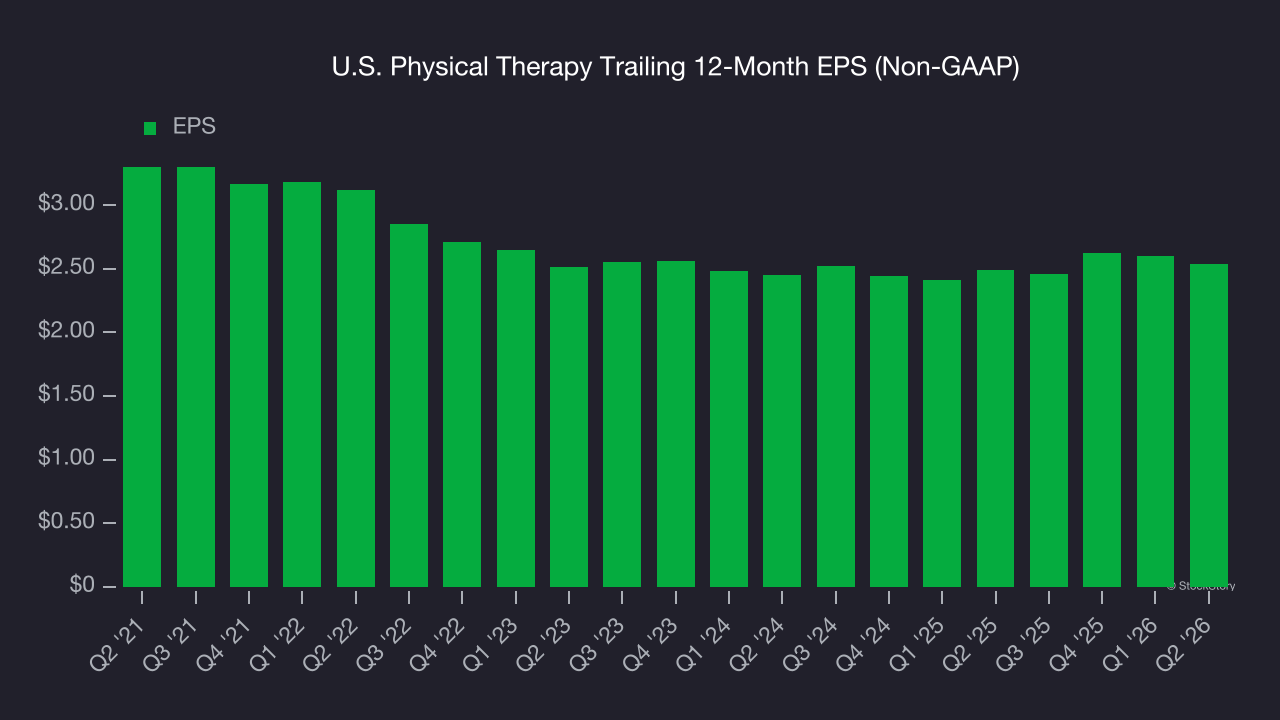
2. EPS trending down
We track the long-term change in earnings per share (EPS) because it highlights whether a company’s growth is profitable.
Sadly for U.S. Physical Therapy, its EPS declined by 5.1% annually over the last five years while its revenue grew by 11.8%. This tells us the company became less profitable on a per-share basis as it expanded.
3. New investments fail to bear fruit as ROIC declines
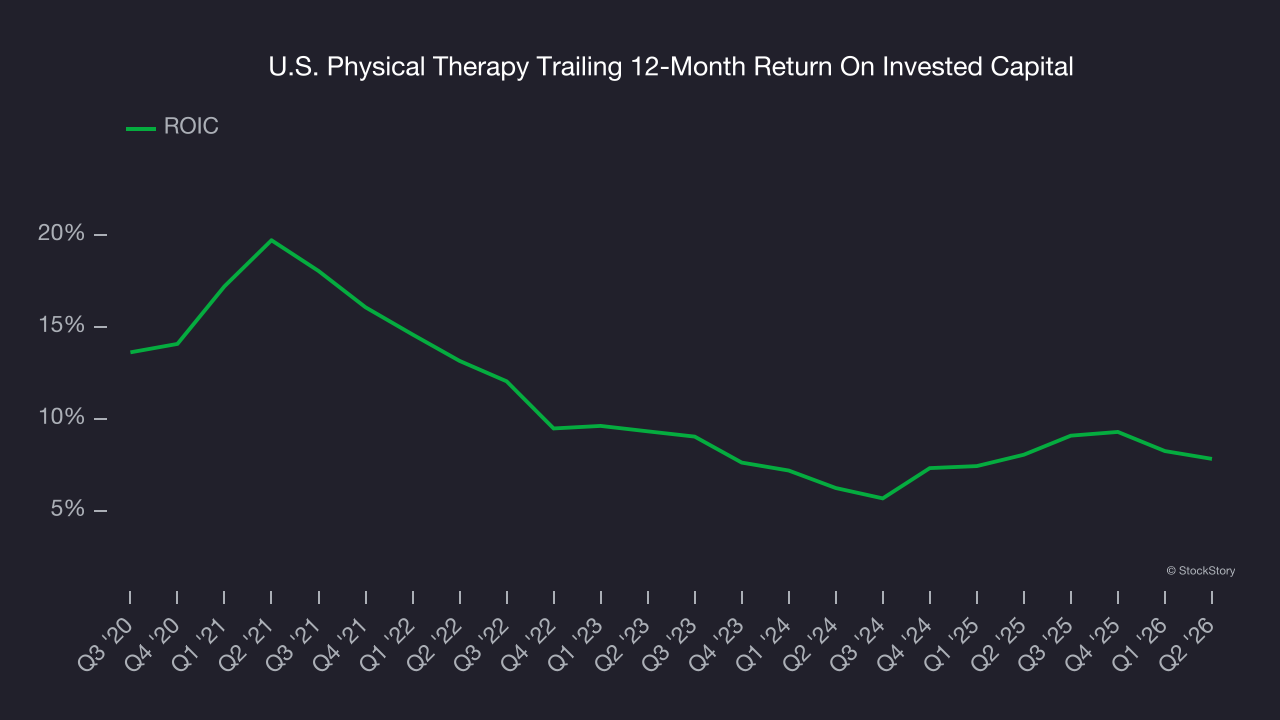
A company’s ROIC, or return on invested capital, shows how much operating profit it makes compared to the money it has raised (debt and equity).
Unfortunately, U.S. Physical Therapy’s ROIC averaged 3.3 percentage point decreases each year over the last few years. We like what management has done in the past, but its declining returns are perhaps a symptom of fewer profitable growth opportunities.
Final judgment
U.S. Physical Therapy isn’t a terrible business, but it doesn’t pass our quality test. With its shares beating the market recently, the stock trades at 29.3× forward P/E (or $88.57 per share). Investors with a higher risk tolerance might like the company, but we think the potential downside is too great. We’re pretty confident there are more exciting stocks to buy at the moment. We’d recommend looking at one of our top digital advertising picks.
High-quality stocks for all market conditions
WHILE YOU’RE HERE: Top 9 Market-Beating Stocks. The best stocks don’t just beat the market once. They do it again. And again. Robust revenue growth, rising free cash flow, returns on capital that leave their competition in the dust. The market has already rewarded these businesses.
But our AI platform says the party isn’t over. Find out which 9 stocks made the cut this week — FREE. Get Our Top 9 Market-Beating Stocks for Free HERE.
Stocks that have made our list include now familiar names such as Nvidia (+1,460% between June 2020 and June 2025) as well as under-the-radar businesses like the once-micro-cap company Tecnoglass (+1,552% between June 2020 and June 2025). Find your next big winner with StockStory today.