Over the past six months, Mettler-Toledo has been a great trade, beating the S&P 500 by 24.1%. Its stock price has climbed to $1,685, representing a healthy 33.3% increase. This was partly thanks to its solid quarterly results, and the performance may have investors wondering how to approach the situation.
Is now the time to buy Mettler-Toledo, or should you be careful about including it in your portfolio? Check out our in-depth research report to see what our analysts have to say, it’s free.
Why is Mettler-Toledo not exciting?
We’re happy investors have made money, but we’re sitting this one out for now. Here are three reasons why MTD doesn’t excite us, plus one stock we’d rather own.
1. Slow organic growth suggests waning demand in core business
Investors interested in research tools & consumables companies should track organic revenue in addition to reported revenue. This metric gives visibility into Mettler-Toledo’s core business because it excludes one-time events such as mergers, acquisitions, and divestitures along with foreign currency fluctuations - non-fundamental factors that can manipulate the income statement.
Over the last two years, Mettler-Toledo’s organic revenue averaged 3.7% year-on-year growth. This performance slightly lagged the sector and suggests it may need to improve its products, pricing, or go-to-market strategy, which can add an extra layer of complexity to its operations. 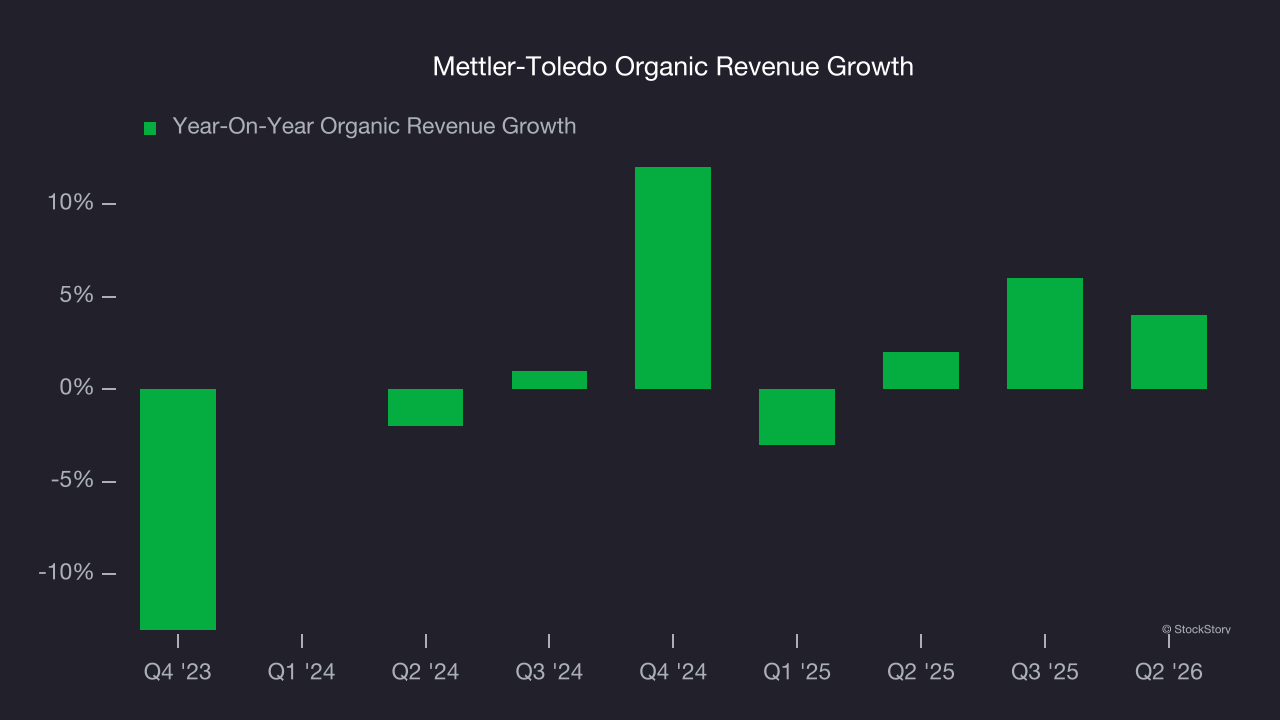
2. Projected revenue growth is slim
Forecasted revenues by Wall Street analysts signal a company’s potential. Predictions may not always be accurate, but accelerating growth typically boosts valuation multiples and stock prices while slowing growth does the opposite.
Over the next 12 months, sell-side analysts expect Mettler-Toledo’s revenue to rise by 4.9%, close to its 3.5% annualized growth for the past five years. This projection is underwhelming and implies its newer products and services will not accelerate its top-line performance yet.
3. New investments fail to bear fruit as ROIC declines
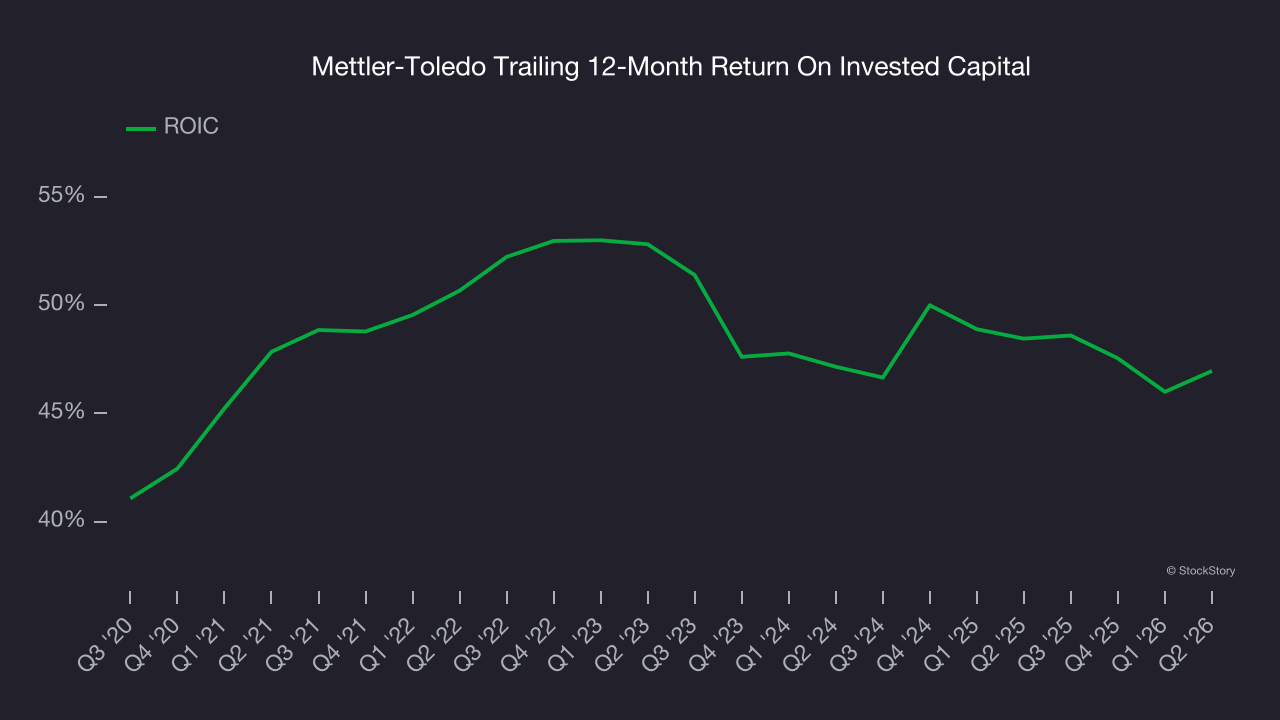
ROIC, or return on invested capital, is a metric showing how much operating profit a company generates relative to the money it has raised (debt and equity).
Unfortunately, Mettler-Toledo’s ROIC averaged 4 percentage point decreases each year over the last few years. We like what management has done in the past, but its declining returns are perhaps a symptom of fewer profitable growth opportunities.
Final judgment
Mettler-Toledo’s business quality ultimately falls short of our standards. With its shares beating the market recently, the stock trades at 34× forward P/E (or $1,685 per share). Beauty is in the eye of the beholder, but our analysis shows the upside isn’t great compared to the potential downside. We’re pretty confident there are more exciting stocks to buy at the moment. Let us point you toward one of our top software and edge computing picks.
Stocks we would buy instead of Mettler-Toledo
ALSO WORTH WATCHING: Top 5 Momentum Stocks. The best time to own a great stock is when the market is finally noticing it. These aren’t just high-quality businesses. Something is happening with them right now. Elite fundamentals meet near-term momentum — both boxes checked at the same time.
Find out which stocks our AI platform is flagging this week. See this week’s Strong Momentum stocks — FREE. Get Our Strong Momentum Stocks for Free HERE.
Stocks that have made our list include now familiar names such as Nvidia (+1,460% between June 2020 and June 2025) as well as under-the-radar businesses like the once-small-cap company Exlservice (+271% between June 2020 and June 2025). Find your next big winner with StockStory today.