Riley Exploration Permian has had an impressive run over the past six months as its shares have beaten the S&P 500 by 25.5%. The stock now trades at $48.32, marking a 33.6% gain. This was partly thanks to its solid quarterly results, and the run-up might have investors contemplating their next move.
Is now still a good time to buy REPX? Or are investors being too optimistic? Find out in our full research report, it’s free.
Why are we positive on Riley Exploration Permian?
Operating in counties where legacy oil fields have been producing since the early 1900s, Riley Exploration Permian (NYSE: REPX) drills for and produces oil and natural gas from horizontal wells in the Permian Basin of West Texas and New Mexico.
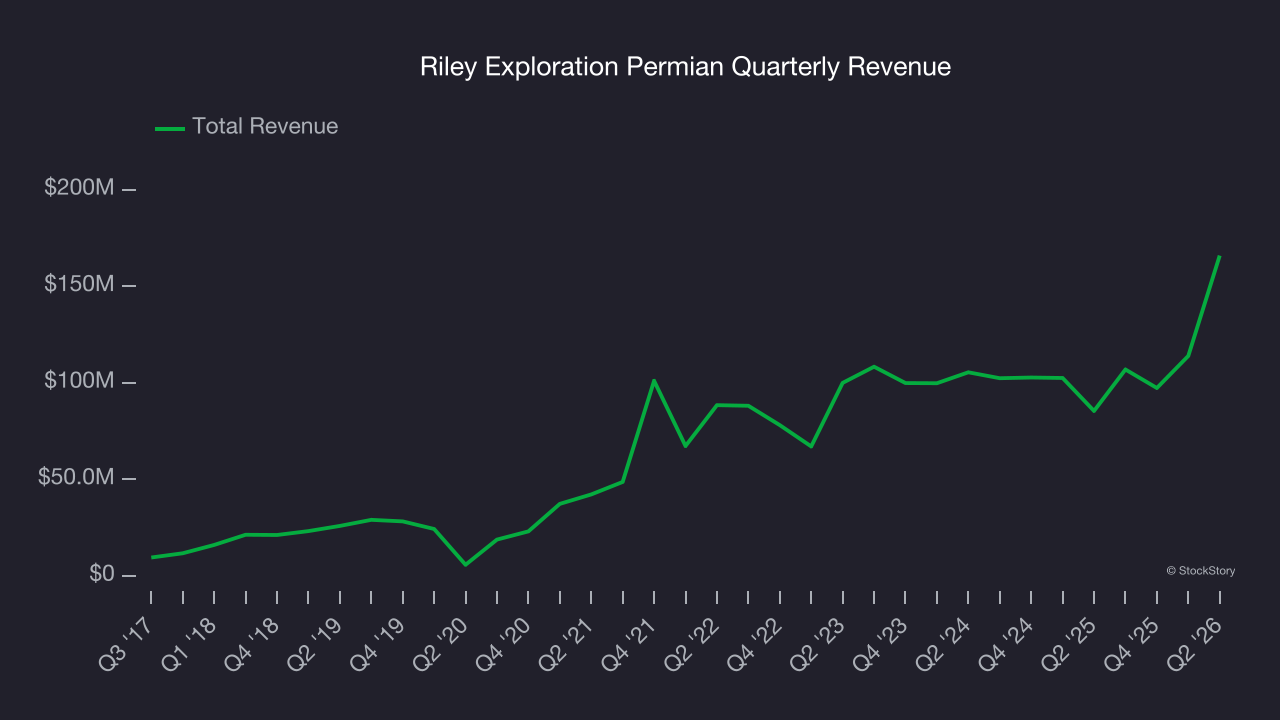
1. Skyrocketing revenue shows strong momentum
Cyclical sectors like Energy often flatter weaker operators during favorable price environments, but a longer-term lens separates those from businesses that can consistently perform across market cycles. Luckily, Riley Exploration Permian’s sales grew at an incredible 31.9% compounded annual growth rate over the last five years. Its growth beat the average energy upstream and integrated energy company and shows its offerings resonate with customers.
2. Elite gross margin powers best-in-class business model
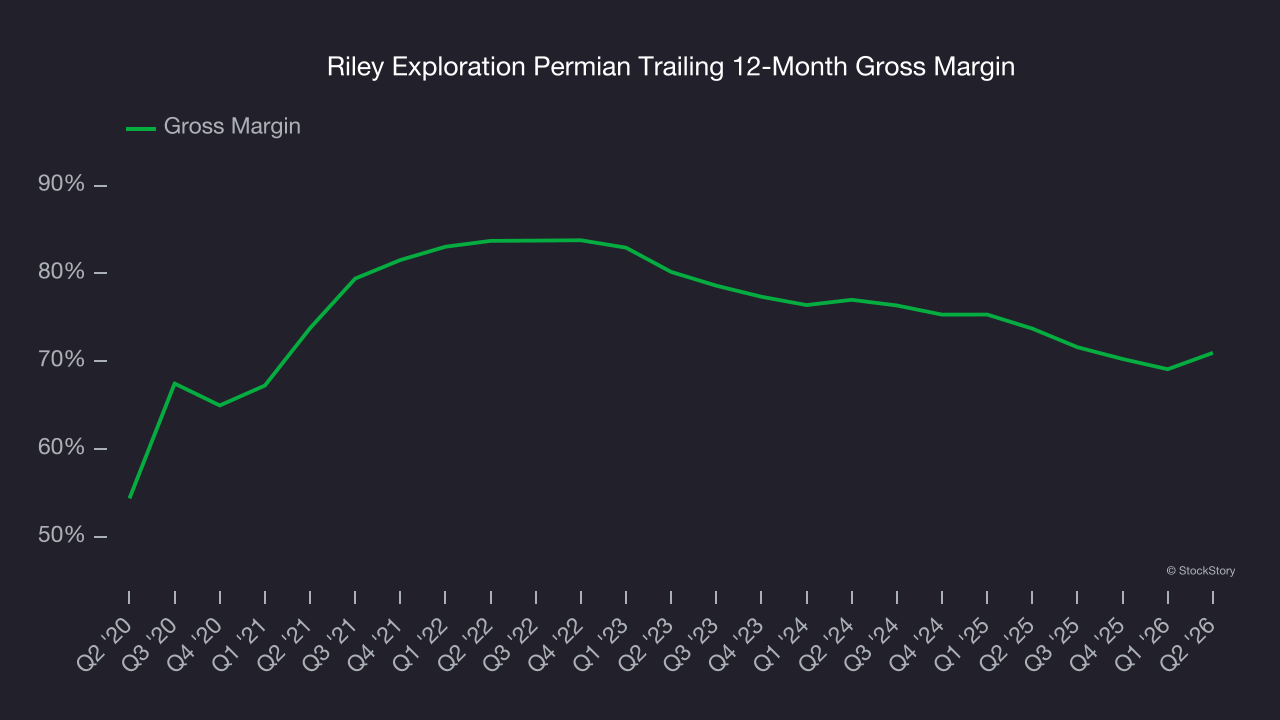
In any given year, energy gross margins are heavily influenced by prices, hedging, and cost inflation, but over a full cycle these gross margins reveal which producers are structurally advantaged through superior “rock” quality, infrastructure access, and cost position.
Riley Exploration Permian, which averaged 76.4% gross margin over the last five years, exhibits enviable unit economics in the sector. It means the company will remain profitable at lower commodity prices than peers with inferior gross margins and serves as an advantaged starting point for ultimate operating profits and free cash flow generation.
3. Excellent free cash flow margin boosts reinvestment potential
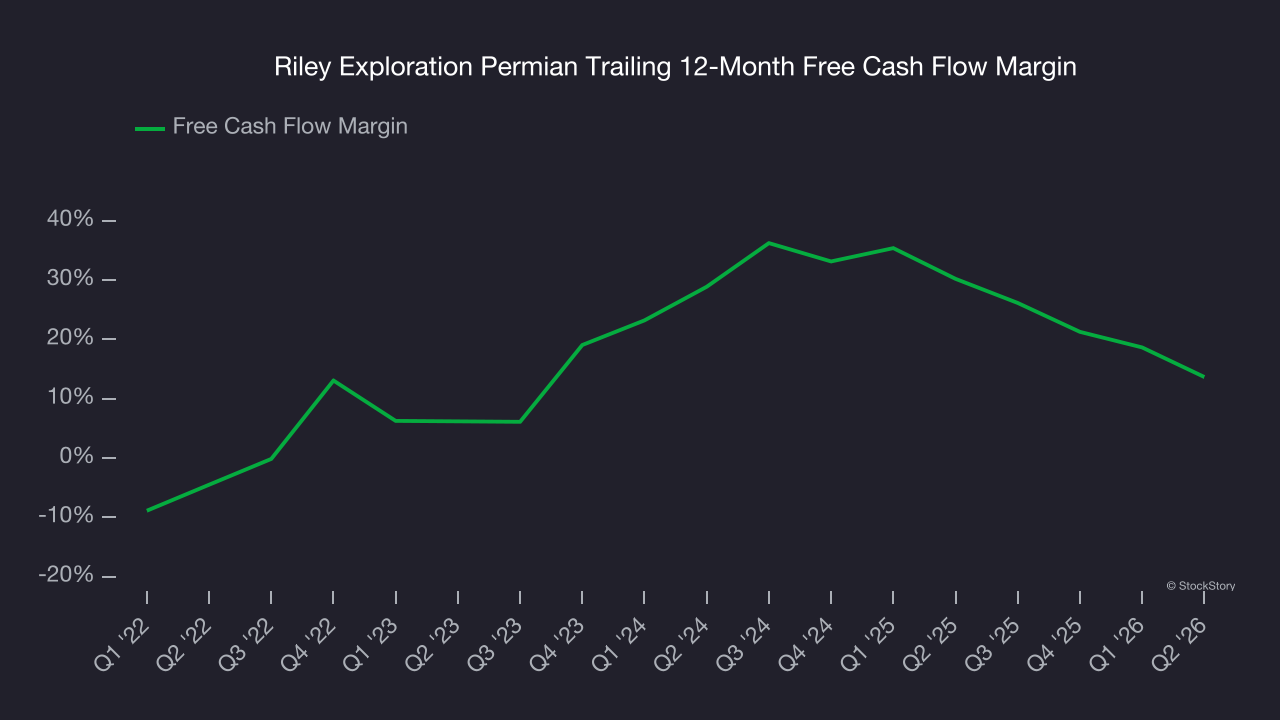
Free cash flow isn’t a prominently featured metric in company financials and earnings releases, but we think it’s telling because it accounts for all operating and capital expenses, making it tough to manipulate. Cash is king.
Riley Exploration Permian has shown robust cash profitability, driven by its attractive business model that enables it to reinvest or return capital to investors. The company’s free cash flow margin averaged 16.1% over the last five years, quite impressive for an upstream and integrated energy business.
Final judgment
These are just a few reasons why Riley Exploration Permian ranks highly on our list, and with its shares beating the market recently, the stock trades at 6.4× forward P/E (or $48.32 per share). Is now a good time to buy? See for yourself in our full research report, it’s free.
Stocks we like even more than Riley Exploration Permian
ONE MORE THING: Top 5 Growth Stocks. The biggest stock winners almost always had one thing in common before they ran. Revenue growing like crazy. Meta. CrowdStrike. Broadcom. Our AI flagged all three. They returned 315%, 314%, and 455%, respectively.
Find out which 5 stocks it’s flagging this month — FREE. Get Our Top 5 Growth Stocks for Free HERE.
Stocks that have made our list include now familiar names such as Nvidia (+1,460% between June 2020 and June 2025) as well as under-the-radar businesses like the once-micro-cap company Tecnoglass (+1,552% between June 2020 and June 2025). Find your next big winner with StockStory today.