Over the past six months, DraftKings’s stock price fell to $20.44. Shareholders have lost 11.1% of their capital, which is disappointing considering the S&P 500 has climbed by 8.9%. This was partly driven by its softer quarterly results and might have investors contemplating their next move.
Is now the time to buy DraftKings, or should you be careful about including it in your portfolio? See what our analysts have to say in our full research report, it’s free.
Why Do We Think DraftKings Will Underperform?
Even with the cheaper entry price, we’re passing on DraftKings for now. Here are three reasons we avoid DKNG, plus one stock we’d rather own.
1. Lackluster Revenue Growth
Long-term growth is the most important, but within consumer discretionary, product cycles are short and revenue can be hit-driven due to rapidly changing trends and consumer preferences. DraftKings’s recent performance shows its demand has slowed as its annualized revenue growth of 20.3% over the last two years was below its five-year trend. We’re wary when companies in the sector see decelerations in revenue growth, as it could signal changing consumer tastes aided by low switching costs. 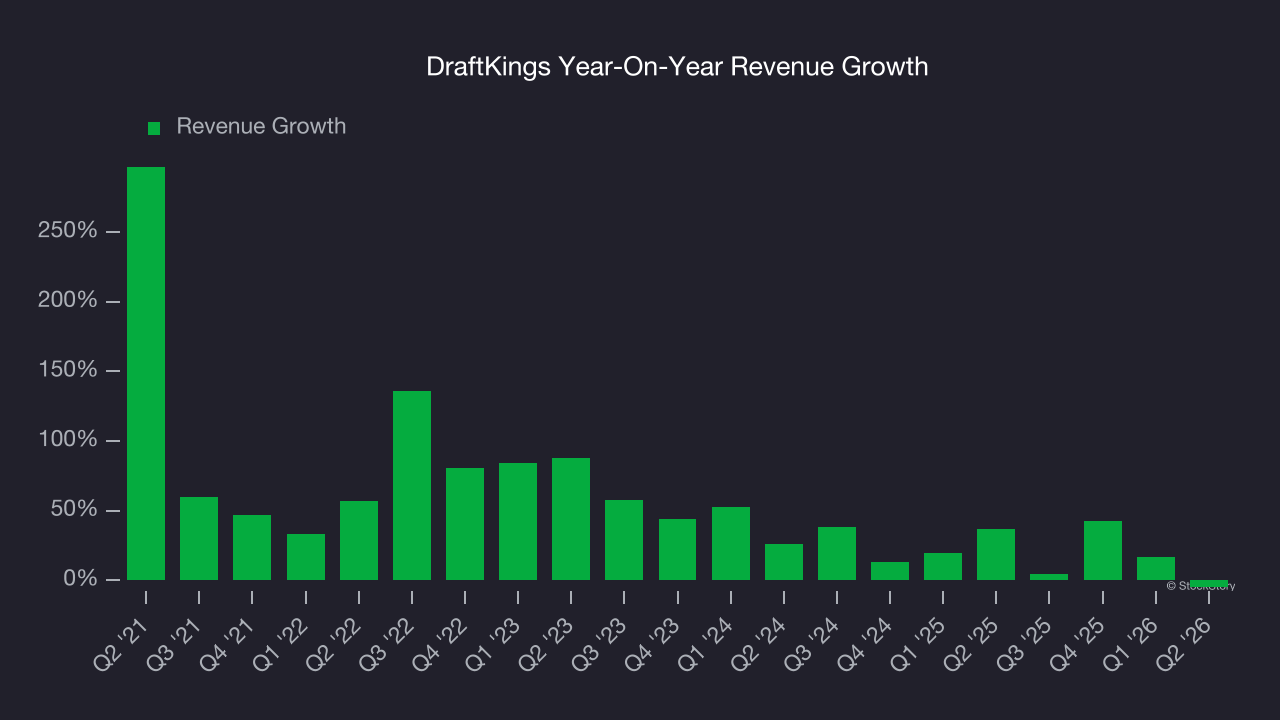
2. Operating Losses Sound the Alarm
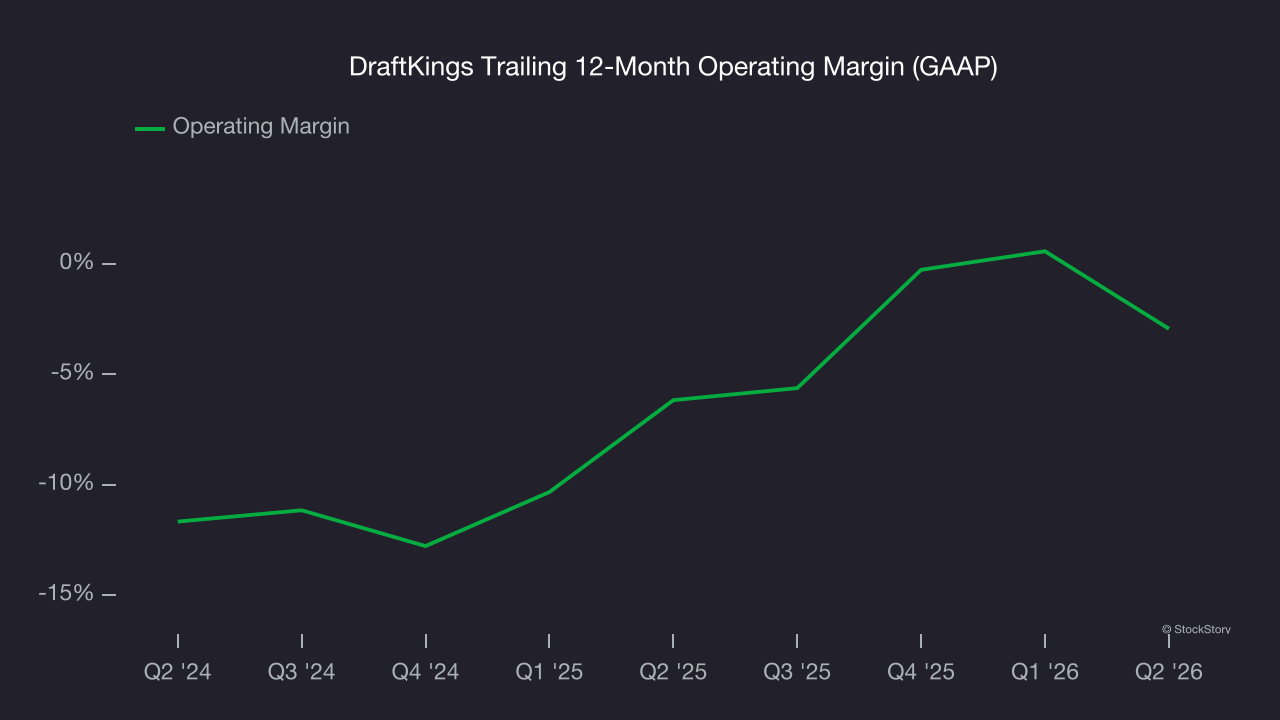
Operating margin is an important measure of profitability as it shows the portion of revenue left after accounting for all core expenses — everything from the cost of goods sold to advertising and wages. It’s also useful for comparing profitability across companies with different levels of debt and tax rates because it excludes interest and taxes.
DraftKings’s operating margin has risen over the last 12 months, but it still averaged negative 4.4% over the last two years. This is due to its large expense base and inefficient cost structure.
3. Mediocre Free Cash Flow Margin Limits Reinvestment Potential
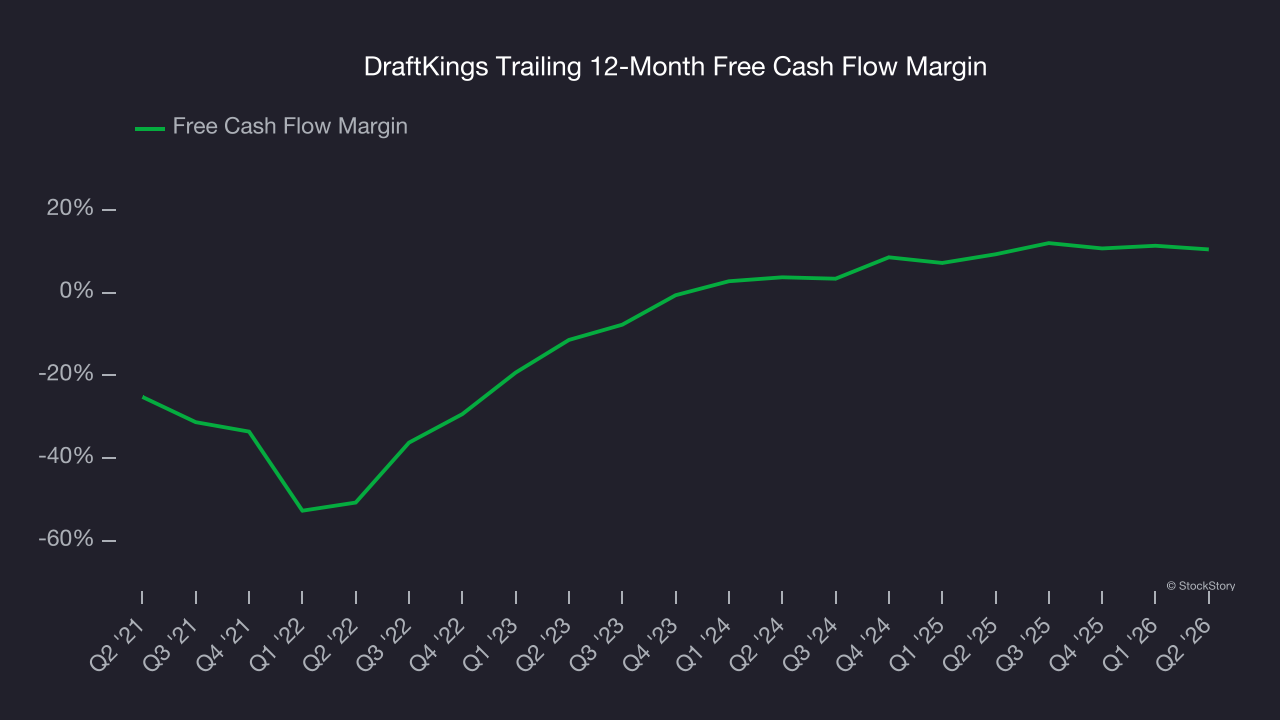
If you’ve followed StockStory for a while, you know we emphasize free cash flow. Why, you ask? We believe that in the end, cash is king, and you can’t use accounting profits to pay the bills.
DraftKings has shown poor cash profitability relative to peers over the last two years, giving the company fewer opportunities to return capital to shareholders. Its free cash flow margin averaged 9.9%, below what we’d expect for a consumer discretionary business.
Final Judgment
We cheer for all companies serving everyday consumers, but in the case of DraftKings, we’ll be cheering from the sidelines. Following the recent decline, the stock trades at 18.7× forward P/E (or $20.44 per share). While this valuation is reasonable, we don’t see a big opportunity at the moment. There are more exciting stocks to buy at the moment. We’d suggest looking at a dominant aerospace business that has perfected its M&A strategy.
Stocks We Would Buy Instead of DraftKings
ALSO WORTH WATCHING: Top 5 Momentum Stocks. The best time to own a great stock is when the market is finally noticing it. These aren’t just high-quality businesses. Something is happening with them right now. Elite fundamentals meet near-term momentum — both boxes checked at the same time.
Find out which stocks our AI platform is flagging this week. See this week’s Strong Momentum stocks — FREE. Get Our Strong Momentum Stocks for Free HERE.
Stocks that have made our list include now familiar names such as Nvidia (+1,460% between June 2020 and June 2025) as well as under-the-radar businesses like the once-micro-cap company Kadant (+214% between June 2020 and June 2025). Find your next big winner with StockStory today.