Homebuilder KB Home (NYSE: KBH) met Wall Street’s revenue expectations in Q3 CY2026, but sales fell by 20% year on year to $1.30 billion. On the other hand, the company’s full-year revenue guidance of $5 billion at the midpoint came in 2% below analysts’ estimates. Its GAAP profit of $1.05 per share was 16.7% above analysts’ consensus estimates.
Is now the time to buy KB Home? Find out by accessing our full research report, it’s free.
KB Home (KBH) Q3 CY2026 Highlights:
- Revenue: $1.30 billion vs analyst estimates of $1.30 billion (20% year-on-year decline, in line)
- EPS (GAAP): $1.05 vs analyst estimates of $0.90 (16.7% beat)
- Operating Margin: 5.2%, down from 8.4% in the same quarter last year
- Backlog: $2.05 billion at quarter end, up 3.2% year on year
- Market Capitalization: $2.93 billion
"We also made significant progress and have now achieved our goal of returning to a predominantly Built to Order business, with BTO homes representing nearly three-quarters of our deliveries in the third quarter, which contributed to our sequentially higher housing gross profit margin," said Robert McGibney, President and Chief Executive Officer. "In addition, we generated year-over-year community count growth. This reflects a significant number of new community openings over the past year that will help support our sales efforts going forward, along with a continued focus on balancing price and pace for the best possible return."
Company Overview
The first homebuilder to be listed on the NYSE, KB Home (NYSE: KBH) is a homebuilding company targeting the first-time home buyer and move-up buyer markets.
Revenue Growth
A company’s long-term performance is an indicator of its overall quality. Any business can put up a good quarter or two, but the best consistently grow over the long haul. Unfortunately, KB Home struggled to consistently increase demand as its $5.18 billion of sales for the trailing 12 months was close to its revenue five years ago. This wasn’t a great result and suggests it’s a low quality business.
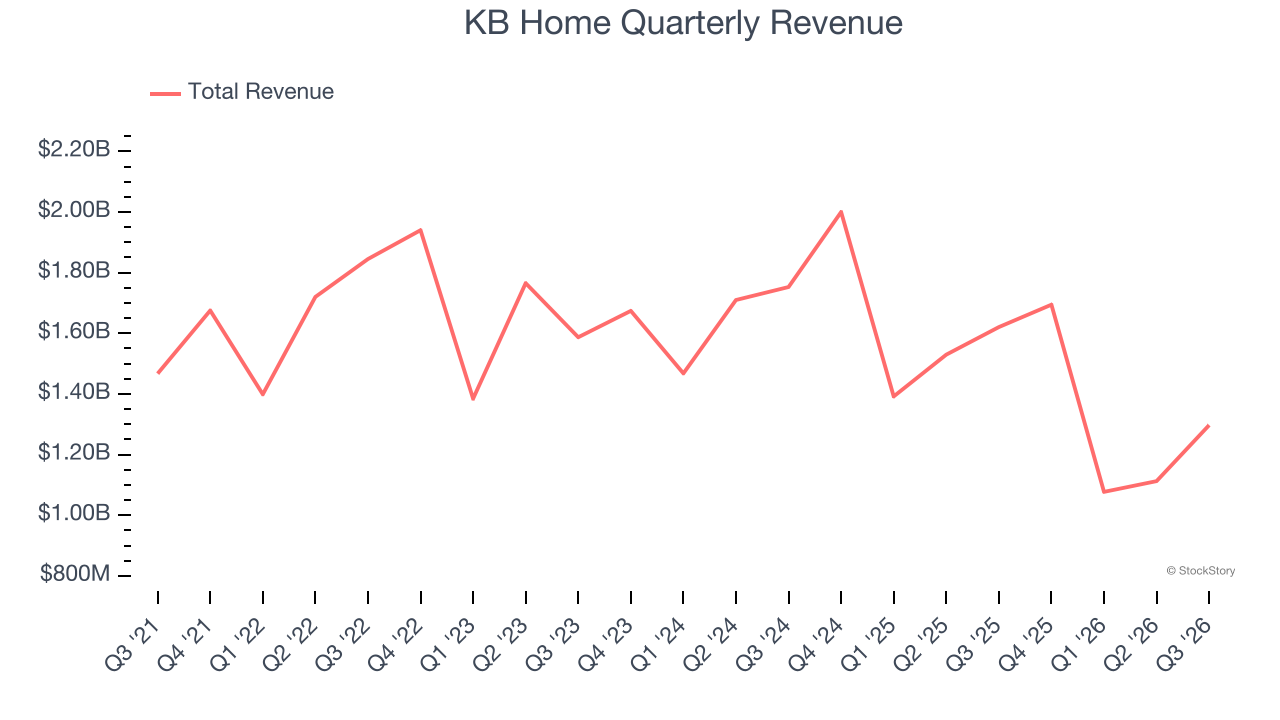
We at StockStory place the most emphasis on long-term growth, but within industrials, a half-decade historical view may miss cycles, industry trends, or a company capitalizing on catalysts such as a new contract win or a successful product line. KB Home’s recent performance shows its demand remained suppressed as its revenue has declined by 11.4% annually over the last two years. KB Home isn’t alone in its struggles as the Home Builders industry experienced a cyclical downturn, with many similar businesses observing lower sales at this time. 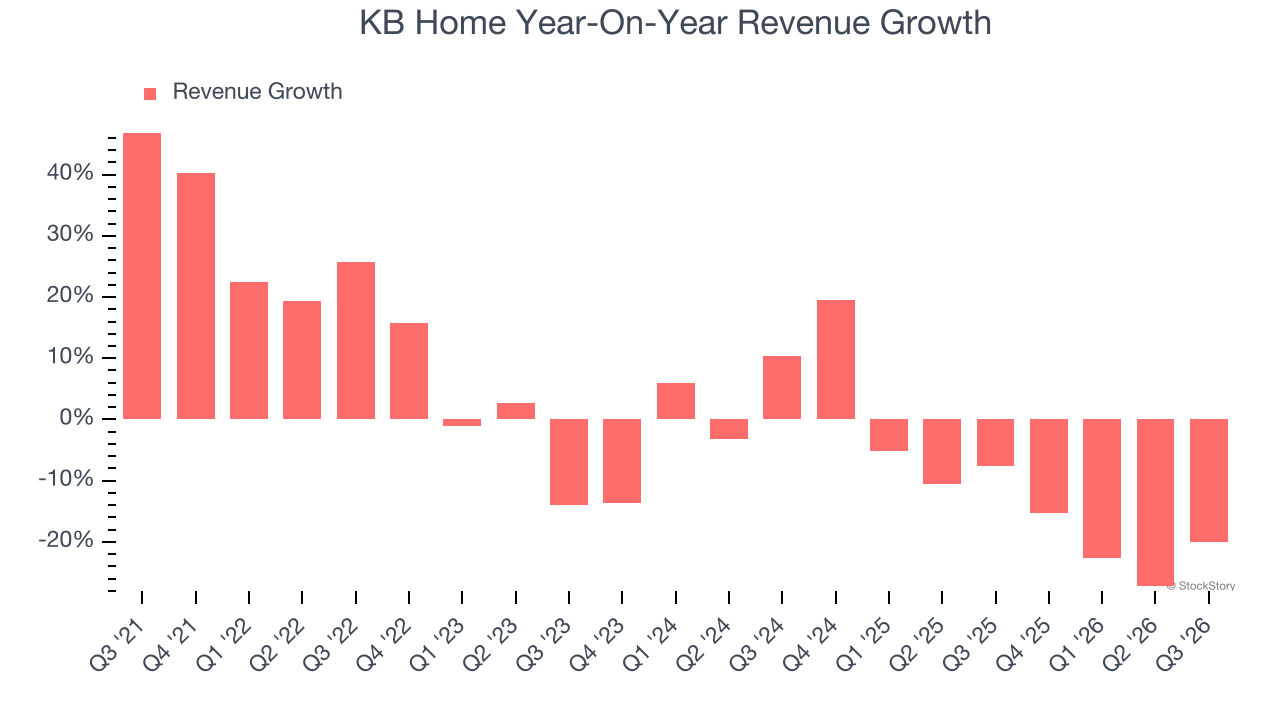
We can better understand the company’s revenue dynamics by analyzing its backlog, or the value of its outstanding orders that have not yet been executed or delivered. KB Home’s backlog reached $2.05 billion in the latest quarter and averaged 20.5% year-on-year declines over the last two years. Because this number is lower than its revenue growth, we can see the company hasn’t secured enough new orders to maintain its growth rate in the future. 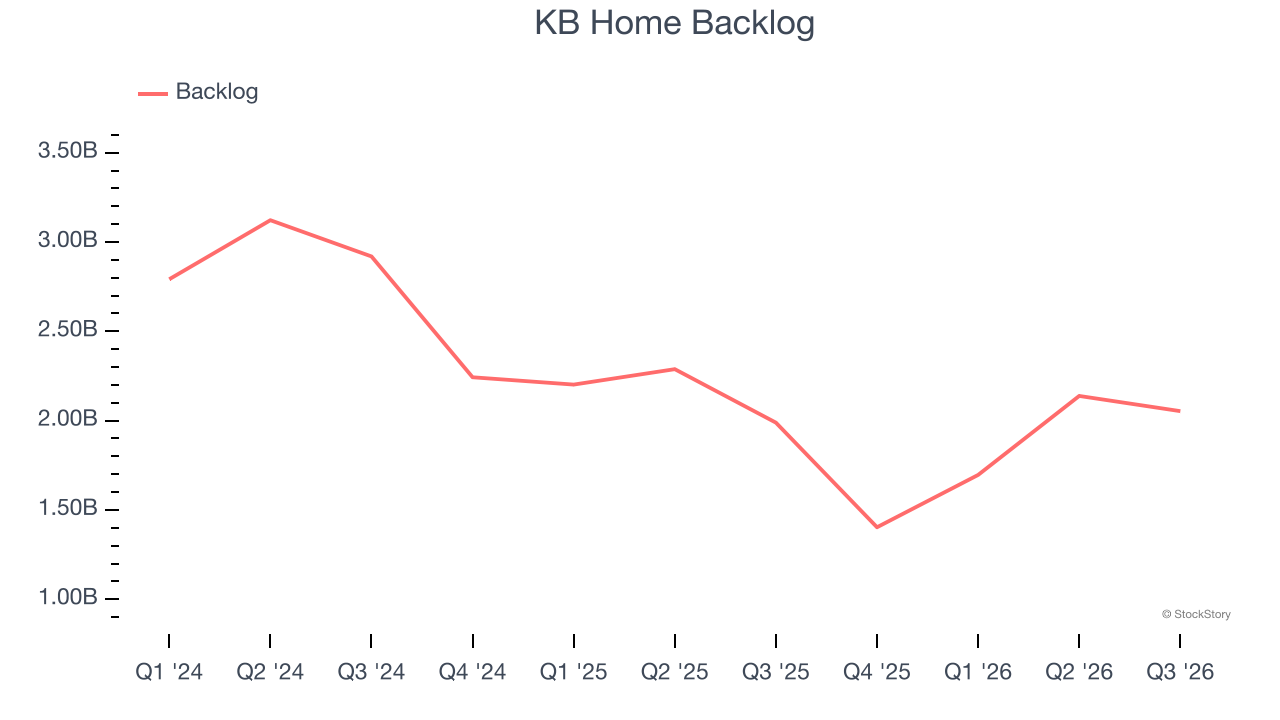
This quarter, KB Home reported a rather uninspiring 20% year-on-year revenue decline to $1.30 billion of revenue, in line with Wall Street’s estimates.
Looking ahead, sell-side analysts expect revenue to grow 6.5% over the next 12 months. Although this projection indicates its newer products and services will spur better top-line performance, it is still below the sector average.
ALSO WORTH WATCHING: Nvidia’s Quiet Partner. Nvidia’s chips cost a hundred grand. The connectors that make them work cost even more. One company makes them all.
Every AI server needs specialized infrastructure the chip companies don’t make. High-speed cables. Power connectors. Thermal sensors. This 90-year-old company built a monopoly on it. The AI boom just started. This stock is still flying under the radar. Claim The Stock Ticker Here for FREE.
Operating Margin
KB Home has managed its cost base well over the last five years. It demonstrated solid profitability for an industrials business, producing an average operating margin of 10.9%. This result was particularly impressive because of its low gross margin, which is mostly a factor of what it sells and takes huge shifts to move meaningfully. Companies have more control over their operating margins, and it’s a show of well-managed operations if they’re high when gross margins are low.
Analyzing the trend in its profitability, KB Home’s operating margin decreased by 9.9 percentage points over the last five years. Many Home Builders companies also saw their margins fall (along with revenue, as mentioned above) because the cycle turned in the wrong direction. We hope KB Home can emerge from this a stronger company, as the silver lining of a downturn is that market share can be won and efficiencies found.
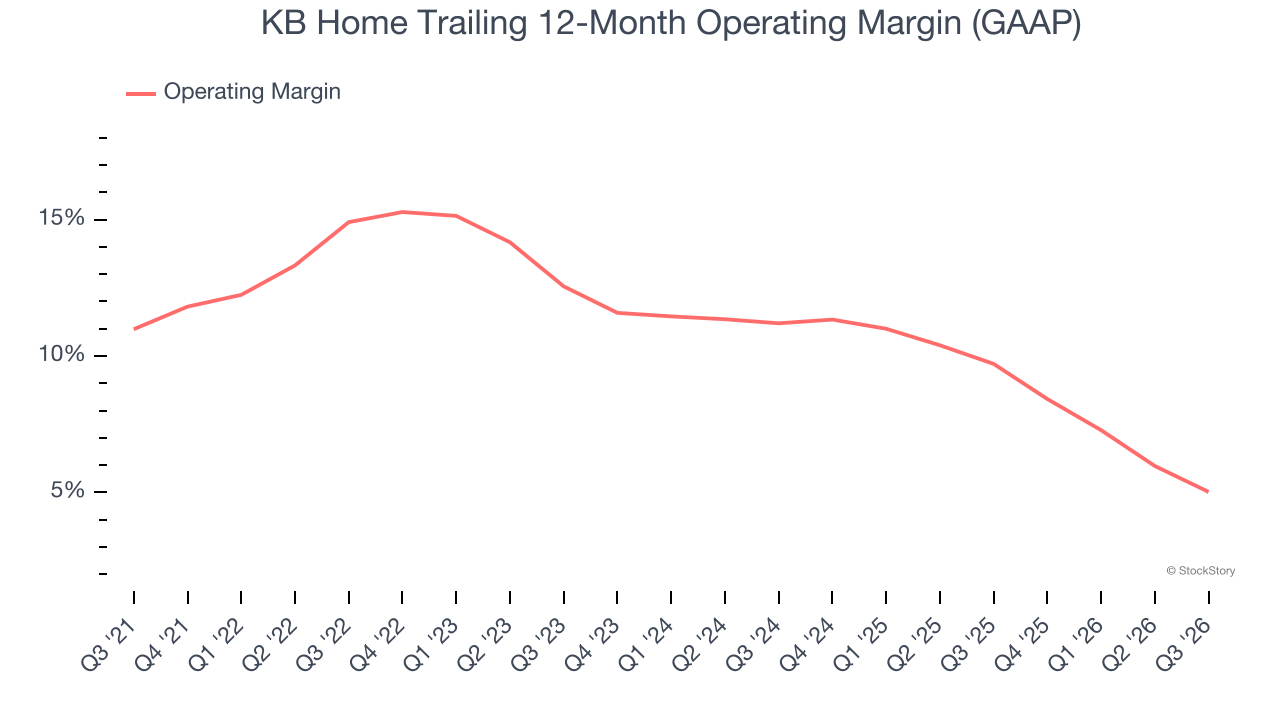
This quarter, KB Home generated an operating margin profit margin of 5.2%, down 3.2 percentage points year on year. Since KB Home’s operating margin decreased more than its gross margin, we can assume it was less efficient because expenses such as marketing, R&D, and administrative overhead increased.
Earnings Per Share
We track the long-term change in earnings per share (EPS) for the same reason as long-term revenue growth. Compared to revenue, however, EPS highlights whether a company’s growth is profitable.
Sadly for KB Home, its EPS declined by 7.4% annually over the last five years while its revenue was flat. This tells us the company struggled because its fixed cost base made it difficult to adjust to choppy demand.
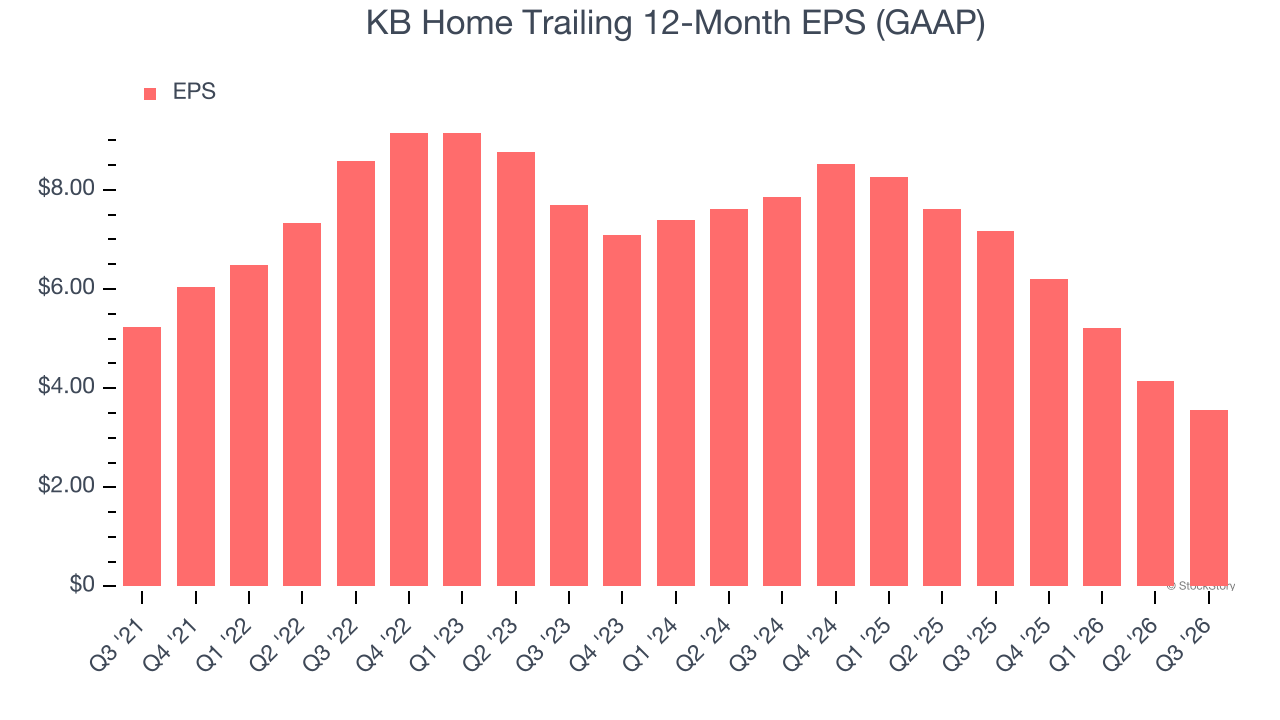
Diving into the nuances of KB Home’s earnings can give us a better understanding of its performance. As we mentioned earlier, KB Home’s operating margin declined by 9.9 percentage points over the last five years. This was the most relevant factor (aside from the revenue impact) behind its lower earnings; interest expenses and taxes can also affect EPS but don’t tell us as much about a company’s fundamentals.
Like with revenue, we analyze EPS over a shorter period to see if we are missing a change in the business.
For KB Home, its two-year annual EPS declines of 32.6% show it’s continued to underperform. These results were bad no matter how you slice the data.
In Q3, KB Home reported EPS of $1.05, down from $1.62 in the same quarter last year. Despite falling year on year, this print easily cleared analysts’ estimates. Over the next 12 months, Wall Street expects KB Home’s full-year EPS to grow 19.7% from $3.57 to $4.27.
Key Takeaways from KB Home’s Q3 Results
It was good to see KB Home beat analysts’ EPS expectations this quarter. On the other hand, its full-year revenue guidance missed. Overall, this was a softer quarter. The stock traded up 2% to $49.37 immediately after reporting.
Is KB Home an attractive investment opportunity right now? The latest quarter does matter, but not nearly as much as longer-term fundamentals and valuation, when deciding if the stock is a buy. We cover that in our actionable full research report which you can read here (it’s free).