Earnings results often indicate what direction a company will take in the months ahead. With Q2 behind us, let’s have a look at Mondelez (NASDAQ: MDLZ) and its peers.
As America industrialized and moved away from an agricultural economy, people faced more demands on their time. Packaged foods emerged as a solution offering convenience to the evolving American family, whether it be canned goods or snacks. Today, Americans seek brands that are high in quality, reliable, and reasonably priced. Furthermore, there's a growing emphasis on health-conscious and sustainable food options. Packaged food stocks are considered resilient investments. People always need to eat, so these companies can enjoy consistent demand as long as they stay on top of changing consumer preferences. The industry spans from multinational corporations to smaller specialized firms and is subject to food safety and labeling regulations.
The 17 shelf-stable food stocks we track reported a mixed Q2. As a group, revenues beat analysts’ consensus estimates by 0.8% while next quarter’s revenue guidance was 3.6% below.
Amidst this news, share prices of the companies have had a rough stretch. On average, they are down 6.3% since the latest earnings results.
Mondelez (NASDAQ: MDLZ)
Founded as Nabisco in 1903, Mondelez (NASDAQ: MDLZ) is a packaged snacks powerhouse best known for its Oreo, Cadbury, Toblerone, Ritz, and Trident brands.
Mondelez reported revenues of $9.36 billion, up 4.1% year on year. This print exceeded analysts’ expectations by 1.6%. Overall, it was a strong quarter for the company with a solid beat of analysts’ gross margin estimates and a narrow beat of analysts’ organic revenue estimates.
“Our second quarter results were marked by robust top-line expansion, coupled with volume growth and share improvement, along with improved profitability. We delivered continued strength across our Emerging Markets, as well as strong growth and elevated execution in our North America business. In Europe, share dynamics are showing early positive trends, and we believe the business is well-positioned to build on that progress," said Dirk Van de Put, Chair and Chief Executive Officer.
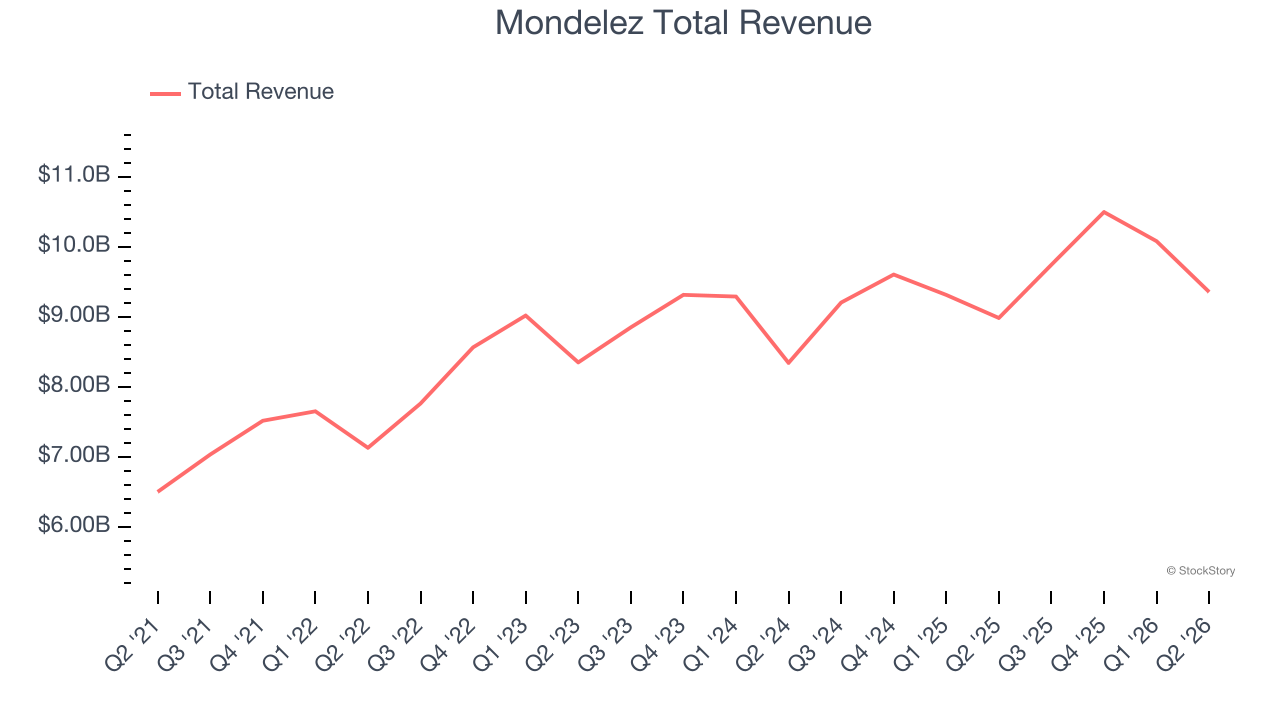
The market was likely pricing in the results, and the stock is flat since reporting. It currently trades at $62.31.
Is now the time to buy Mondelez? Access our full analysis of the earnings results here, it’s free.
Best Q2: J. M. Smucker (NYSE: SJM)
Best known for its fruit jams and spreads, J.M Smucker (NYSE: SJM) is a packaged foods company whose products span from peanut butter and coffee to pet food.
J. M. Smucker reported revenues of $2.22 billion, up 5% year on year, outperforming analysts’ expectations by 4.3%. The business had a stunning quarter with a beat of analysts’ EPS estimates and a solid beat of analysts’ EBITDA estimates.
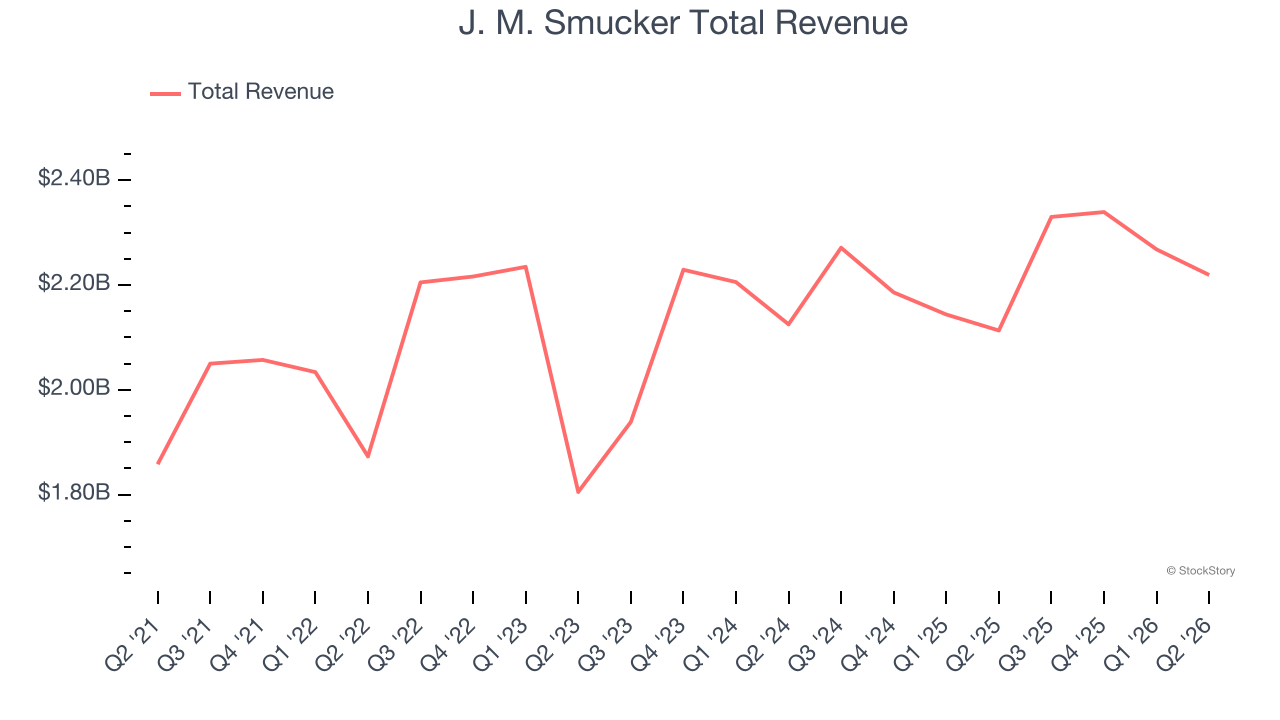
Although it had a fine quarter compared to its peers, the market seems unhappy with the results as the stock is down 1.9% since reporting. It currently trades at $123.07.
Is now the time to buy J. M. Smucker? Access our full analysis of the earnings results here, it’s free.
Weakest Q2: Hain Celestial (NASDAQ: HAIN)
Sold in over 75 countries around the world, Hain Celestial (NASDAQ: HAIN) is a natural and organic food company whose products range from snacks to teas to baby food.
Hain Celestial reported revenues of $263.1 million, down 27.6% year on year, falling short of analysts’ expectations by 2.2%. It was a softer quarter as it posted a significant miss of analysts’ gross margin estimates and EPS in line with analysts’ estimates.
Hain Celestial delivered the slowest revenue growth in the group. As expected, the stock is down 4.7% since the results and currently trades at $0.59.
Read our full analysis of Hain Celestial’s results here.
Campbell's (NASDAQ: CPB)
With its iconic canned soup as its cornerstone product, Campbell's (NASDAQ: CPB) is a packaged food company with an illustrious portfolio of brands.
Campbell's reported revenues of $2.14 billion, down 7.9% year on year. This result met analysts’ expectations. More broadly, it was a slower quarter as it produced full-year EPS guidance missing analysts’ expectations and a miss of analysts’ gross margin estimates.
The stock is down 9.7% since reporting and currently trades at $21.47.
Read our full, actionable report on Campbell's here, it’s free.
Post (NYSE: POST)
Founded in 1895, Post (NYSE: POST) is a packaged food company known for its namesake breakfast cereal and healthier-for-you snacks.
Post reported revenues of $1.95 billion, down 1.8% year on year. This number lagged analysts’ expectations by 3.7%. It was a slower quarter as it also produced a miss of analysts’ EBITDA estimates.
Post had the weakest performance against analyst estimates of the whole group. The stock is down 13% since reporting and currently trades at $78.51.
Read our full, actionable report on Post here, it’s free.
Market Update
Over the past year, investors have been forced to repeatedly answer the same question: what is the market’s biggest risk? The answer has changed several times, and each shift has reshaped market leadership.
Late in 2025 and early 2026, artificial intelligence became the market’s primary uncertainty. Investors questioned whether AI would erode software pricing power and weaken competitive moats as AI made it easier to replicate once-differentiated products.
By the spring, technology took a back seat to geopolitics. The U.S. conflict with Iran briefly became the market’s dominant narrative, raising concerns about oil prices, inflation, and global growth. But as energy markets remained orderly and fears of a prolonged supply disruption faded, investors quickly turned their focus back to fundamentals.
Want to invest in winners with rock-solid fundamentals? Check out our Strong Momentum Stocks and add them to your watchlist. These companies are poised for growth regardless of the political or macroeconomic climate.