Renasant trades at $40.53 per share and has stayed right on track with the overall market, gaining 14.8% over the last six months. At the same time, the S&P 500 has returned 12.9%.
Is there a buying opportunity in Renasant, or does it present a risk to your portfolio? Get the full breakdown from our expert analysts, it’s free.
Why Is Renasant Not Exciting?
We don’t have much confidence in Renasant. Here are three reasons why RNST doesn’t excite us, plus one stock we’d rather own.
1. Projected Net Interest Income Growth Is Slim
Forecasted net interest income by Wall Street analysts signals a company’s potential. Predictions may not always be accurate, but accelerating growth typically boosts valuation multiples and stock prices while slowing growth does the opposite.
Over the next 12 months, sell-side analysts expect Renasant’s net interest income to rise by 3.9%, a deceleration versus its 33.7% annualized growth for the past two years. This projection is below its 33.7% annualized growth rate for the past two years.
2. EPS Barely Growing
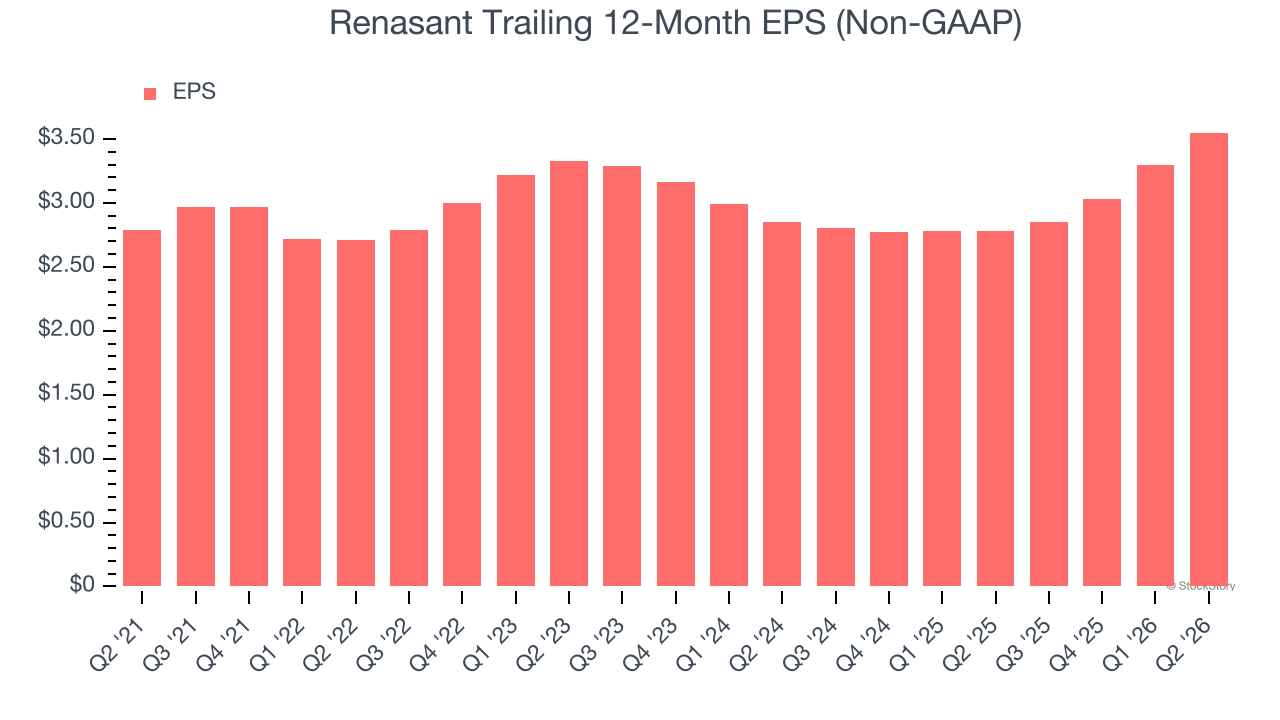
Analyzing the long-term change in earnings per share (EPS) shows whether a company’s incremental sales were profitable — for example, revenue could be inflated through excessive spending on advertising and promotions.
Renasant’s EPS grew at a weak 4.9% compounded annual growth rate over the last five years, lower than its 10.1% annualized revenue growth. This tells us the company became less profitable on a per-share basis as it expanded.
3. Substandard TBVPS Growth Indicates Limited Asset Expansion
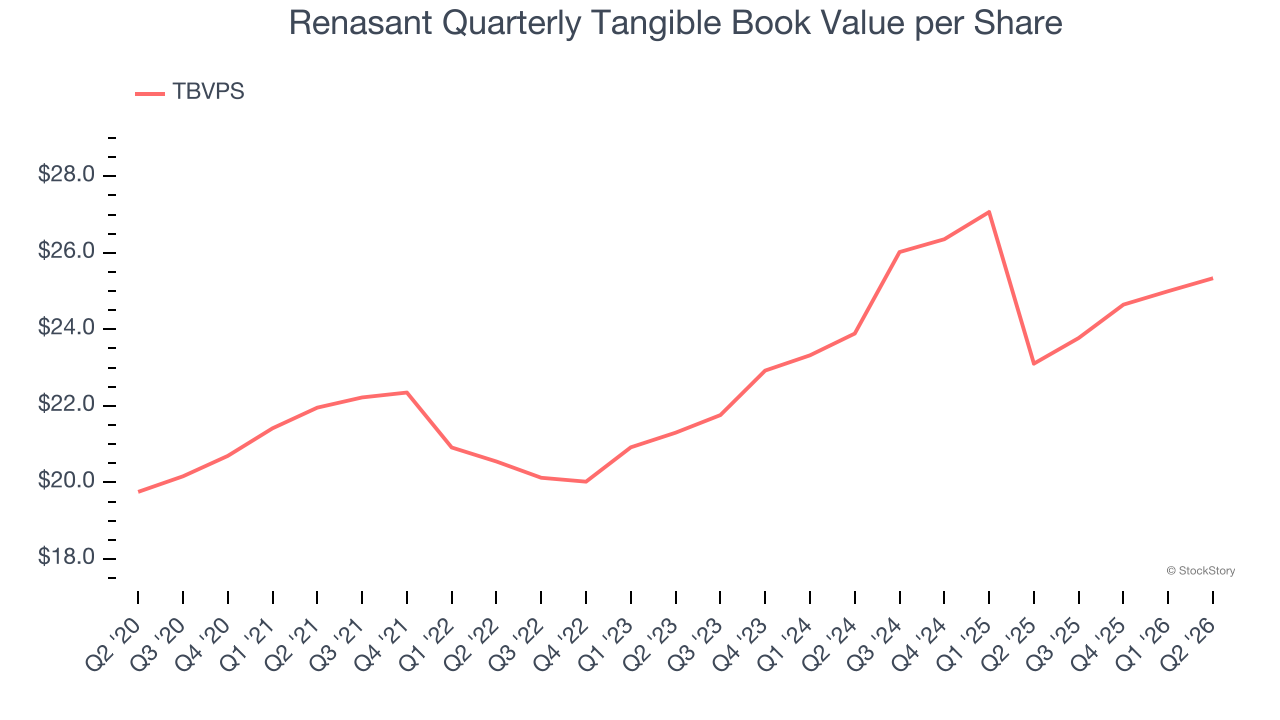
For banks, tangible book value per share (TBVPS) is a crucial metric that measures the actual value of shareholders’ equity, stripping out goodwill and other intangible assets that may not be recoverable in a worst-case scenario.
To the detriment of investors, Renasant’s TBVPS grew at a sluggish 3% annual clip over the last two years.
Final Judgment
Renasant isn’t a terrible business, but it doesn’t pass our quality test. That said, the stock currently trades at 0.9× forward P/B (or $40.53 per share). This valuation is reasonable, but the company’s shakier fundamentals present too much downside risk. We’re pretty confident there are more exciting stocks to buy at the moment. We’d suggest looking at a top digital advertising platform riding the creator economy.
Stocks We Like More Than Renasant
ALSO WORTH WATCHING: Top 5 Momentum Stocks. The best time to own a great stock is when the market is finally noticing it. These aren’t just high-quality businesses. Something is happening with them right now. Elite fundamentals meet near-term momentum — both boxes checked at the same time.
Find out which stocks our AI platform is flagging this week. See this week’s Strong Momentum stocks — FREE. Get Our Strong Momentum Stocks for Free HERE.
Stocks that have made our list include now familiar names such as Nvidia (+1,460% between June 2020 and June 2025) as well as under-the-radar businesses like the once-micro-cap company Kadant (+214% between June 2020 and June 2025). Find your next big winner with StockStory today.