Online dating app Bumble (NASDAQ: BMBL) fell short of the market’s revenue expectations in Q3 2026, with revenue falling 15.9% year on year to $207.1 million. Its non-GAAP profit of $0.15 per share was 33.9% below analysts’ consensus estimates.
For more on Bumble, read our free full research report.
Bumble (BMBL) Q3 2026 highlights:
- Revenue $207.1 million vs S&P analyst consensus of $209.1 million (15.9% year-on-year decline, 0.9% miss)
- Adjusted EPS $0.15 vs S&P analyst consensus of $0.22 (33.9% miss)
- Adjusted EBITDA $60.55 million vs analysts’ consensus estimates of $61.39 million (29.2% margin, 1.4% miss)
- Operating margin 26.3%, in line with the same quarter last year
- Free cash flow margin 25.6%, up from 24.3% in the previous quarter
- Paying users 3.08 million, down 499,100 year on year
- Market capitalization $924.5 million
Revenue growth
Reviewing a company’s long-term revenue performance reveals insights into its quality. Even a bad business can perform well for one or two quarters, but a top-tier one grows for years. Bumble’s demand was weak over the last three years as its revenue fell at a 5.7% annual rate, an underwhelming result.
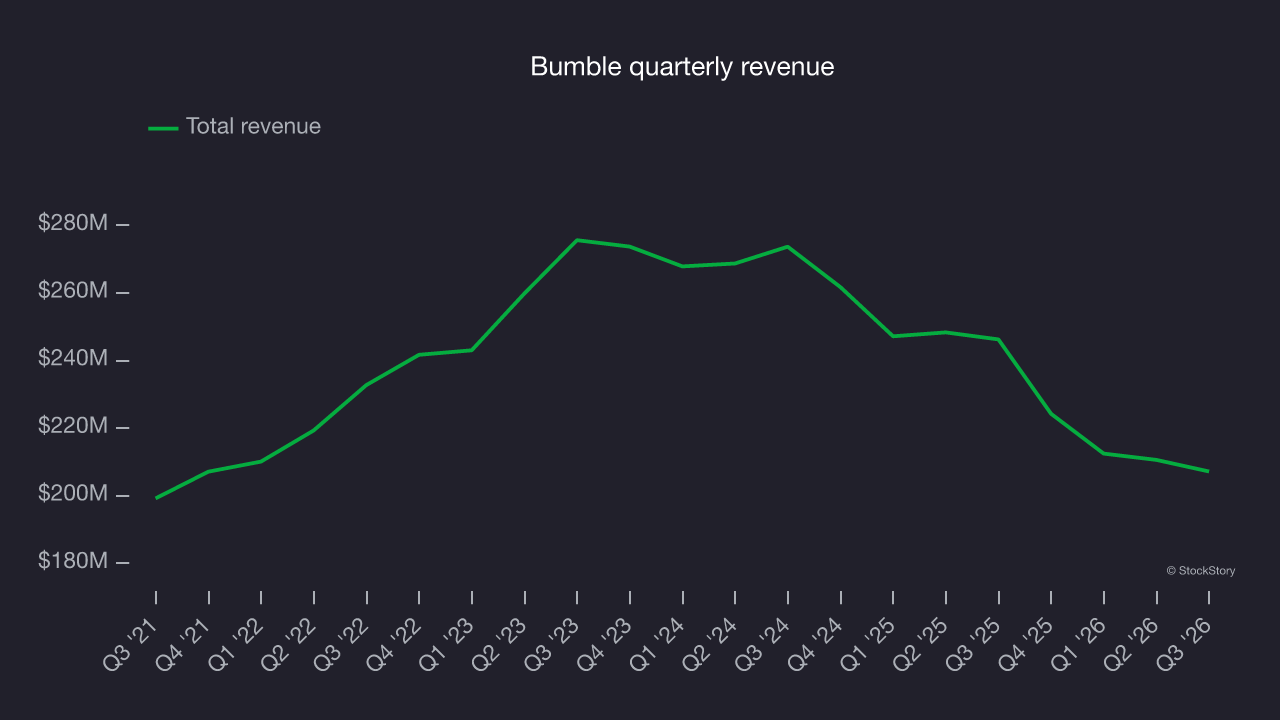
This quarter, Bumble missed Wall Street’s consensus estimates and reported an uninspiring 15.9% year-on-year revenue decline, generating $207.1 million of revenue.
Looking ahead, sell-side analysts expect revenue to decline by 8.1% over the next 12 months, according to S&P, a slight deceleration versus the last three years. The outlook is lackluster and suggests its products and services will see some demand headwinds.
Paying users
Buyer growth
As a subscription-based app, Bumble generates revenue growth by expanding both its subscriber base and the amount each subscriber spends over time.
Bumble struggled with new customer acquisition over the last two years as its paying users have declined by 10.2% annually to 3.08 million in the latest quarter. This performance is underwhelming because internet usage is secular, meaning there are typically unaddressed market opportunities. If Bumble wants to accelerate growth, it likely needs to enhance the appeal of its current offerings or innovate with new products. 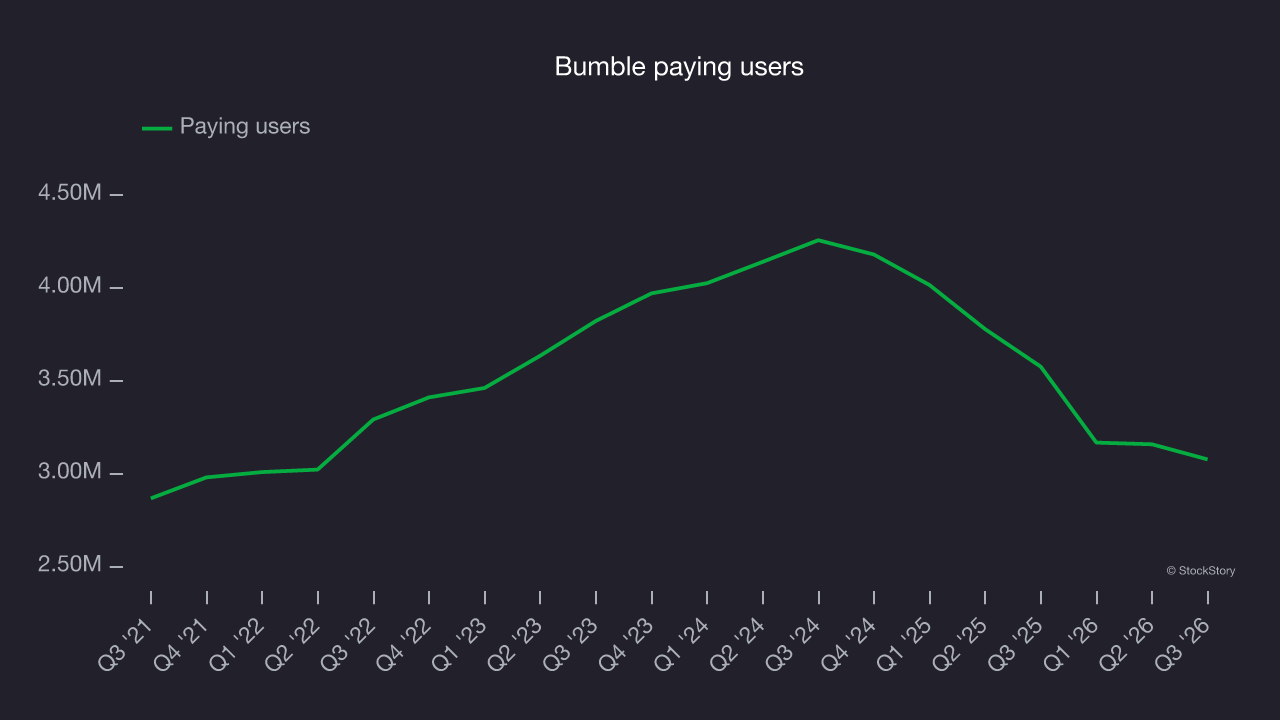
In Q3, Bumble’s paying users once again decreased by 499,100, a 14% drop since last year. The quarterly result was weaker than its two-year performance, suggesting its new initiatives aren’t yet improving buyer growth.
Revenue per buyer
Average revenue per buyer, or ARPB, is a critical metric to track because it measures how much the average buyer spends. ARPB is also a key indicator of how valuable its buyers are (and can be over time).
Bumble’s ARPB has been roughly flat over the last two years. This raises questions about its platform’s health when paired with its declining paying users. If Bumble wants to increase its buyers, it must either develop new features or provide some existing ones for free. 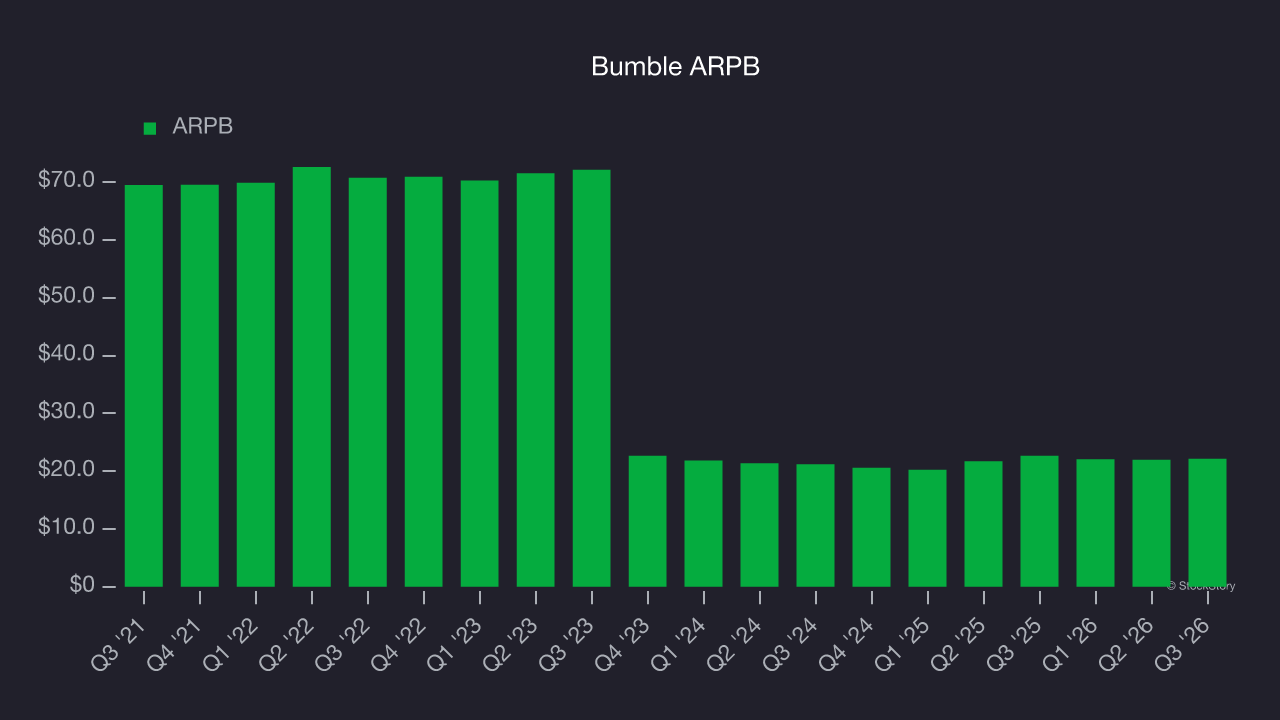
This quarter, Bumble’s ARPB was $22.14. It declined 2.2% year on year but outperformed the change in its paying users.
Key takeaways from Bumble’s Q3 results
Bumble’s shrinking buyer count and revenue that fell slightly short of Wall Street’s consensus estimates left few positives in a weaker quarter. Shares remained flat at $5.99 immediately after the report.
Bumble underperformed this quarter. When deciding whether to invest, the latest quarter matters, but not nearly as much as longer-term fundamentals and valuation. Read our full research report here (it’s free).