Animal health company Elanco (NYSE: ELAN) beat Wall Street’s revenue expectations in Q3 2026, with revenue up 11.3% year on year to $1.27 billion. Guidance for next quarter’s revenue was better than expected at $1.2 billion at the midpoint, 1.3% above analysts’ consensus estimates. Its non-GAAP profit of $0.27 per share was 32.8% above analysts’ consensus estimates.
For more on Elanco, read the full research report for free.
Elanco (ELAN) Q3 2026 highlights:
- Revenue $1.27 billion vs S&P analysts’ consensus estimates of $1.21 billion (11.3% year-on-year growth, 4.8% beat)
- Adjusted EPS $0.27 vs S&P analysts’ consensus estimates of $0.20 (32.8% beat)
- Adjusted EBITDA $243 million vs analysts’ consensus estimates of $208.4 million (19.2% margin, 16.6% beat)
- Revenue guidance $1.2 billion at the midpoint for Q4 2026, above analysts’ consensus estimates of $1.19 billion
- Adjusted EPS guidance Management raised its full-year adjusted EPS guidance to $1.19 at the midpoint, a 4.9% increase
- EBITDA guidance $1.06 billion at the midpoint for the full year, above analysts’ consensus estimates of $1.02 billion
- Operating margin 18%, up from 0.2% in the same quarter last year
- Constant currency revenue rose 9% year on year, in line with the same quarter last year
- Market capitalization $11.83 billion
"Third quarter results demonstrate Elanco is a consistent, reliable growth company, delivering our diverse portfolio of innovation along with accelerating cash flow," stated Jeff Simmons, President and CEO of Elanco. "Organic constant currency revenue growth of 9% was led by International Pet Health up 17% and U.S. Pet Health up 13%, as we saw strong veterinarian and pet owner demand for what we believe is 'best medicine' innovation for our 'Big 6' growth led by Zenrelia and Credelio Quattro. Price accelerated to 4% growth, exceeding our expectations, while volume remained robust at 5%. Our durable top-line is fueled by a significant runway for share gains off a small base in large, growing, global markets. Both Zenrelia and Credelio Quattro reached new market share highs in September, with competitive activity having no fundamental impact on the trajectory of our innovation. At the same time, adjusted gross margin expanded 300 basis points, we invested in our commercial execution, and we drove our net leverage ratio to the 2.9x milestone which accelerates our capital allocation flexibility. As we are raising full-year guidance to fully pass through the third quarter beat, Elanco is well positioned with momentum heading into 2027. We are recommitting to our annual algorithm of mid-single digit organic constant currency revenue growth, high-single digit adjusted EBITDA growth, and low-double digit adjusted EPS growth, building on this year's expected outperformance and creating sustainable value for our customers, our shareholders, and the industry."
Revenue growth
Examining a company’s long-term performance can provide clues about its quality. Any business can put up a good quarter or two, but many enduring ones grow for years. Over the last five years, Elanco grew its revenue at a tepid 1.4% compounded annual growth rate, falling short of our benchmarks.
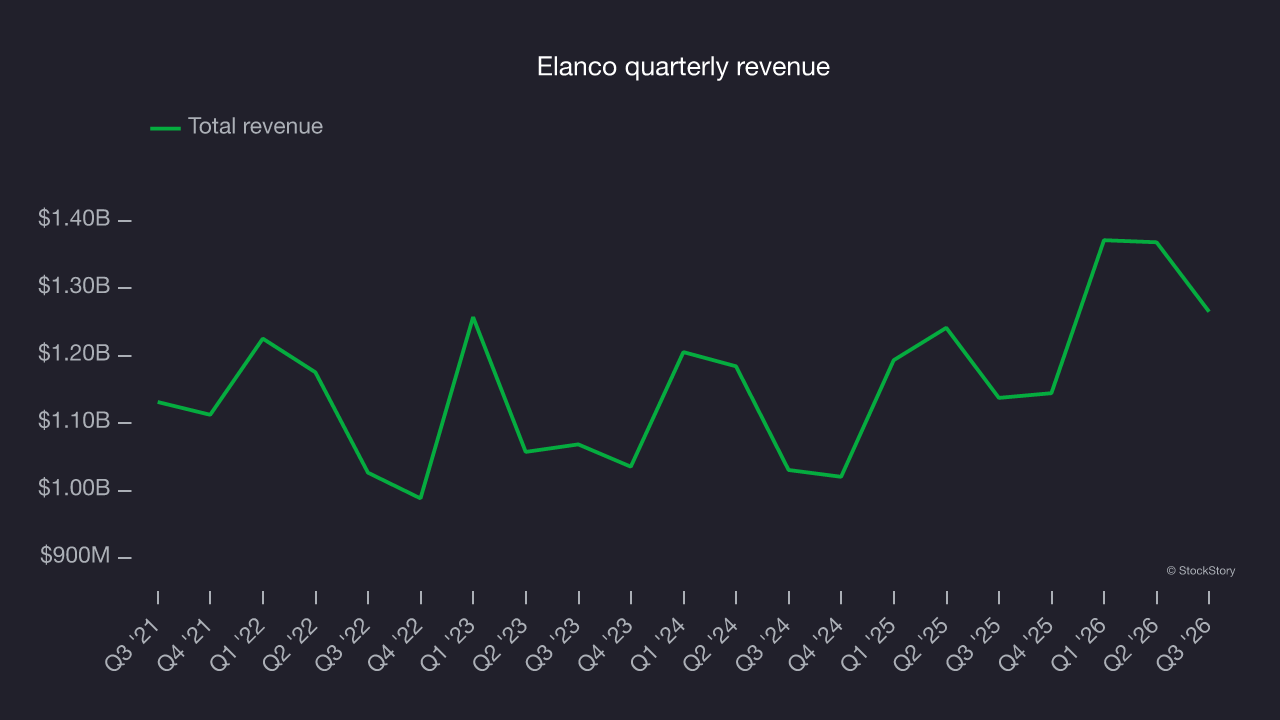
Long-term growth is the most important, but within healthcare, a half-decade historical view may miss new innovations or demand cycles. Elanco’s annualized revenue growth of 7.5% over the last two years is above its five-year trend, suggesting some bright spots.
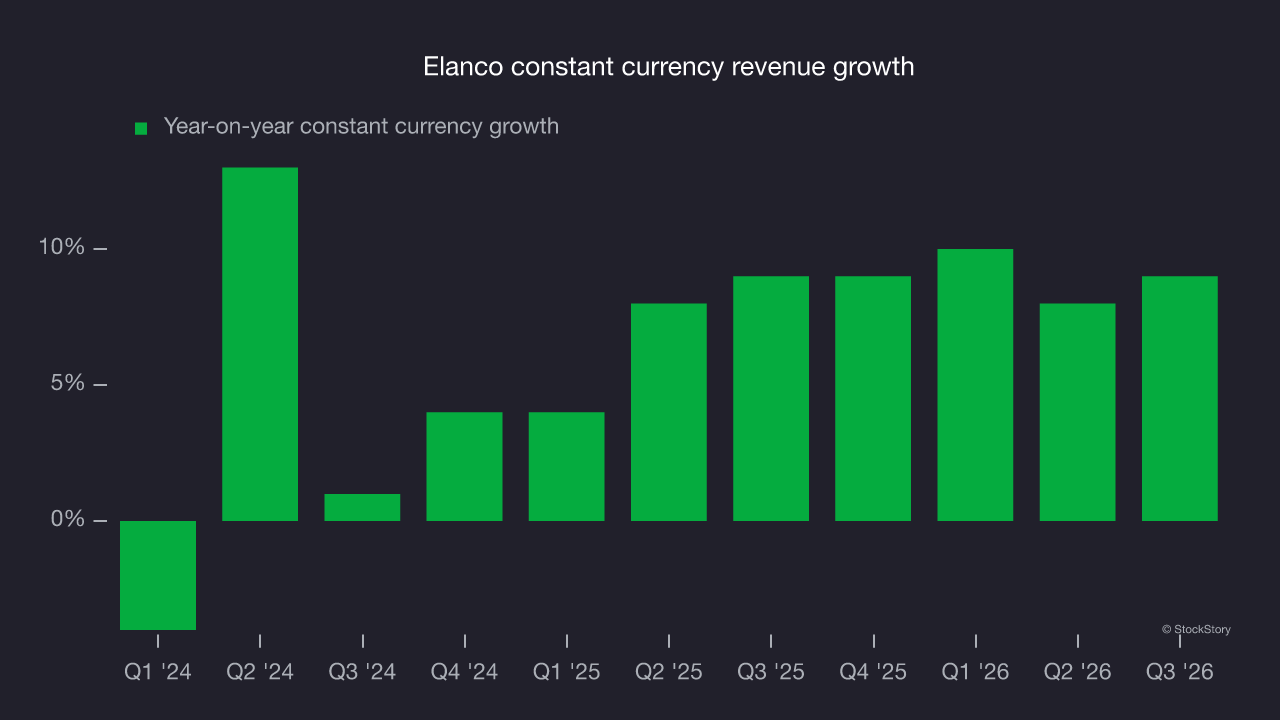
Elanco also reports revenue performance excluding currency movements, which are outside the company’s control and not indicative of demand. Over the last two years, its constant currency revenue averaged 7.6% year-on-year growth. This was in line with reported revenue growth, indicating that foreign exchange has not had a meaningful impact on revenue.
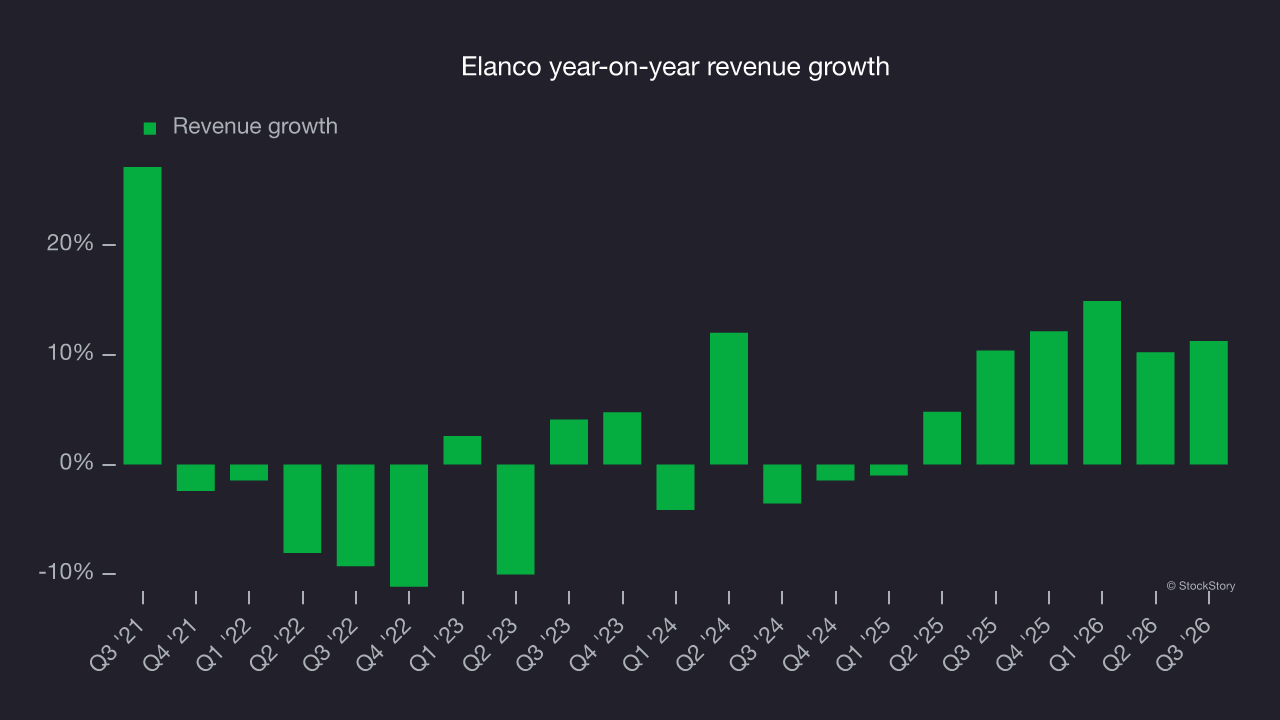
This quarter, Elanco reported year-on-year revenue growth of 11.3%, and its $1.27 billion of revenue exceeded Wall Street’s consensus estimates by 4.8%. Management is guiding for a 5.1% year-on-year increase in revenue next quarter.
Looking further ahead, sell-side analysts expect revenue to grow 3.6% over the next 12 months, according to S&P, a deceleration versus the last two years. This underwhelming projection implies its products and services will face some demand challenges.
Adjusted operating margin
Adjusted operating margin is one of the best measures of profitability because it shows how much a company earns after subtracting all core expenses, like marketing and research and development. It also removes various one-time costs to give a clearer picture of normalized profits.
Elanco has managed its cost base well over the last five years. It demonstrated solid profitability for a healthcare business, producing an average adjusted operating margin of 18.6%.
Looking at the trend in its profitability, Elanco’s adjusted operating margin decreased by 2.8 percentage points over the last five years. This raises questions about the company’s expense base because its revenue growth should have given it leverage on its fixed costs, resulting in better economies of scale and profitability.
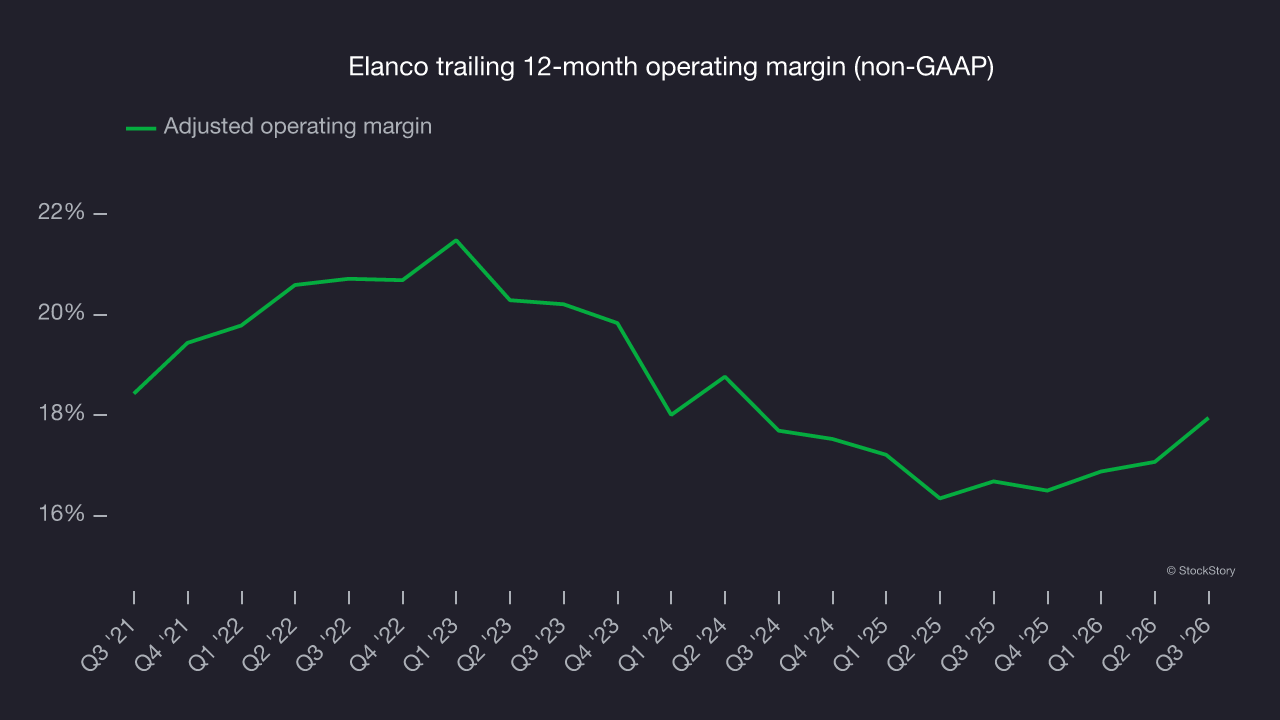
This quarter, Elanco generated an adjusted operating margin of 18%, up 3.9 percentage points year on year. This improvement shows it was more efficient.
Earnings per share
Long-term growth in earnings per share, or EPS, matters for the same reason as long-term revenue growth. Compared to revenue, however, EPS highlights whether a company’s growth is profitable.
Elanco’s EPS grew at a 3.5% compounded annual growth rate over the last five years. This performance was better than its revenue growth, but that comparison warrants caution because its adjusted operating margin improvement lagged peers’ and it didn’t repurchase its shares, meaning the difference came from reduced interest expenses or taxes.
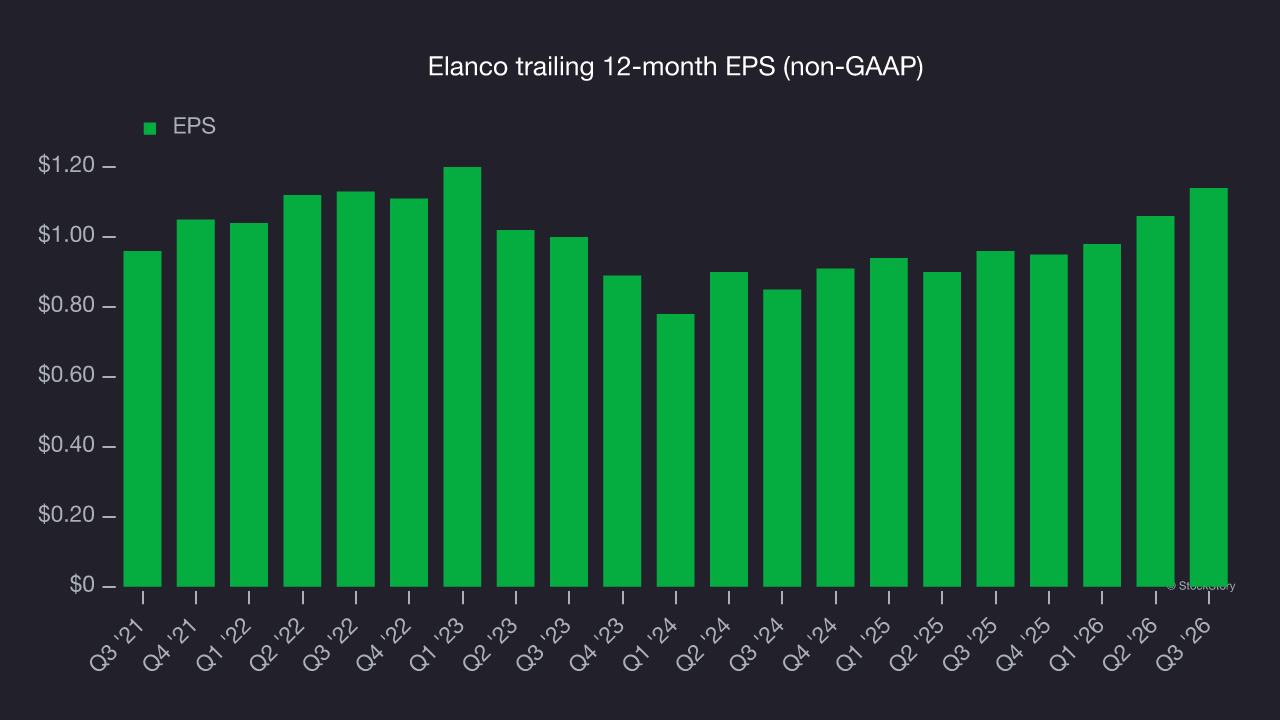
In Q3, Elanco reported adjusted EPS of $0.27, up from $0.19 in the same quarter last year. This result easily cleared analysts’ consensus estimates, a positive outcome for shareholders. Over the next 12 months, Wall Street expects Elanco’s full-year EPS to grow 6.6% from $1.14 to $1.22, according to S&P.
Key takeaways from Elanco’s Q3 results
Elanco delivered a solid Q3, with revenue and EPS both topping analysts’ consensus estimates. Shares surged 7.4% to $25.45 immediately after the results.
Elanco reported solid earnings, but one quarter doesn’t necessarily make the stock a buy. When making that decision, it’s important to consider its valuation and business quality as well as what happened in the latest quarter. Read our full research report here (it’s free).