Payment processing company Shift4 Payments (NYSE: FOUR) fell short of the market’s revenue expectations in Q3 2026, but revenue rose 12.1% year on year to $1.32 billion. Its non-GAAP profit of $1.49 per share was 9.1% above analysts’ consensus estimates.
For more on Shift4, read our full research report for free.
Shift4 (FOUR) Q3 2026 highlights:
- Revenue $1.32 billion vs S&P analysts’ consensus estimates of $1.33 billion (12.1% year-on-year growth, 0.9% miss)
- Pre-tax profit $66 million (5% margin)
- Adjusted EPS $1.49 vs S&P analysts’ consensus estimates of $1.37 (9.1% beat)
- Adjusted EPS guidance Management lowered its full-year adjusted EPS guidance to $5.10 at the midpoint, a 2.9% decrease
- Market capitalization $3.54 billion
Revenue growth
Examining a company’s long-term performance can provide clues about its quality. Any business can have short-term success, but a top-tier one grows for years. Shift4’s revenue grew at a strong 33.1% compounded annual growth rate over the last five years. Its growth surpassed the average financials company and shows its offerings resonate with customers.
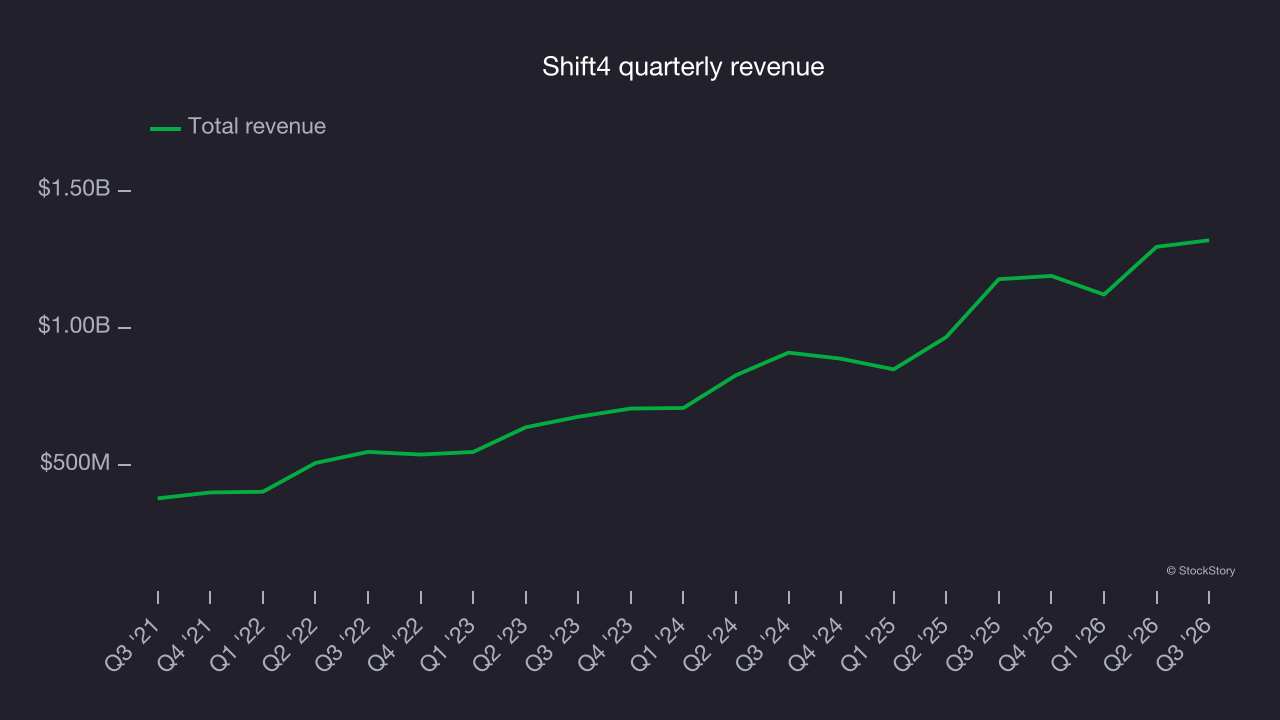
Long-term growth matters most, but within financials, a half-decade historical view may miss recent interest rate changes, market returns and industry trends. Shift4’s annualized revenue growth of 25% over the last two years is below its five-year trend, but the results still suggest healthy demand. 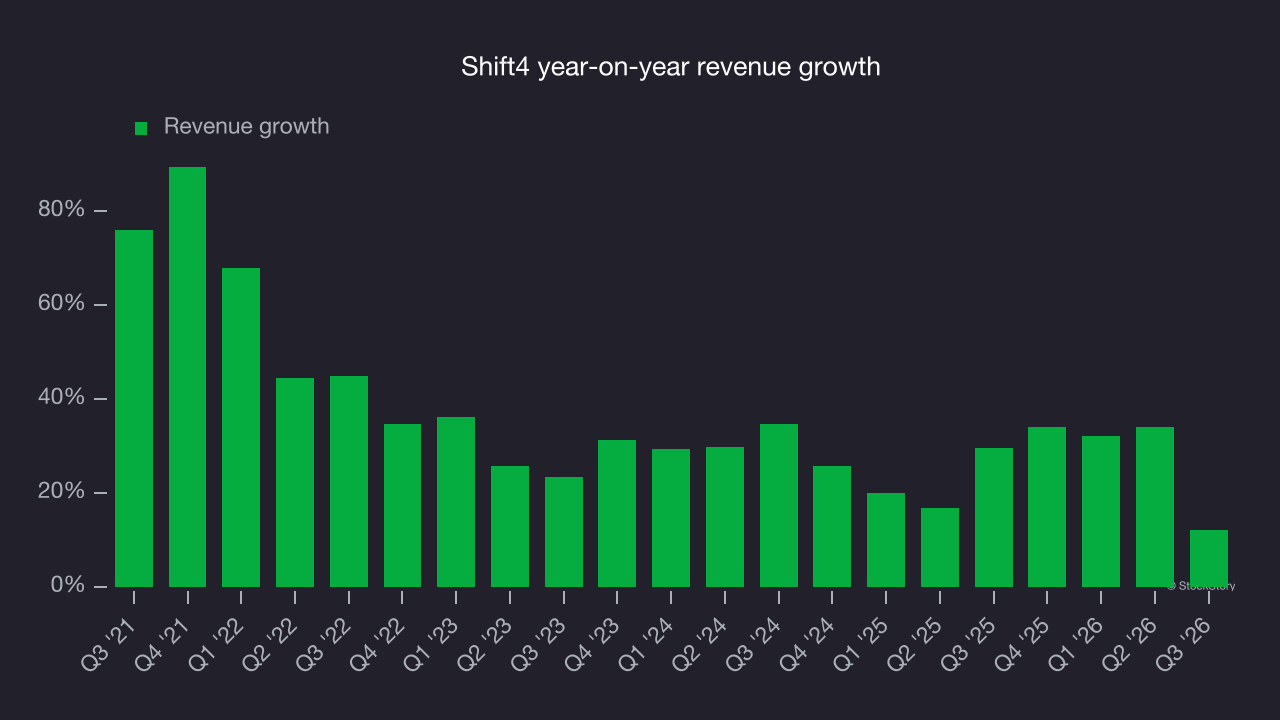
This quarter, Shift4’s revenue grew by 12.1% year on year to $1.32 billion but fell short of Wall Street’s consensus estimates.
Key takeaways from Shift4’s Q3 results
Shift4’s EPS beat analysts’ consensus estimates, but the rest of its Q3 results left room for improvement: Revenue fell slightly short of Wall Street’s consensus estimates, and full-year EPS guidance also missed. Taken together, the quarter could have been better. Shares plunged 10.5% to $40.06 immediately after the results.
Shift4’s latest quarter matters when deciding whether to invest at the current price, but longer-term business quality and valuation matter more. Read the full research report here (it’s free).