Even though TFS Financial (currently trading at $16.18 per share) has gained 8.3% over the last six months, it has lagged the S&P 500’s 14.3% return during that period. This may have investors wondering how to approach the situation.
Is there a buying opportunity in TFS Financial, or does it present a risk to your portfolio? Dive into our full research report to see our analyst team’s opinion, it’s free.
Why Do We Think TFS Financial Will Underperform?
We’re cautious about TFS Financial. Here are three reasons why TFSL doesn’t excite us, plus one stock we’d rather own.
1. Net Interest Income Points to Soft Demand
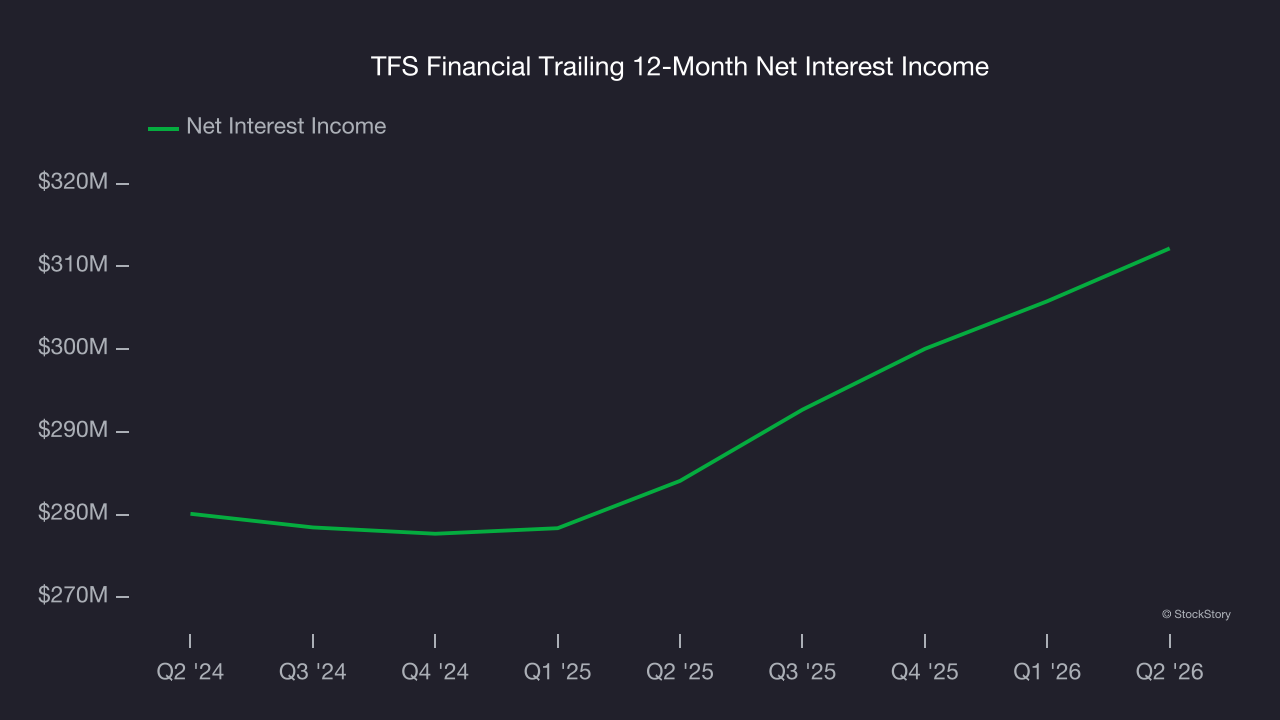
Net interest income commands greater market attention due to its reliability and consistency, whereas one-time fees are often seen as lower-quality revenue that lacks the same dependable characteristics.
TFS Financial’s net interest income has grown at a 6.8% annualized rate over the last five years, worse than the broader banking industry. Its growth was driven by both an increase in its outstanding loans and net interest margin, which represents how much a bank earns in relation to its outstanding loan book.
2. Low Net Interest Margin Reveals Weak Loan Book Profitability
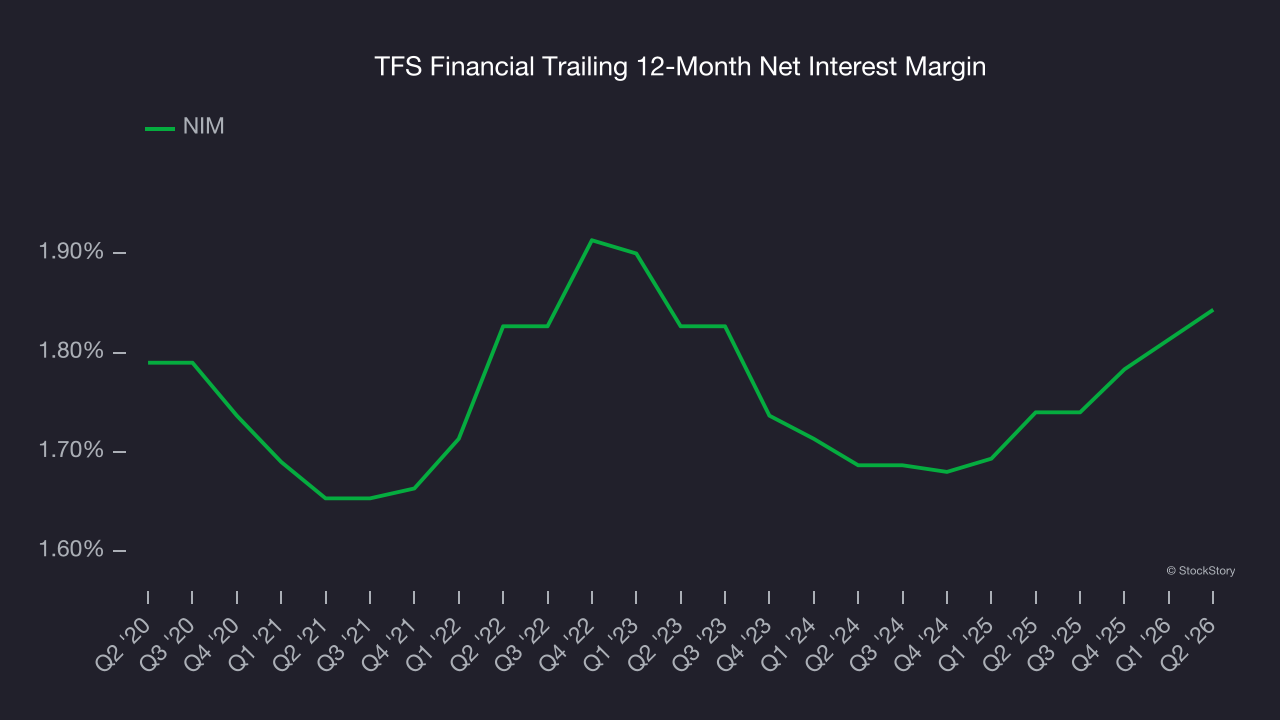
Net interest margin (NIM) represents the unit economics of a bank by measuring the profitability of its interest-bearing assets relative to its interest-bearing liabilities. It’s a fundamental metric that investors use to assess lending premiums and returns.
Over the past two years, we can see that TFS Financial’s net interest margin averaged a poor 1.8%, reflecting its high servicing and capital costs.
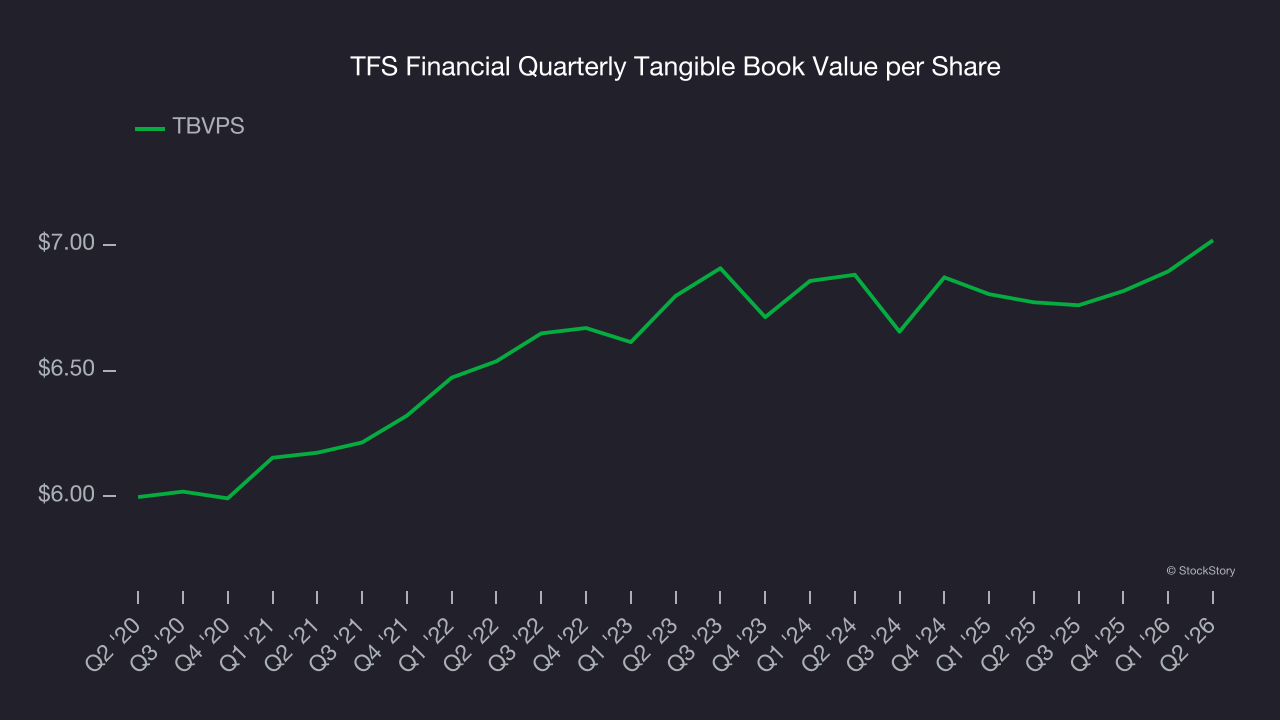
3. Projected TBVPS Growth Shows Limited Upside
The key to tangible book value per share (TBVPS) growth is a bank’s ability to earn consistent returns on its assets that exceed its funding costs and credit losses.
Over the next 12 months, Consensus estimates call for TFS Financial’s TBVPS to remain flat at roughly $7.08, a disappointing projection.
Final Judgment
We cheer for all companies supporting the economy, but in the case of TFS Financial, we’ll be cheering from the sidelines. With its shares underperforming the market lately, the stock trades at 2.3× forward P/B (or $16.18 per share). This multiple tells us a lot of good news is priced in - we think other companies feature superior fundamentals at the moment. We’d suggest looking at one of our all-time favorite software stocks.
High-Quality Stocks for All Market Conditions
ALSO WORTH WATCHING: Top 5 Momentum Stocks. The best time to own a great stock is when the market is finally noticing it. These aren’t just high-quality businesses. Something is happening with them right now. Elite fundamentals meet near-term momentum — both boxes checked at the same time.
Find out which stocks our AI platform is flagging this week. See this week’s Strong Momentum stocks — FREE. Get Our Strong Momentum Stocks for Free HERE.
Stocks that have made our list include now familiar names such as Nvidia (+1,460% between June 2020 and June 2025) as well as under-the-radar businesses like the once-micro-cap company Tecnoglass (+1,552% between June 2020 and June 2025). Find your next big winner with StockStory today.