Fintech mortgage provider Rocket Companies (NYSE: RKT) beat Wall Street’s revenue expectations in Q3 2026, with revenue up 84.2% year on year to $3.28 billion. On the other hand, next quarter’s revenue guidance of $2.2 billion was less impressive, coming in 14.2% below analysts’ consensus estimates. Its non-GAAP profit of $0.15 per share was 12.4% above analysts’ consensus estimates.
For more on Rocket Companies, read our full research report, available free.
Rocket Companies (RKT) Q3 2026 highlights:
- Revenue $3.28 billion vs S&P analysts’ consensus estimates of $2.59 billion (84.2% year-on-year growth, 26.7% beat)
- Adjusted EPS $0.15 vs S&P analysts’ consensus estimates of $0.13 (12.4% beat)
- Revenue guidance $2.2 billion at the midpoint for Q4 2026, below analysts’ consensus estimates of $2.56 billion
- Market capitalization $32.76 billion
"Rocket gained market share in both purchase and refinance, quarter over quarter and year over year, and delivered our highest profitability margin in nearly five years, even as mortgage rates climbed to a three-year high," said Varun Krishna, CEO and Director of Rocket Companies. "We didn't spend the last three years waiting for rates to fall. We acquired distribution, connected real estate and mortgage, and invested heavily in technology. We changed the economics of our business. Rates went up. We took share. Profits grew. That's not a coincidence."
Revenue growth
Two primary revenue streams drive bank earnings. While net interest income, which is earned by charging higher rates on loans than paid on deposits, forms the foundation, fee-based services across banking, credit, wealth management and trading operations provide additional income. Over the last five years, Rocket Companies’s demand was weak and its revenue declined by 6.8% per year. This fell short of our standards and suggests it is a lower-quality business.
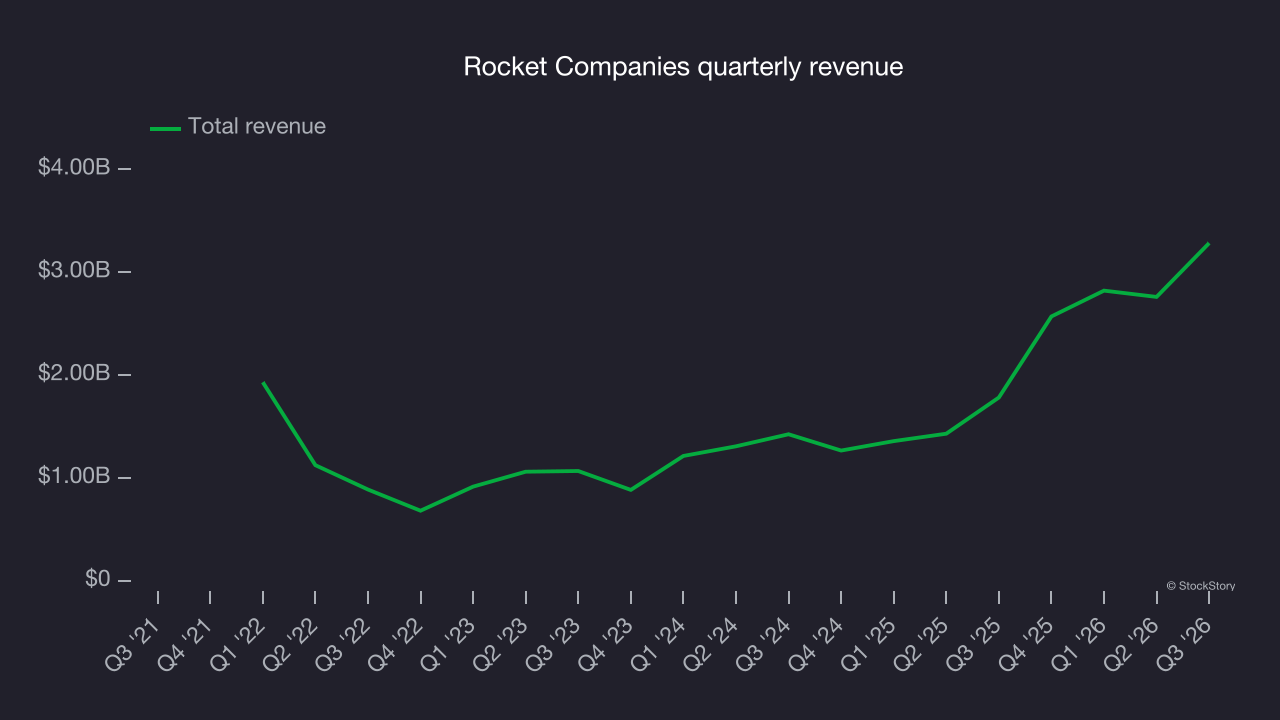 Note: Quarters not shown were determined to be outliers because they were impacted by outsized investment gains/losses that are not indicative of the recurring fundamentals of the business.
Long-term growth is the most important, but within financials, a half-decade historical view may miss recent interest rate changes and market returns. Rocket Companies’s annualized revenue growth of 53.8% over the last two years is above its five-year trend, suggesting its demand recently accelerated. 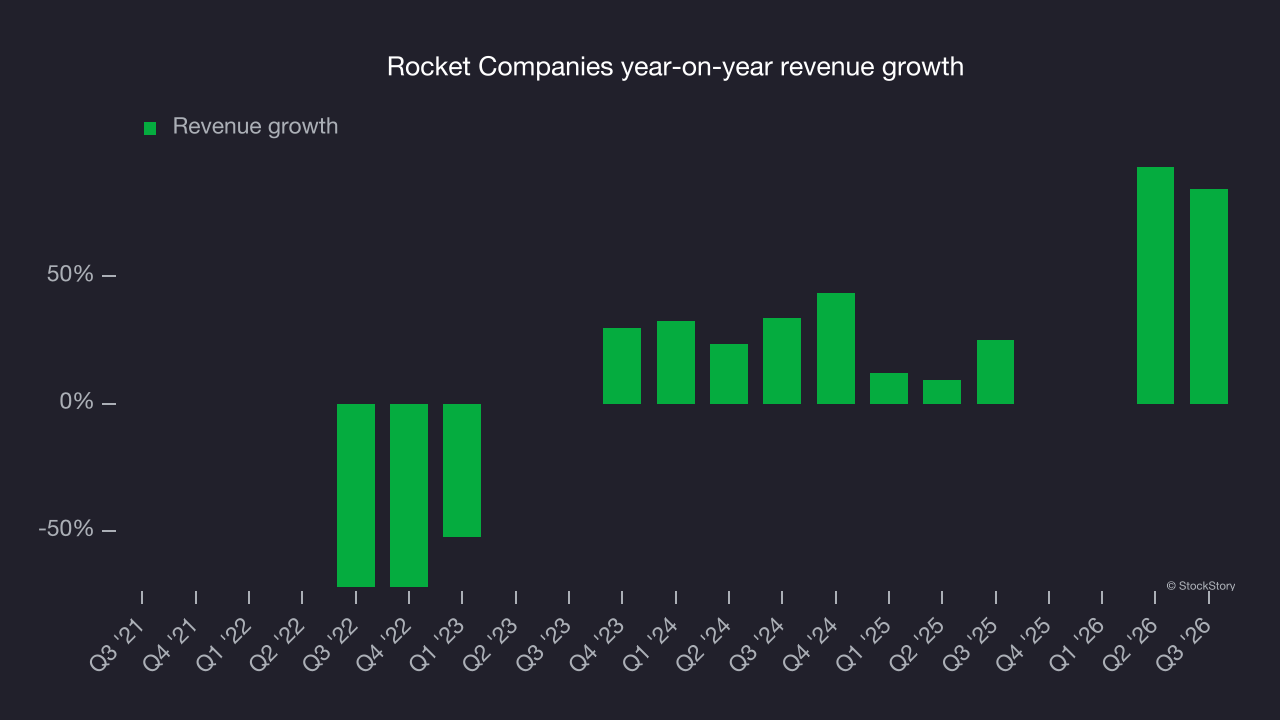 Note: Quarters not shown were determined to be outliers because they were impacted by outsized investment gains/losses that are not indicative of the recurring fundamentals of the business.
This quarter, Rocket Companies reported year-on-year revenue growth of 84.2%, and its $3.28 billion of revenue beat Wall Street’s consensus estimates by 26.7%. Company management is currently guiding for a 14.4% year-on-year decline in revenue next quarter.
Key takeaways from Rocket Companies’s Q3 results
Rocket Companies delivered some important positives this quarter, with revenue well ahead of analysts’ consensus estimates and EPS also topping Wall Street’s estimates. Shares rose 2% to $12.21 immediately after the report.
Rocket Companies reported solid earnings, but one quarter doesn’t necessarily make the stock a buy. The latest quarter does matter, but not nearly as much as longer-term fundamentals and valuation when deciding if the stock is a buy. For more on those factors, read our full research report here (it’s free).