Digital medical services platform Teladoc Health (NYSE: TDOC) reported Q3 2026 results exceeding the market’s revenue expectations, but revenue fell by 3.4% year on year to $605.1 million. On the other hand, next quarter’s revenue guidance of $592 million was less impressive, coming in 0.8% below analysts’ consensus estimates. Its GAAP loss of $0.15 per share was 30% above analysts’ consensus estimates.
For more on Teladoc, read our full research report, available free.
Teladoc (TDOC) Q3 2026 highlights:
- Revenue $605.1 million vs S&P analysts’ consensus estimates of $588.4 million (3.4% year-on-year decline, 2.8% beat)
- EPS (GAAP) -$0.15 vs analysts’ consensus estimates of -$0.21 (30% beat)
- Adjusted EBITDA $79.36 million vs analysts’ consensus estimates of $68.08 million (13.1% margin, 16.6% beat)
- Revenue guidance $592 million at the midpoint for Q4 2026, below analysts’ consensus estimates of $596.6 million
- GAAP EPS guidance -$0.85 at the midpoint for the full year, beating analysts’ consensus estimates by 4.5%
- EBITDA guidance $290 million at the midpoint for the full year, above analysts’ consensus estimates of $278.6 million
- Operating margin -4.6%, improved from -8.3% in the same quarter last year
- Free cash flow margin 12.5%, increased from 10.5% in the previous quarter
- Market capitalization $1.17 billion
“We delivered third quarter results near the upper end of our guidance range for consolidated revenue and above our range for consolidated adjusted EBITDA, reflecting solid execution across our two segments,” said Chuck Divita, Chief Executive Officer of Teladoc Health.
Revenue growth
A company’s long-term revenue performance is one signal of its overall quality. Any business can experience short-term success, but top-performing ones sustain growth for years. Teladoc struggled to consistently generate demand over the last three years as its revenue dropped at a 1.5% annual rate. This fell short of our standards and points to poor business quality.
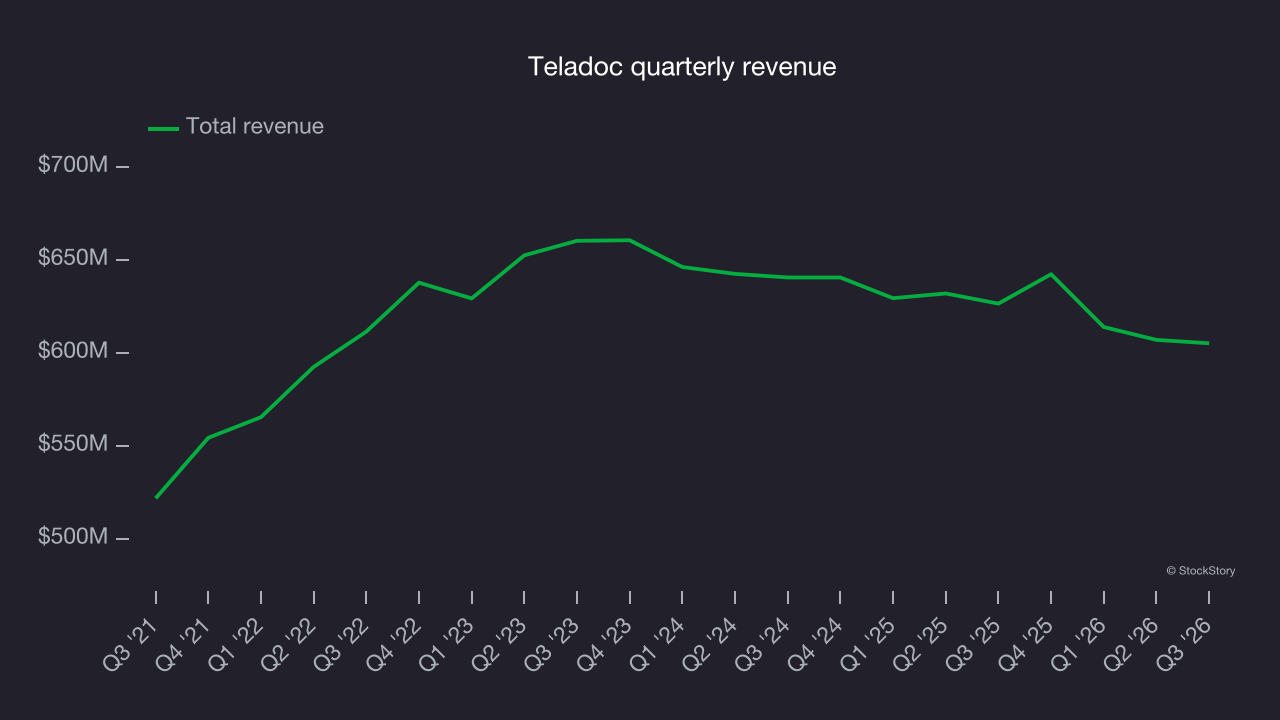
This quarter, Teladoc’s revenue fell by 3.4% year on year to $605.1 million but beat Wall Street’s consensus estimates by 2.8%. Company management is currently guiding for a 7.8% year-on-year decline in revenue next quarter.
Looking further ahead, sell-side analysts expect revenue to decline by 4.5% over the next 12 months, according to S&P, a deceleration versus the last three years. This underwhelming projection implies its products and services will face some demand challenges.
Cash flow
Although EBITDA is valuable for assessing company performance, cash matters more because accounting profits alone can’t pay the bills.
Teladoc has shown strong cash profitability, driven by its attractive business model that gives it the option to reinvest or return capital to investors. The company’s free cash flow margin averaged 10.3% over the last two years, better than the broader consumer internet sector.
Teladoc’s margin dropped by 1 percentage point over the last few years. Continued declines could signal it is in the middle of an investment cycle.
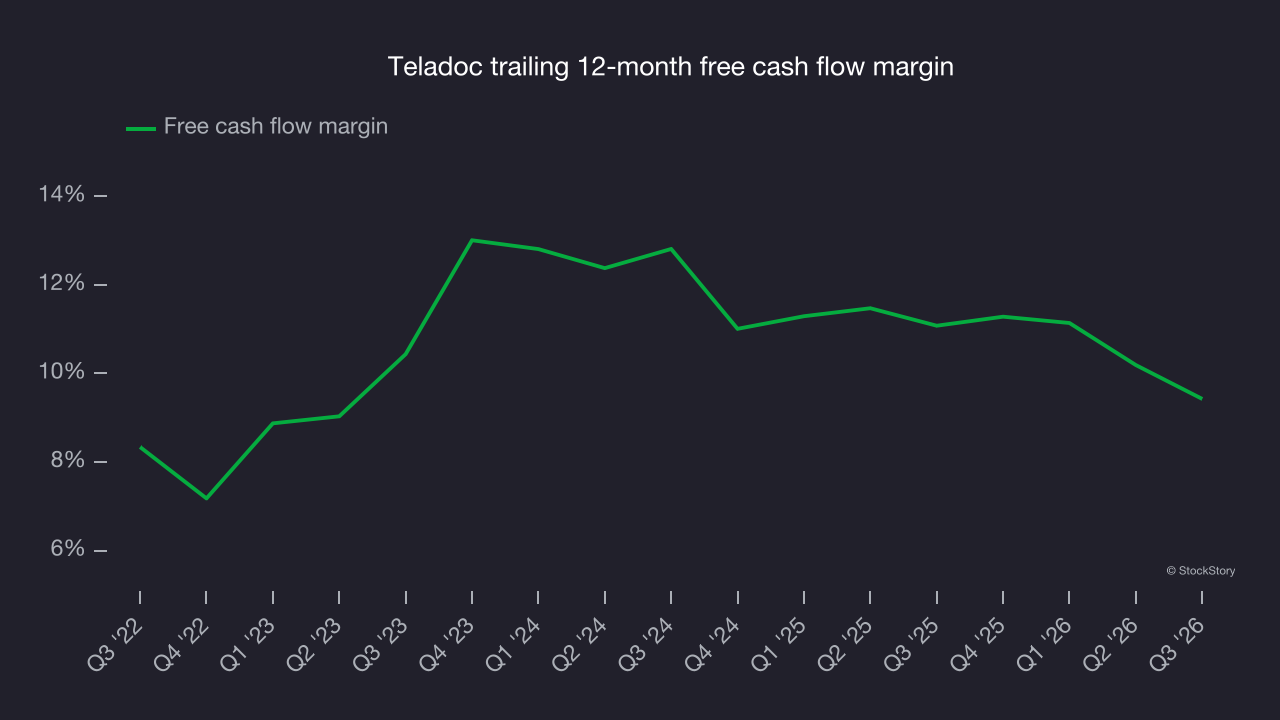
Teladoc’s free cash flow totaled $75.94 million in Q3, equivalent to a 12.5% margin. The company’s cash profitability declined, with its margin 2.9 percentage points lower than in the same quarter last year, but still above its two-year average. This quarter’s decline warrants limited weight because investment needs can be seasonal, causing short-term swings. Long-term trends are more important.
Key takeaways from Teladoc’s Q3 results
Teladoc delivered some key positives this quarter: EBITDA beat analysts’ consensus estimates by a wide margin, and full-year EBITDA guidance topped Wall Street’s consensus. Next-quarter revenue guidance, however, fell slightly short of expectations. Shares soared 11.5% to $7.55 immediately after the report.
Teladoc reported solid earnings, but one quarter doesn’t necessarily make the stock a buy. What happened in the latest quarter matters, but not as much as longer-term business quality and valuation when deciding whether to invest in this stock. For more on Teladoc, read our full research report here (it’s free).