Security and Aerospace company Lockheed Martin (NYSE: LMT) reported Q3 2026 results topping the market’s revenue expectations, with sales up 11.3% year on year to $20.71 billion. The company expects the full year’s revenue to be around $81 billion, close to analysts’ estimates. Its GAAP profit of $7.97 per share was 6% above analysts’ consensus estimates.
Is now the time to buy Lockheed Martin? Find out by accessing our full research report, it’s free.
Lockheed Martin (LMT) Q3 2026 highlights:
- Revenue: $20.71 billion vs analyst estimates of $20.44 billion (11.3% year-on-year growth, 1.3% beat)
- EPS (GAAP): $7.97 vs analyst estimates of $7.52 (6% beat)
- The company slightly lifted its revenue guidance for the full year to $81 billion at the midpoint from $80.75 billion
- EPS (GAAP) guidance for the full year is $30.55 at the midpoint, roughly in line with what analysts were expecting
- Operating Margin: 11.8%, in line with the same quarter last year
- Free Cash Flow Margin: 14.5%, down from 18% in the same quarter last year
- Backlog: $292 billion at quarter end, up 63.1% year on year
- Market Capitalization: $127.3 billion
"Our strong third quarter performance underscores Lockheed Martin's continuing leadership in the development and delivery of advanced and reliable defense technology solutions. Every day, our research, engineering and production teams are putting highly effective and scalable capabilities in the field. We strive to improve mission performance on a continuous basis by combining proven systems like Aegis, F-35, and Hellfire with the latest digital technologies including AI and Autonomy. We are doing this by integrating our internal innovative solutions with those of start-ups, new entrants into our industry, and commercial technology leaders." said Lockheed Martin Chairman, President and CEO Jim Taiclet.
Company overview
Headquartered in Maryland, Famous for the F-35 aircraft, Lockheed Martin (NYSE: LMT) specializes in defense, space, homeland security, and information technology products.
Revenue growth
A company’s long-term performance is an indicator of its overall quality. Even a bad business can shine for one or two quarters, but a top-tier one grows for years. Regrettably, Lockheed Martin’s sales grew at a sluggish 3.6% compounded annual growth rate over the last five years. This was below our standard for the industrials sector and is a tough starting point for our analysis.
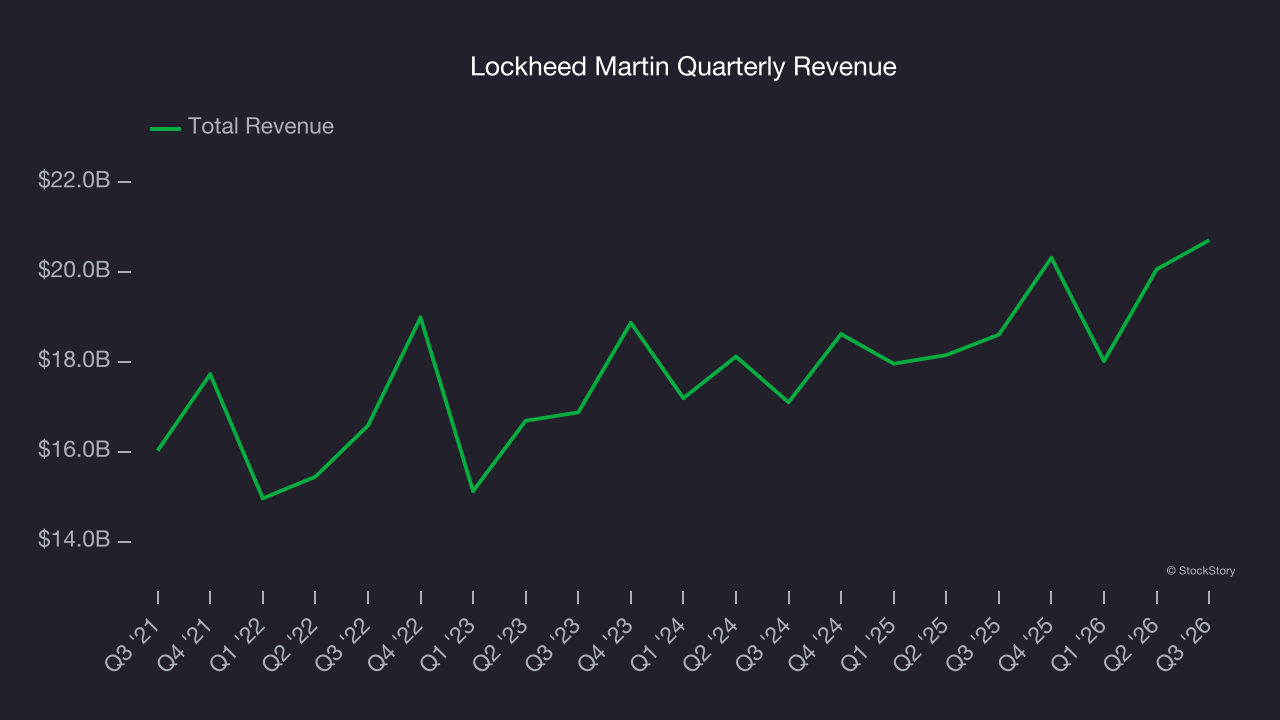
Long-term growth is the most important, but within industrials, a half-decade historical view may miss new industry trends or demand cycles. Lockheed Martin’s annualized revenue growth of 5.3% over the last two years is above its five-year trend, which is encouraging. 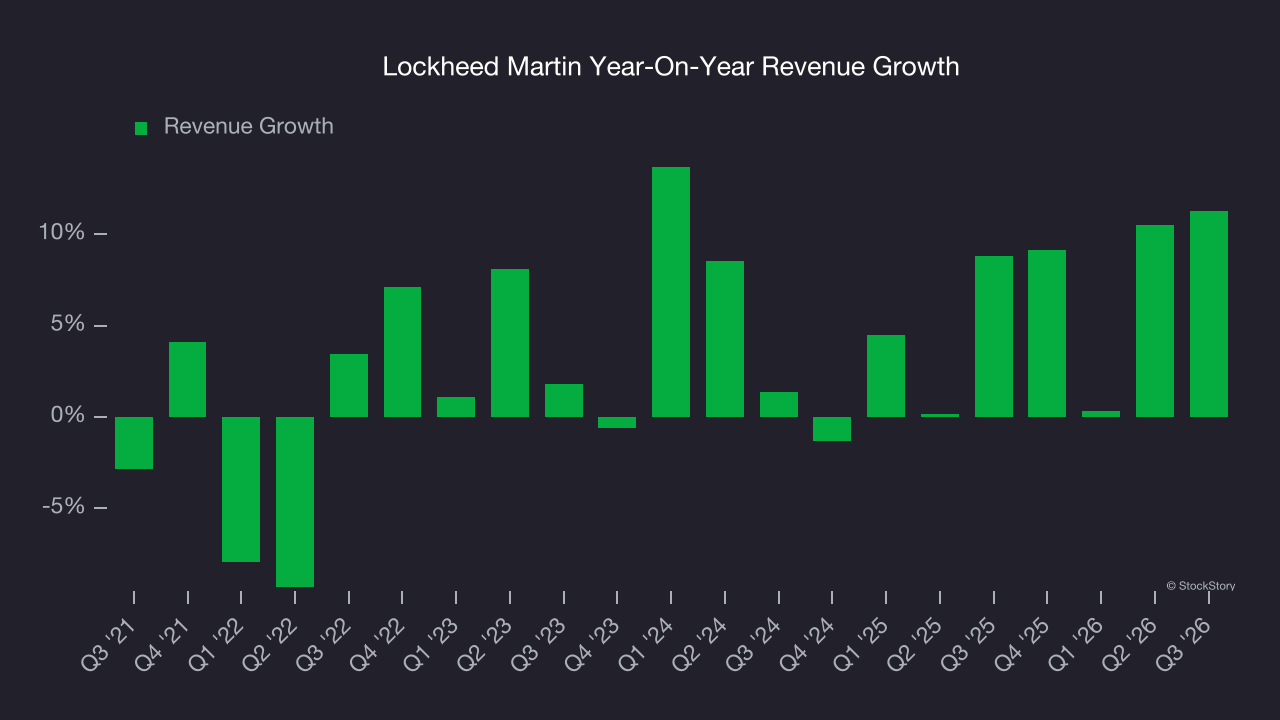
Lockheed Martin also reports its backlog, or the value of its outstanding orders that have not yet been executed or delivered. Lockheed Martin’s backlog reached $292 billion in the latest quarter and averaged 20.1% year-on-year growth over the last two years. Because this number is better than its revenue growth, we can see the company accumulated more orders than it could fulfill and deferred revenue to the future. This could imply elevated demand for Lockheed Martin’s products and services but raises concerns about capacity constraints. 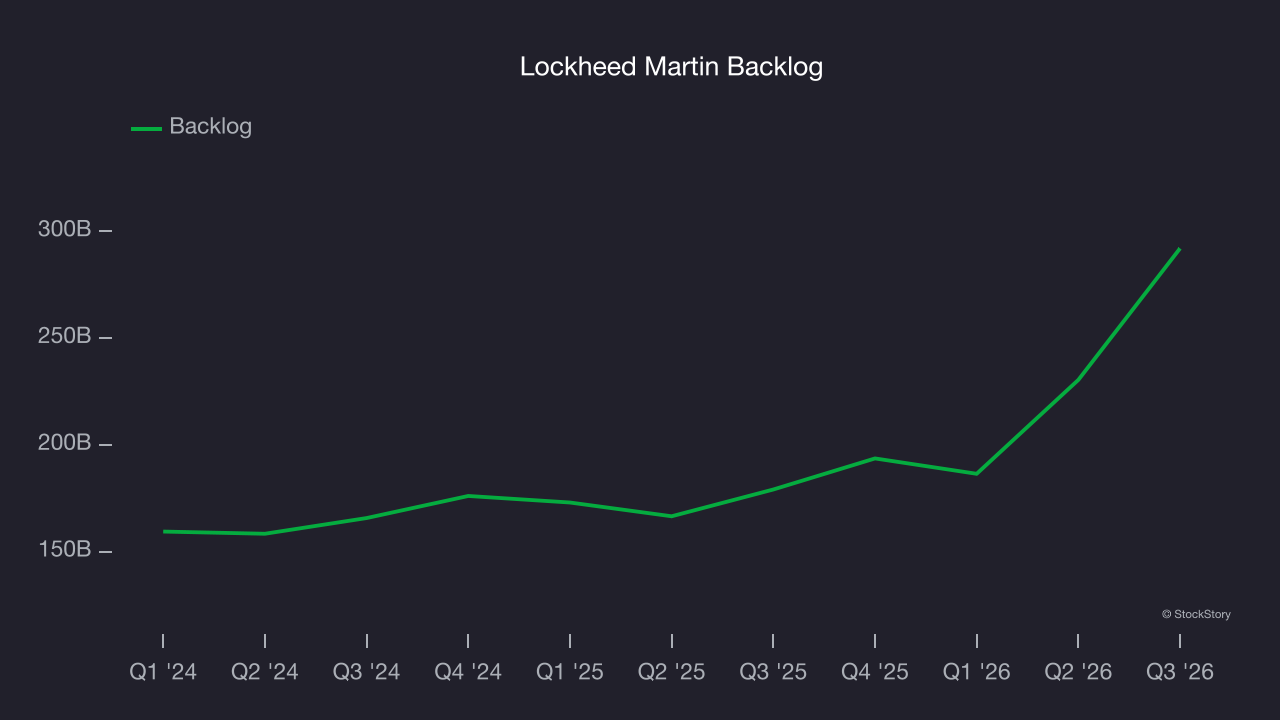
This quarter, Lockheed Martin reported year-on-year revenue growth of 11.3%, and its $20.71 billion of revenue exceeded Wall Street’s estimates by 1.3%.
Looking ahead, sell-side analysts expect revenue to grow 7.2% over the next 12 months. Although this projection indicates its newer products and services will spur better top-line performance, it is still below average for the sector.
WHILE YOU’RE HERE: The Next Palantir? One satellite company captures images of every point on Earth. Every single day. The Pentagon wants it. Hedge funds are using it to beat earnings. You’ve probably never heard of it.
This is what the early days of Palantir looked like before it became a giant. Same playbook. Different technology. If you missed Palantir, you need to see this. Claim The Stock Ticker for Free HERE.
Operating margin
Operating margin is a key measure of profitability. Think of it as net income - the bottom line - excluding the impact of taxes and interest on debt, which are less connected to business fundamentals.
Lockheed Martin has managed its cost base well over the last five years. It demonstrated solid profitability for an industrials business, producing an average operating margin of 11.5%.
Looking at the trend in its profitability, Lockheed Martin’s operating margin decreased by 1.4 percentage points over the last five years. This raises questions about the company’s expense base because its revenue growth should have given it leverage on its fixed costs, resulting in better economies of scale and profitability.
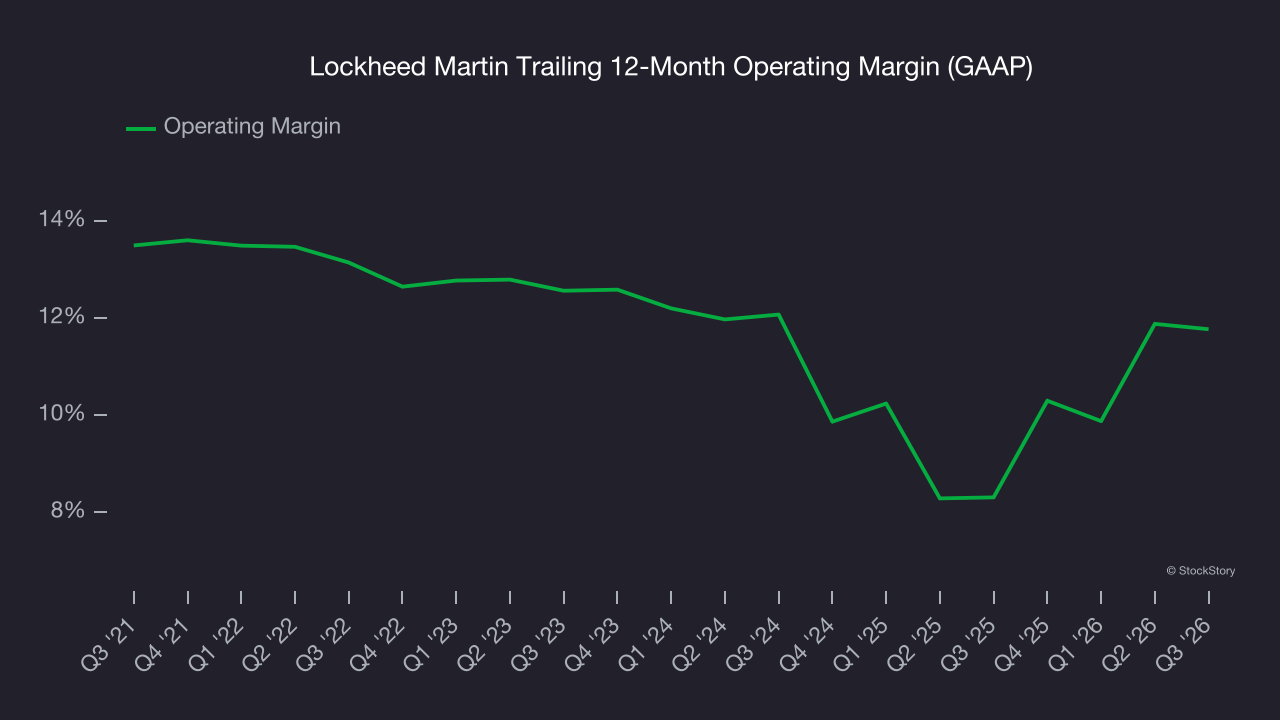
This quarter, Lockheed Martin generated an operating margin profit margin of 11.8%, in line with the same quarter last year. This indicates the company’s overall cost structure has been relatively stable.
Earnings per share
Revenue trends explain a company’s historical growth, but the long-term change in earnings per share (EPS) points to the profitability of that growth — for example, a company could inflate its sales through excessive spending on advertising and promotions.
Lockheed Martin’s unimpressive 5.4% annual EPS growth over the last five years aligns with its revenue performance. This tells us it maintained its per-share profitability as it expanded.
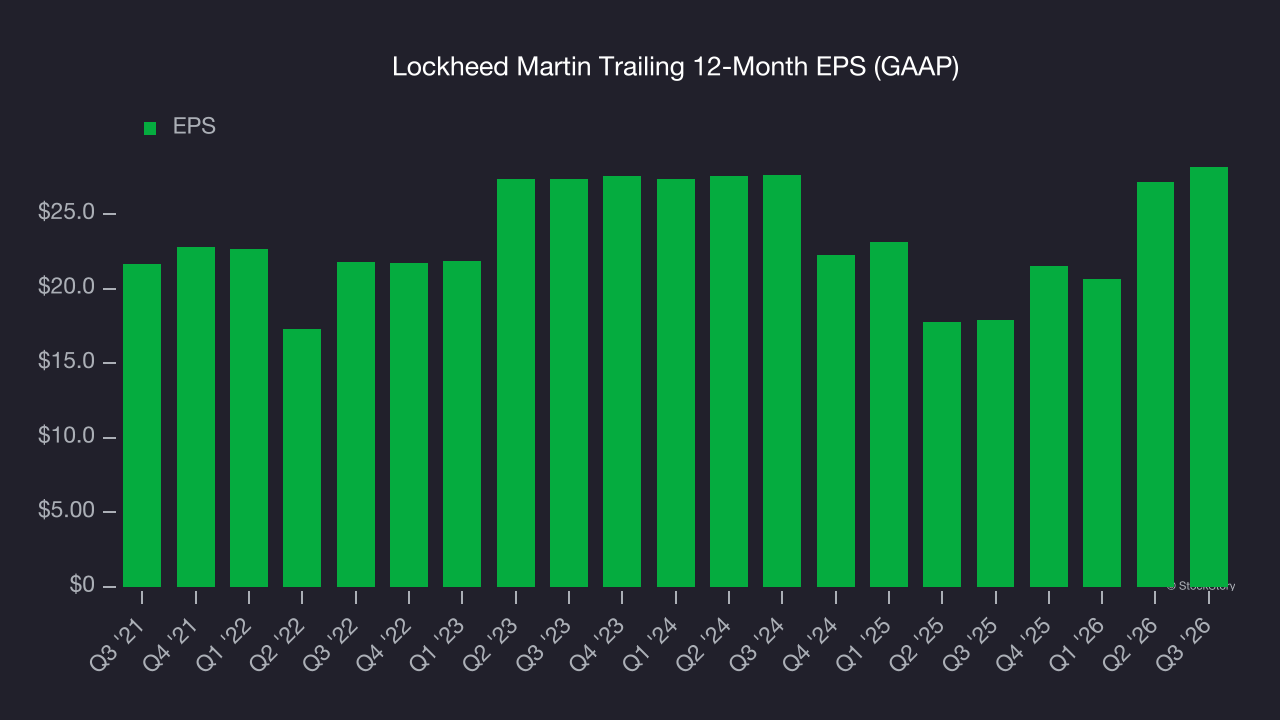
Like with revenue, we analyze EPS over a more recent period because it can provide insight into an emerging theme or development for the business.
For Lockheed Martin, EPS didn’t budge over the last two years, a regression from its five-year trend. We hope it can revert to earnings growth in the coming years.
In Q3, Lockheed Martin reported EPS of $7.97, up from $6.95 in the same quarter last year. This print beat analysts’ estimates by 6%. Over the next 12 months, Wall Street expects Lockheed Martin’s full-year EPS to grow 13.4% from $28.15 to $31.92.
Key takeaways from Lockheed Martin’s Q3 results
It was good to see Lockheed Martin narrowly top analysts’ revenue expectations this quarter. We were also glad its EPS outperformed Wall Street’s estimates. Overall, this print had some key positives. The stock traded up 3.3% to $570.13 immediately following the results.
Big picture, is Lockheed Martin a buy here and now? We think that the latest quarter is only one piece of the longer-term business quality puzzle. Quality, when combined with valuation, can help determine if the stock is a buy. We cover that in our actionable full research report which you can read here (it’s free).