Waste management company Waste Connections (NYSE: WCN) reported Q3 2026 results beating Wall Street’s revenue expectations, with sales up 7.3% year on year to $2.64 billion. The company expects the full year’s revenue to be around $10.09 billion, close to analysts’ estimates. Its non-GAAP profit of $1.58 per share was 3.9% above analysts’ consensus estimates.
Is now the time to buy Waste Connections? Find out by accessing our full research report, it’s free.
Waste Connections (WCN) Q3 2026 highlights:
- Revenue: $2.64 billion vs analyst estimates of $2.61 billion (7.3% year-on-year growth, 1.2% beat)
- Adjusted EPS: $1.58 vs analyst estimates of $1.52 (3.9% beat)
- Adjusted EBITDA: $895.8 million vs analyst estimates of $886 million (34% margin, 1.1% beat)
- The company slightly lifted its revenue guidance for the full year to $10.09 billion at the midpoint from $10.04 billion
- Operating Margin: 20.5%, up from 17.9% in the same quarter last year
- Free Cash Flow Margin: 15.1%, similar to the same quarter last year
- Market Capitalization: $42.72 billion
Company overview
Operating a network of municipal solid waste landfills in the U.S. and Canada, Waste Connections (NYSE: WCN) is North America's third-largest waste management company providing collection, disposal, and recycling services.
Revenue growth
A company’s long-term sales performance can indicate its overall quality. Any business can have short-term success, but a top-tier one grows for years. Thankfully, Waste Connections’s 10.9% annualized revenue growth over the last five years was impressive. Its growth beat the average industrials company and shows its offerings resonate with customers.
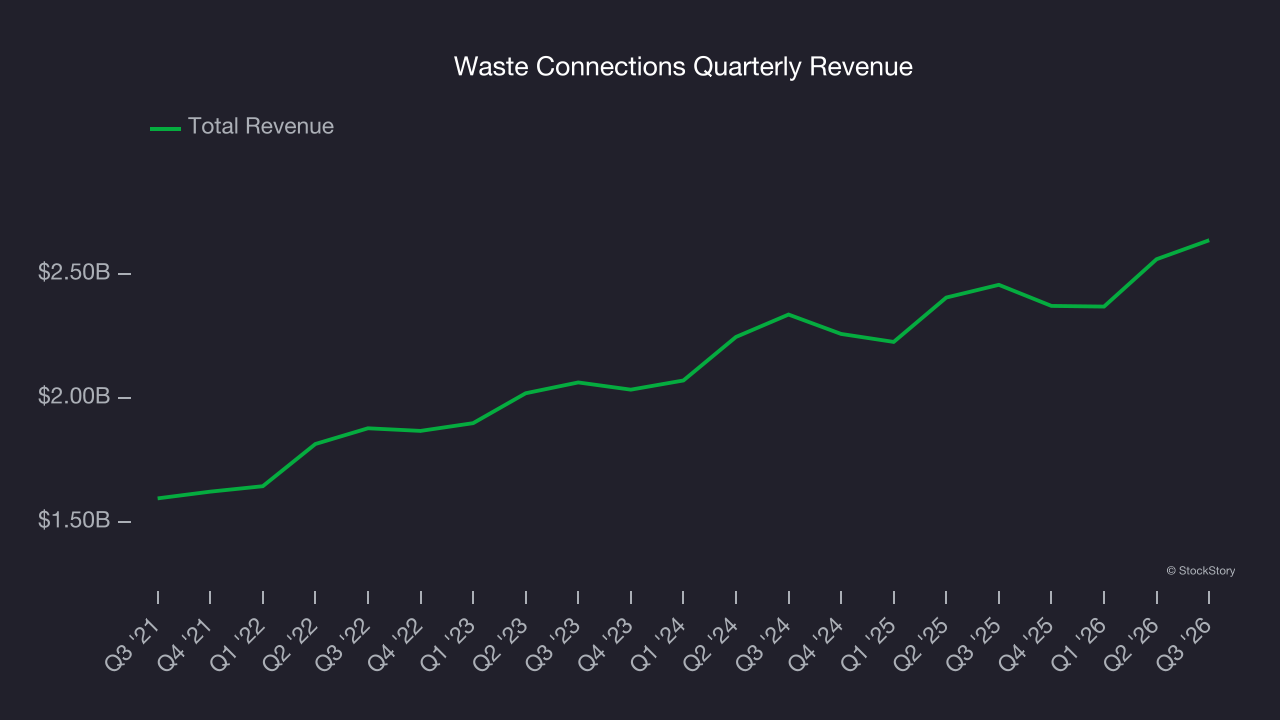
We at StockStory place the most emphasis on long-term growth, but within industrials, a half-decade historical view may miss cycles, industry trends, or a company capitalizing on catalysts such as a new contract win or a successful product line. Waste Connections’s recent performance shows its demand has slowed significantly as its annualized revenue growth of 6.9% over the last two years was well below its five-year trend. 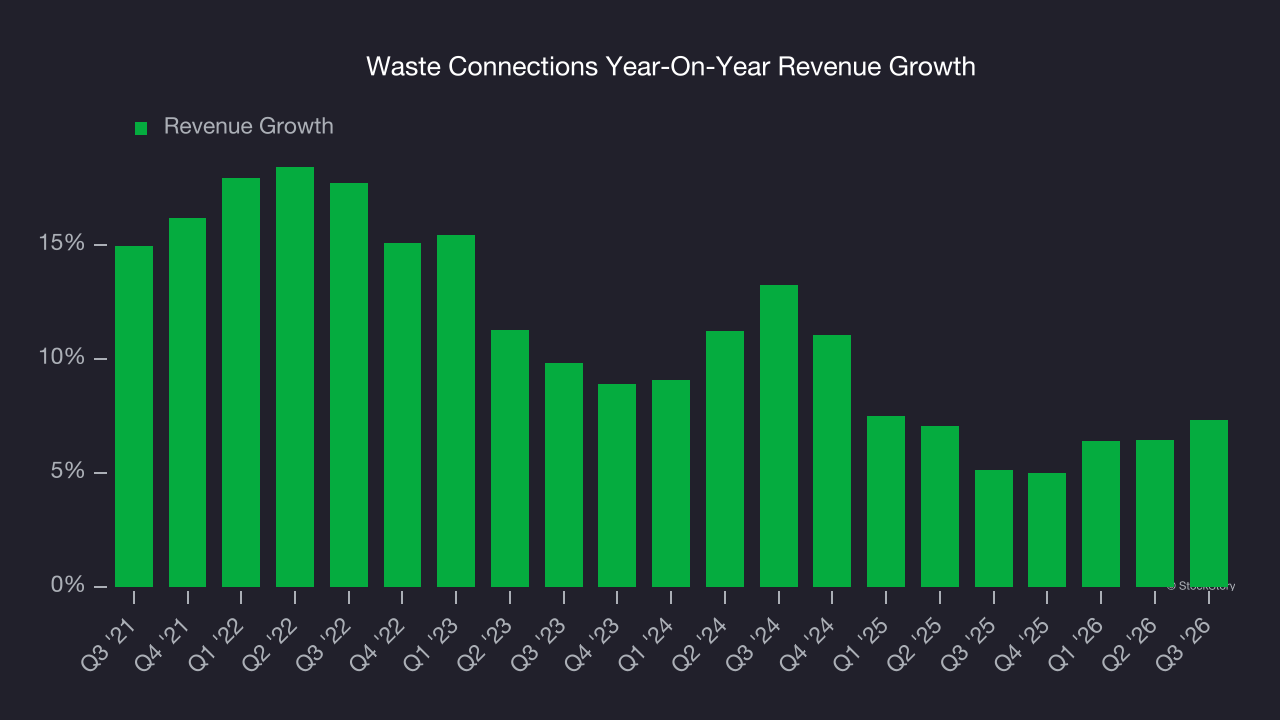
This quarter, Waste Connections reported year-on-year revenue growth of 7.3%, and its $2.64 billion of revenue exceeded Wall Street’s estimates by 1.2%.
Looking ahead, sell-side analysts expect revenue to grow 5.3% over the next 12 months, a slight deceleration versus the last two years. This projection is underwhelming and indicates its products and services will face some demand challenges.
ONE MORE THING: The $21 AI Application Stock Wall Street Forgot. While Wall Street obsesses over who’s building AI, one company is already using it to print money. And nobody’s paying attention.
AI chip stocks trade at ridiculous valuations. This company processes a trillion consumer signals monthly using AI and trades at a third of the price. The gap won’t last. The institutions will figure it out. You need to see this first. Read the FREE Report Before They Notice.
Operating margin
Operating margin is one of the best measures of profitability because it tells us how much money a company takes home after procuring and manufacturing its products, marketing and selling those products, and most importantly, keeping them relevant through research and development.
Waste Connections’s operating margin has risen over the last 12 months and averaged 16% over the last five years. On top of that, its profitability was elite for an industrials business thanks to its efficient cost structure and economies of scale. This result isn’t surprising as its high gross margin gives it a favorable starting point.
Analyzing the trend in its profitability, Waste Connections’s operating margin might have fluctuated slightly but has generally stayed the same over the last five years. This raises questions about the company’s expense base because its revenue growth should have given it leverage on its fixed costs, resulting in better economies of scale and profitability.
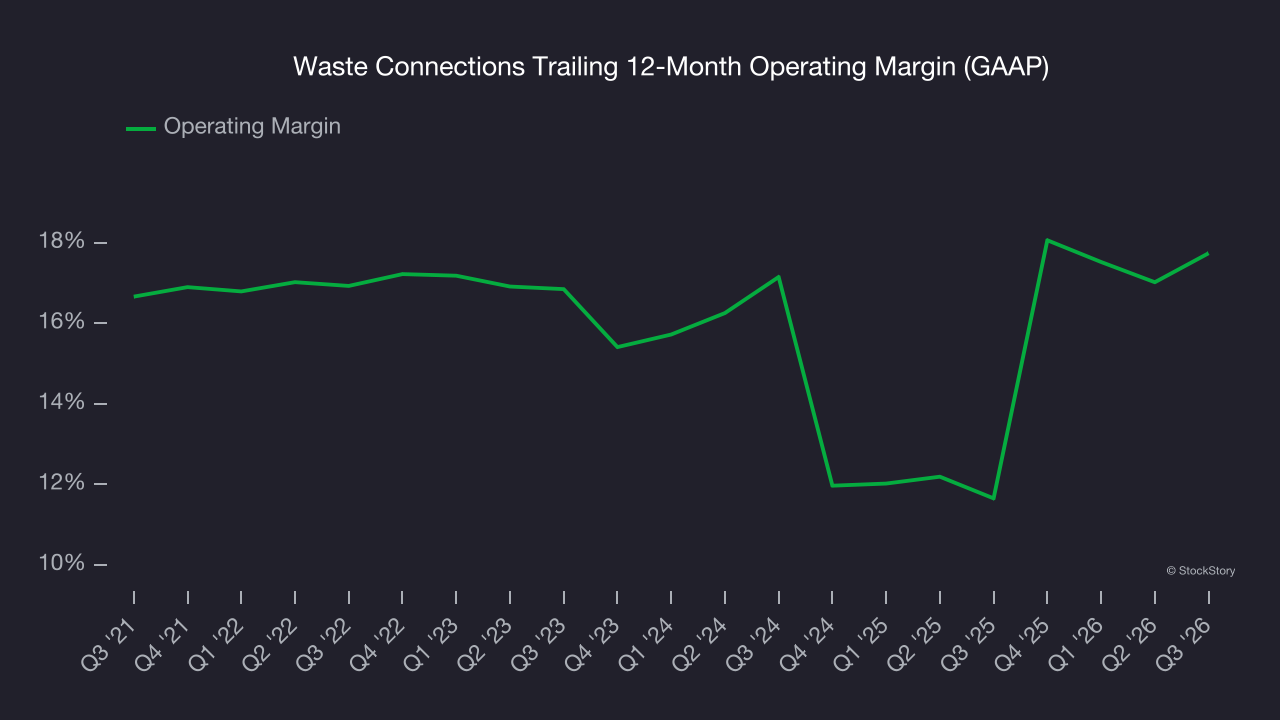
This quarter, Waste Connections generated an operating margin profit margin of 20.5%, up 2.7 percentage points year on year. The increase was encouraging, and because its operating margin rose more than its gross margin, we can infer it was more efficient with expenses such as marketing, R&D, and administrative overhead.
Earnings per share
We track the long-term change in earnings per share (EPS) for the same reason as long-term revenue growth. Compared to revenue, however, EPS highlights whether a company’s growth is profitable.
Waste Connections’s remarkable 12.7% annual EPS growth over the last five years aligns with its revenue performance. This tells us its incremental sales were profitable.
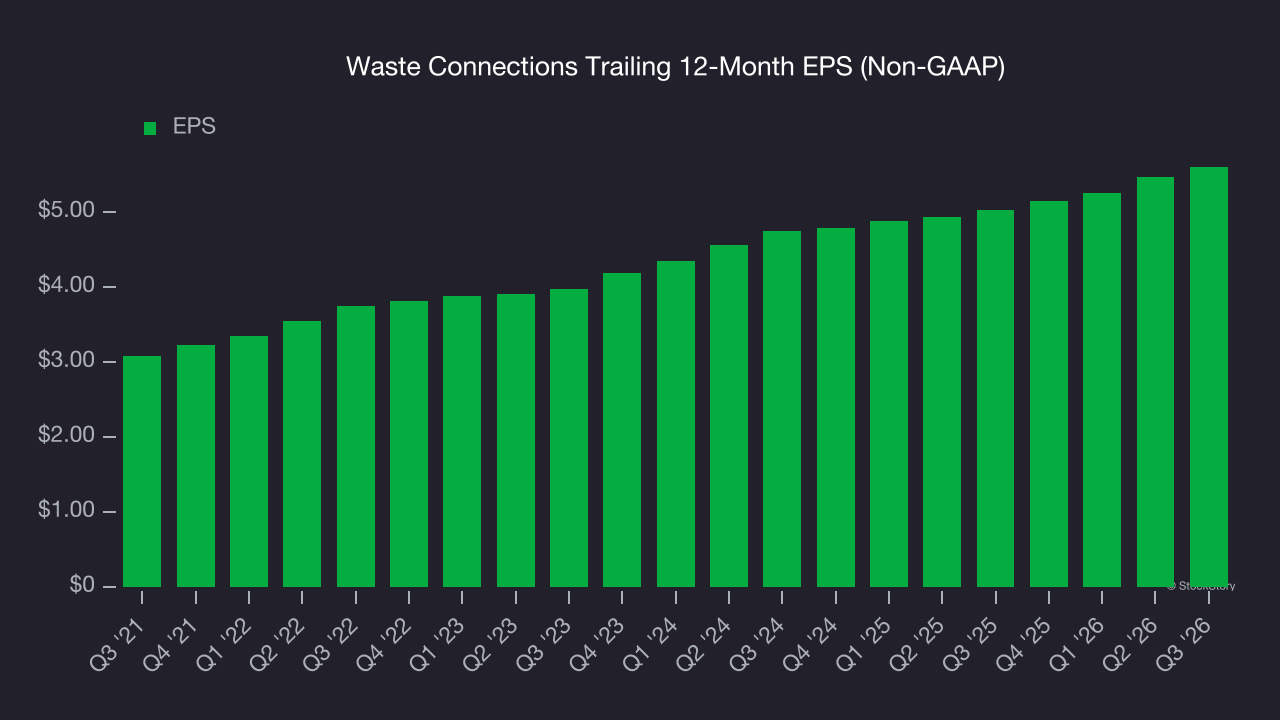
Like with revenue, we analyze EPS over a shorter period to see if we are missing a change in the business.
For Waste Connections, its two-year annual EPS growth of 8.7% was lower than its five-year trend. We hope its growth can accelerate in the future.
In Q3, Waste Connections reported adjusted EPS of $1.58, up from $1.44 in the same quarter last year. This print beat analysts’ estimates by 3.9%. Over the next 12 months, Wall Street expects Waste Connections’s full-year EPS to grow 7.2% from $5.60 to $6.00.
Key takeaways from Waste Connections’s Q3 results
It was good to see Waste Connections narrowly top analysts’ revenue expectations this quarter. We were also glad its EPS outperformed Wall Street’s estimates. Overall, this print had some key positives. The stock traded up 3% to $173.14 immediately after reporting.
Is Waste Connections an attractive investment opportunity right now? If you’re making that decision, you should consider the bigger picture of valuation, business qualities, as well as the latest earnings. We cover that in our actionable full research report which you can read here (it’s free).