Zoetis has gotten torched over the last six months - since April 2026, its stock price has dropped 37.6% to $75.34 per share. This was partly due to its softer quarterly results and may have investors wondering how to approach the situation.
Is now the time to buy Zoetis, or should you be careful about including it in your portfolio? Check out our in-depth research report to see what our analysts have to say, it’s free.
Why Is Zoetis Not Exciting?
Even with the cheaper entry price, we’re passing on Zoetis for now. Here are three reasons why ZTS doesn’t excite us, plus one stock we’d rather own.
1. Long-Term Revenue Growth Disappoints
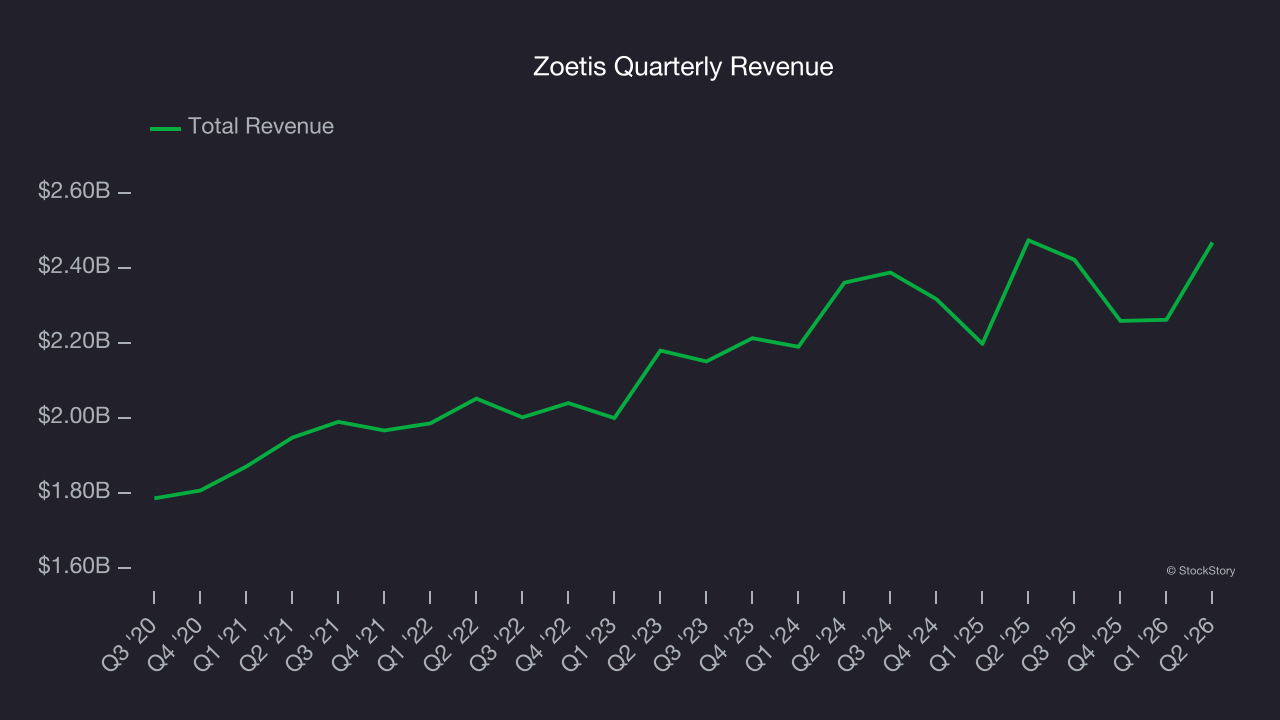
Reviewing a company’s long-term sales performance reveals insights into its quality. Any business can have short-term success, but a top-tier one grows for years. Over the last five years, Zoetis grew its sales at a mediocre 4.9% compounded annual growth rate. This fell short of our benchmark for the healthcare sector.
2. Projected Revenue Growth Shows Limited Upside
Forecasted revenues by Wall Street analysts signal a company’s potential. Predictions may not always be accurate, but accelerating growth typically boosts valuation multiples and stock prices while slowing growth does the opposite.
Over the next 12 months, sell-side analysts expect Zoetis’s revenue to stall, a deceleration versus its 4.9% annualized growth for the past five years. This projection doesn’t excite us and implies its products and services will face some demand challenges.
3. New Investments Aren’t Moving the Needle
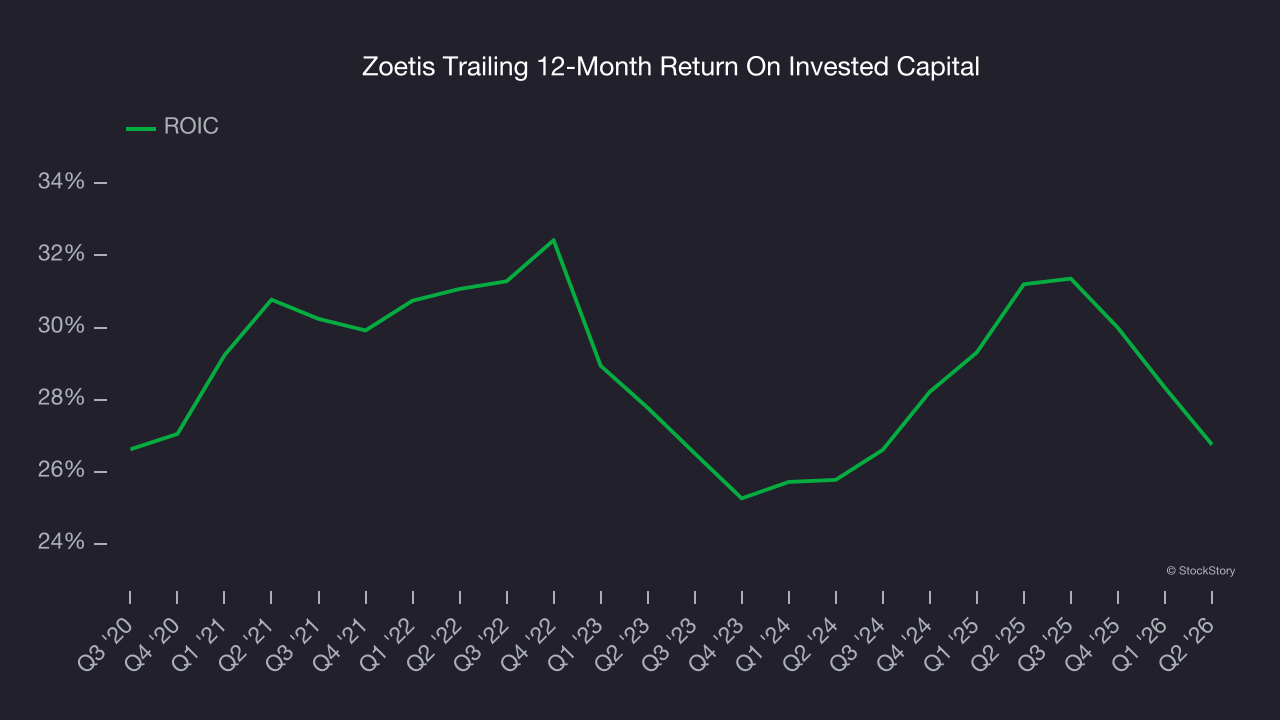
We like to invest in businesses with high returns, but the trend in a company’s ROIC can also be an early indicator of future business quality.
Uneventfully, Zoetis’s ROIC has stayed the same over the last few years. Given the company’s underwhelming financial performance in other areas, we’d like to see its returns improve before recommending the stock.
Final Judgment
Zoetis isn’t a terrible business, but it isn’t one of our picks. After the recent drawdown, the stock trades at 12× forward P/E (or $75.34 per share). While this valuation is reasonable, we don’t really see a big opportunity at the moment. We’re fairly confident there are better investments elsewhere. Let us point you toward one of our all-time favorite software stocks.
High-Quality Stocks for All Market Conditions
WHILE YOU’RE HERE: Top 9 Market-Beating Stocks. The best stocks don’t just beat the market once. They do it again. And again. Robust revenue growth, rising free cash flow, returns on capital that leave their competition in the dust. The market has already rewarded these businesses.
But our AI platform says the party isn’t over. Find out which 9 stocks made the cut this week — FREE. Get Our Top 9 Market-Beating Stocks for Free HERE.
Stocks that have made our list include now familiar names such as Nvidia (+1,460% between June 2020 and June 2025) as well as under-the-radar businesses like the once-micro-cap company Kadant (+214% between June 2020 and June 2025). Find your next big winner with StockStory today.